
Southside Bancshares And 2 Top Dividend Stocks
Global trade is fragmenting as more tariffs and barriers go up, which makes smooth economic growth less certain than it once felt. In that kind of world, reliable cash payouts from established dividend payers can matter more than chasing the next hot story. This article looks at three high-yield companies with dividend streams above 3% that screening suggests are well covered, steadily growing and relatively stable.
The picks in this article are just a small sample, and the full Dividend Powerhouses screen surfaced another 170 companies with yields above 3% and similarly robust stories that are not covered here. To see the wider opportunity set for yourself, head straight to the Dividend Powerhouses (3%+ Yield) screener to identify, analyze and focus on the higher conviction ideas that fit your income goals.
Southside Bancshares (SBSI)
Overview: Southside Bancshares is a Texas-based bank holding company that collects deposits and makes consumer, commercial, and real estate loans that help fund its dividend.
Operations: Southside Bancshares generates about US$245 million in banking revenue, almost entirely from its United States operations.
Market Cap: US$916 million
For income-focused investors, Southside Bancshares links its traditional deposit and lending franchise directly to a cash dividend that screens as both generous and well covered.
"Exposure to ongoing population and job growth across Texas continues to drive strong new loan production and commercial deposit growth, positioning the bank to benefit from higher loan balances and fee income, which should support future revenue and earnings expansion."
The real test for that dividend story sits in how one pressure on profitability evolves over the next few years.
That pressure point is exactly where Southside Bancshares could surprise. The full narrative for Southside Bancshares unpacks how that risk, dividend policy and loan growth are really interacting.

NIKE (NKE)
Overview: NIKE designs and sells athletic footwear, apparel and related gear worldwide, using its global brands to convert sports demand into cash.
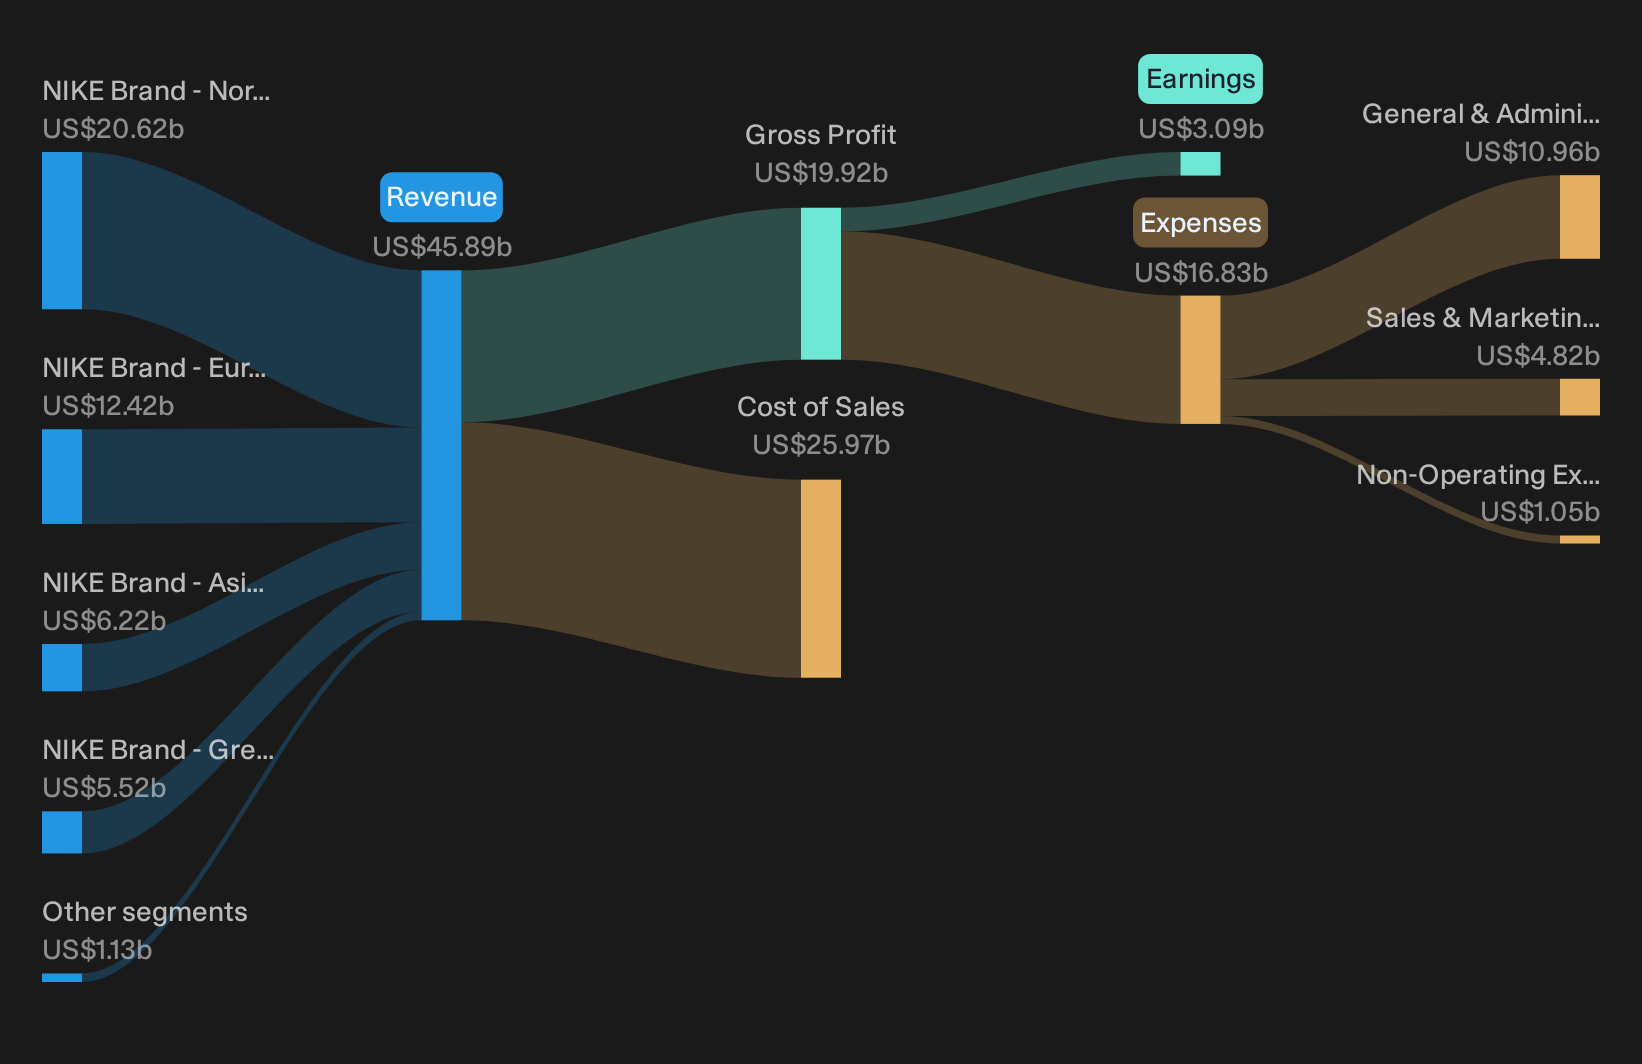
Operations: NIKE generates most of its revenue from the NIKE Brand in North America at US$20.6b, with further sales across Europe, Greater China, Asia Pacific, Latin America and Converse.
Market Cap: US$50.3b
NIKE matters for a dividend-focused screen because its sportswear engine throws off the cash that funds a long-running, shareholder-friendly payout.
"However, there are some risks for the company, represented by the High uncertainty rating, showing that Nike, despite having a history of success, needs to keep reinventing itself by providing, as always, great products to its clients."
For dividend investors, what happens to NIKE’s cash generation if one key pressure on margins persists will likely dictate how dependable that payout feels.
That margin pressure is only part of the story, and the full narrative for NIKE shows how NIKE’s brand strength and product engine could help cash generation continue to grow.
Peoples Bancorp (PEBO)
Overview: Peoples Bancorp is a community-focused financial group that uses its deposit base and loan book to support a high, recurring dividend.
Operations: Peoples Bancorp generates about US$435 million of community banking revenue in the United States through lending, deposits and related services.
Market Cap: US$1.3b
For income investors, Peoples Bancorp ties its 3%+ yield directly to a traditional community banking engine that aims for steady net interest and fee income rather than flashy side businesses.
"Robust loan growth across diversified categories, alongside population and business migration to secondary and tertiary markets where the bank operates, suggests Peoples Bancorp is well positioned to benefit from increased loan demand and local economic strength, which may support future revenue and earnings expansion."
What happens if one still-muted pressure on returns starts to ease could make a real difference to how durable that payout feels.
If that pressure on returns starts easing, the full narrative for Peoples Bancorp shows whether Peoples Bancorp’s dividend story is quietly accelerating beneath the surface.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time a breakout story is flying, the best entry points can be gone. Scan these curated shortlists while it matters and act now.
- Explore potential early momentum in established miners by checking which producers make the cut in the 36 elite gold producer stocks before they are fully caught on every radar.
- Look at future-facing infrastructure plays by zeroing in on power specialists filtered through the 40 power grid technology and infrastructure stocks while sentiment around grid upgrades is still taking shape.
- Monitor the next automation wave by filtering manufacturers and enablers inside the 89 robotics and automation stocks while many of these stories remain less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com