
Halozyme Therapeutics (HALO) Adds Jim Daly As Valuation Questions Follow
Halozyme Therapeutics (HALO) stock is back in focus after the company appointed veteran biopharma executive James “Jim” Daly to its Board of Directors, giving investors fresh data to assess boardroom experience.
At a share price of US$109.86, Halozyme Therapeutics has seen a 36% 90 day share price return and a 56.25% year to date share price return, while the 1 year total shareholder return of 59.26% and 3 year total shareholder return of 194.77% point to momentum that investors are still watching closely as boardroom changes unfold.
Compare Halozyme Therapeutics' recent boardroom catalyst with other potential breakout opportunities by scanning our hand picked 19 high quality undiscovered gems that feature strong fundamentals and room for a bigger story.
The recent surge in Halozyme Therapeutics could signal investors are reassessing the underlying enzyme royalty engine rather than just reacting to a board appointment. To test that view, it helps to see what the current price implies.
Most Popular Narrative: 10.4% Overvalued
Halozyme Therapeutics last closed at $109.86, compared with a widely followed fair value estimate of $99.56 that is built on long duration royalties and a specific earnings path. This gives you a clear yardstick to compare the recent rally against.
The current valuation and this narrative’s fairly valued, bullish stance imply the market already prices in long duration royalty streams from existing and future ENHANZE and Hypercon programs along with disciplined capital returns and balance sheet management.
See why 66 investors see Halozyme Therapeutics as 10% overvalued.
Result: Fair Value of $99.56 (OVERVALUED)
Still, the Halozyme Therapeutics story can change quickly if rival subcutaneous platforms gain share, or if reimbursement and pricing pressure bite into future royalty economics.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View: Halozyme Therapeutics Through The P/E Lens
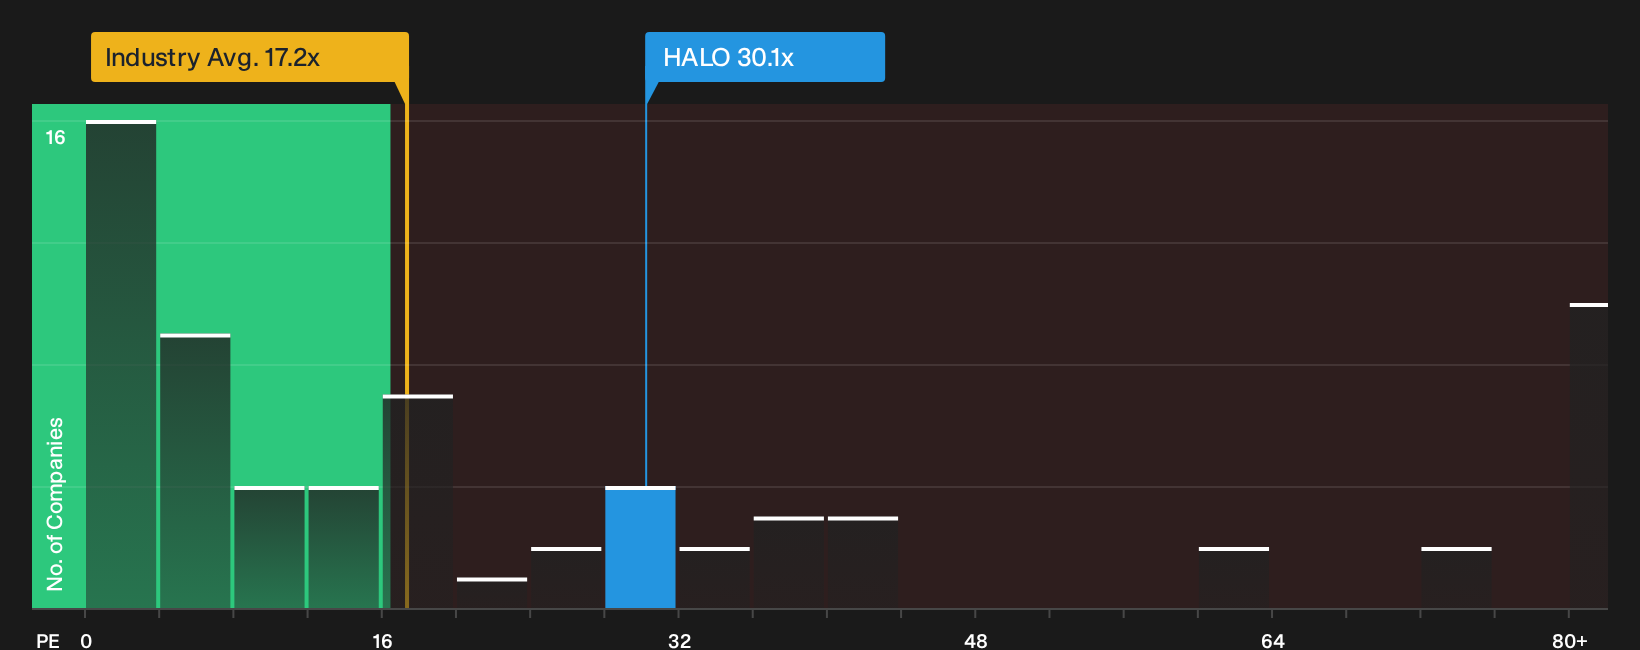
The first narrative frames Halozyme Therapeutics as about 10.4% overvalued versus a US$99.56 fair value estimate. Using a simple P/E check tells a different story. HALO trades on 30.1x earnings, which is far above the US Biotechs industry on 17.2x and also above its own fair ratio at 21.9x.
That gap suggests investors are already paying a sizeable premium for Halozyme Therapeutics compared with both peers and where the ratio could move if sentiment cools. The question for you is whether the royalty engine justifies keeping that premium intact or if the multiple eventually drifts toward the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far on Halozyme Therapeutics’ valuation make this a good moment to look under the hood yourself instead of just following the headline move. To weigh the upside potential against the key concerns, run through the 2 key rewards and 3 important warning signs
Looking for more Halozyme Therapeutics sized ideas?
Do not let your research stop at Halozyme Therapeutics. Fresh opportunities keep showing up, and missing the next move usually comes from not looking widely enough.
- Target resilient balance sheets and steady fundamentals by scanning our focused list of solid balance sheet and fundamentals (25 results) that highlight businesses built to handle tougher conditions.
- Zero in on quality at a reasonable price with the carefully filtered 31 high quality undervalued stocks that spotlight companies combining cash flow strength with appealing valuations.
- Hunt for potential future leaders using the curated 8 elite penny stocks with strong financials where smaller businesses with stronger numbers than their size suggests might be hiding in plain sight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com