
What You Can Learn From Charles River Holders Who Are Up 64%
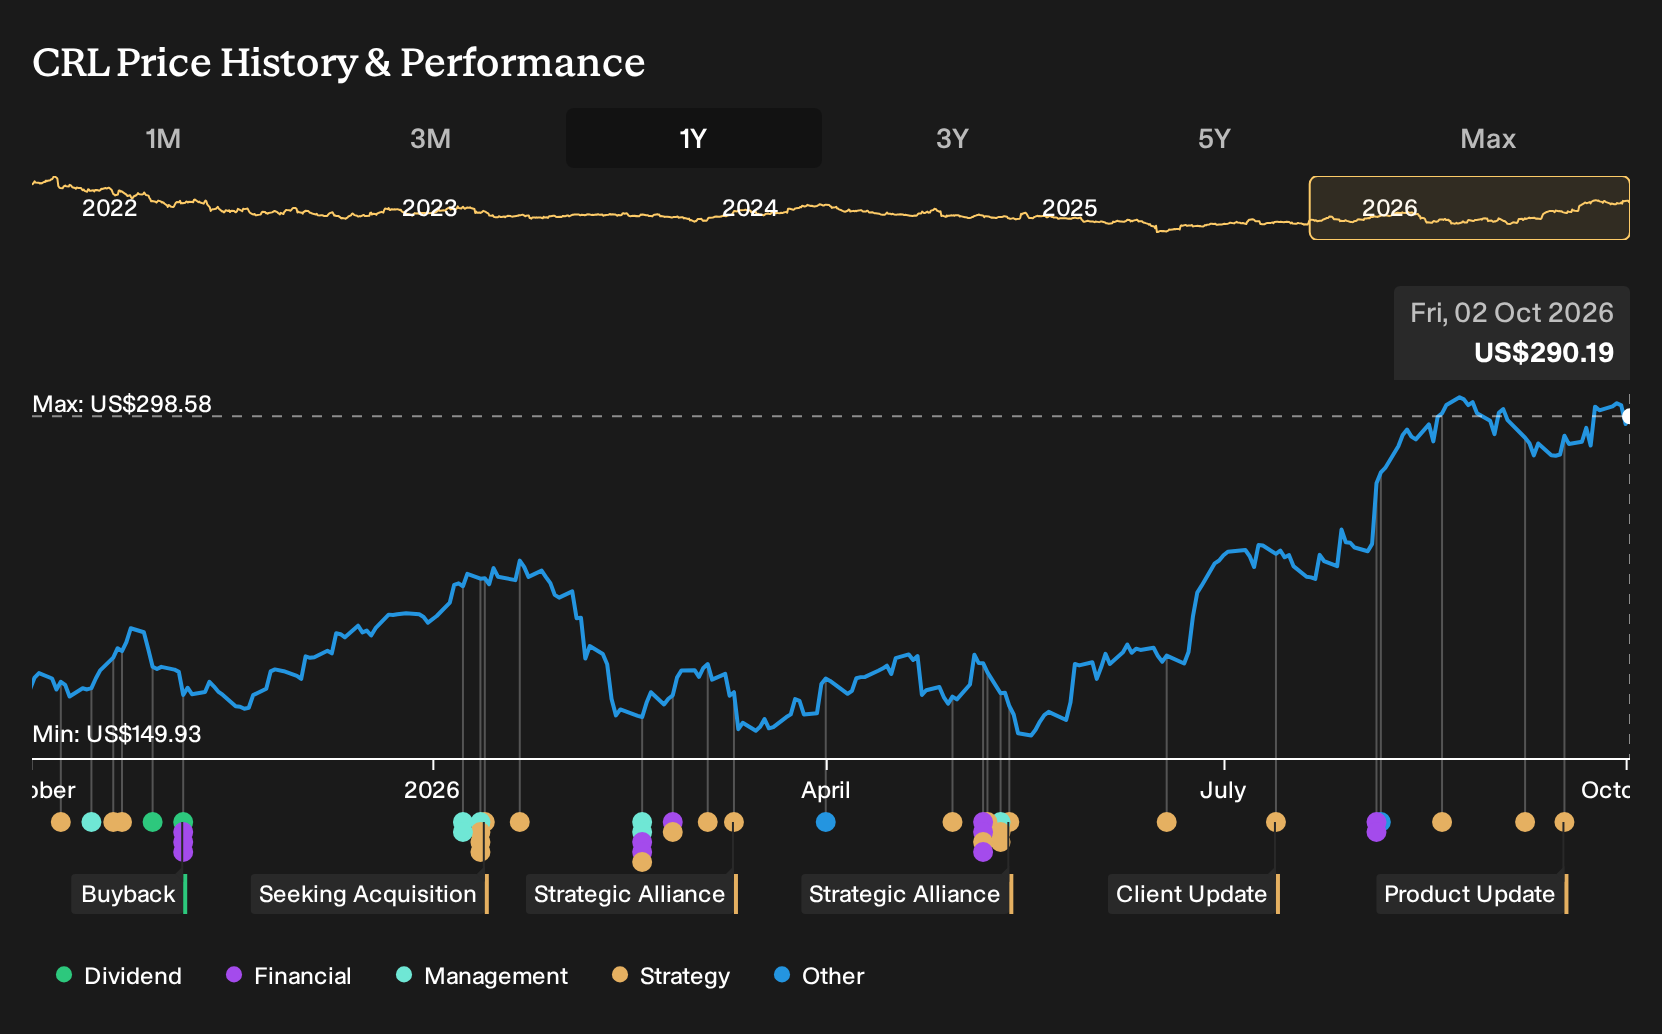
If Charles River Laboratories International sat on your watchlist rather than in your portfolio, the past year may feel like a missed chance. Holding Charles River Laboratories International over the past year would have returned 63.6%, including dividends. If you were staring at it on 2 October 2025, before that move, the key puzzle was simple. Could the company’s push into New Approach Methods and AI-enabled services really offset rising regulatory pressure on traditional animal testing?
Charles River Laboratories International has already moved. Pinpoint other ways to investigate the theme among 35 healthcare AI stocks.
The Two Stories Investors Were Really Debating On Charles River
The shares cost US$175 at the start, and anyone looking at Charles River Laboratories International had to decide which story felt more realistic.
On the bullish side, one camp saw Fair Value at US$200, a rough guide to what the stock might be worth if their assumptions played out. That view leaned on New Approach Methods gaining traction and digital, automated services supporting stronger operating leverage across the business.
The bearish narrative pointed to a Fair Value of US$79.1, arguing that regulatory pressure and alternative testing could shrink Charles River’s core market. Those investors focused on the risk that revenue might decline 11.7% a year over three years even if profit margin reached 6.3%.
What The Results Changed For The Charles River Laboratories International Debate
Charles River Laboratories International leaned hard into New Approach Methods during the period, using AI-enabled pathology, biologics collaborations and vaccine work that all supported the bullish argument that its digital and NAMs push could matter. The hard data pointed the other way. Revenue fell from US$1,032.1m in Q2 2025 to US$1,004.1m in Q2 2026 and net margin moved from 5.1% to a small loss, so profitability in the optimistic case stayed unproven. Overall, the evidence cut both ways.
The lesson travels. When a story turns on new technology offsetting pressure on a legacy product, you can test it quickly by watching two things in the numbers: segment revenue tied to the new offer, and the group net margin trend. If both do not move in the claimed direction, treat the turnaround pitch as work in progress rather than a finished result.
What Charles River’s Run Now Prices In
After a 63.6% gain over the past year, Charles River Laboratories International now trades at US$290. The selected Narrative’s Fair Value sits below the current price, framing today’s quote as already baking in meaningful progress on its modernization and New Approach Methodologies plans.
The key question for anyone paying today’s level is what has to keep working. A buyer needs confidence that digital workflows, NAM uptake and bioanalysis growth will translate into durable margin improvement rather than staying mostly on slide decks.
"The numbers imply the share price already reflects strong execution on cost savings, mix shift toward higher margin segments, and sustained biotech funding support, which leaves limited room for disappointment if demand, pricing, or margin expansion fall short of current expectations."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Another Way Into Health Experiments
Charles River shows how testing risk and regulation can reshape expectations quickly. You might also look at the drug makers that need those answers.
New therapies in cancer, immune disorders and brain health still depend on clear trial results. One large healthcare group spends heavily to keep that pipeline moving.
It pours money into discovery, late stage studies and bolt on deals. The aim is simple. Keep fresh treatments ready as older products age.
Medical devices are part of that push too, from heart procedures to surgical robots and eye care tools. If demand for complex treatment rises, that mix could matter more.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 25% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com