
Should Equity Offering Require Action From Celestica (TSX:CLS) Investors?
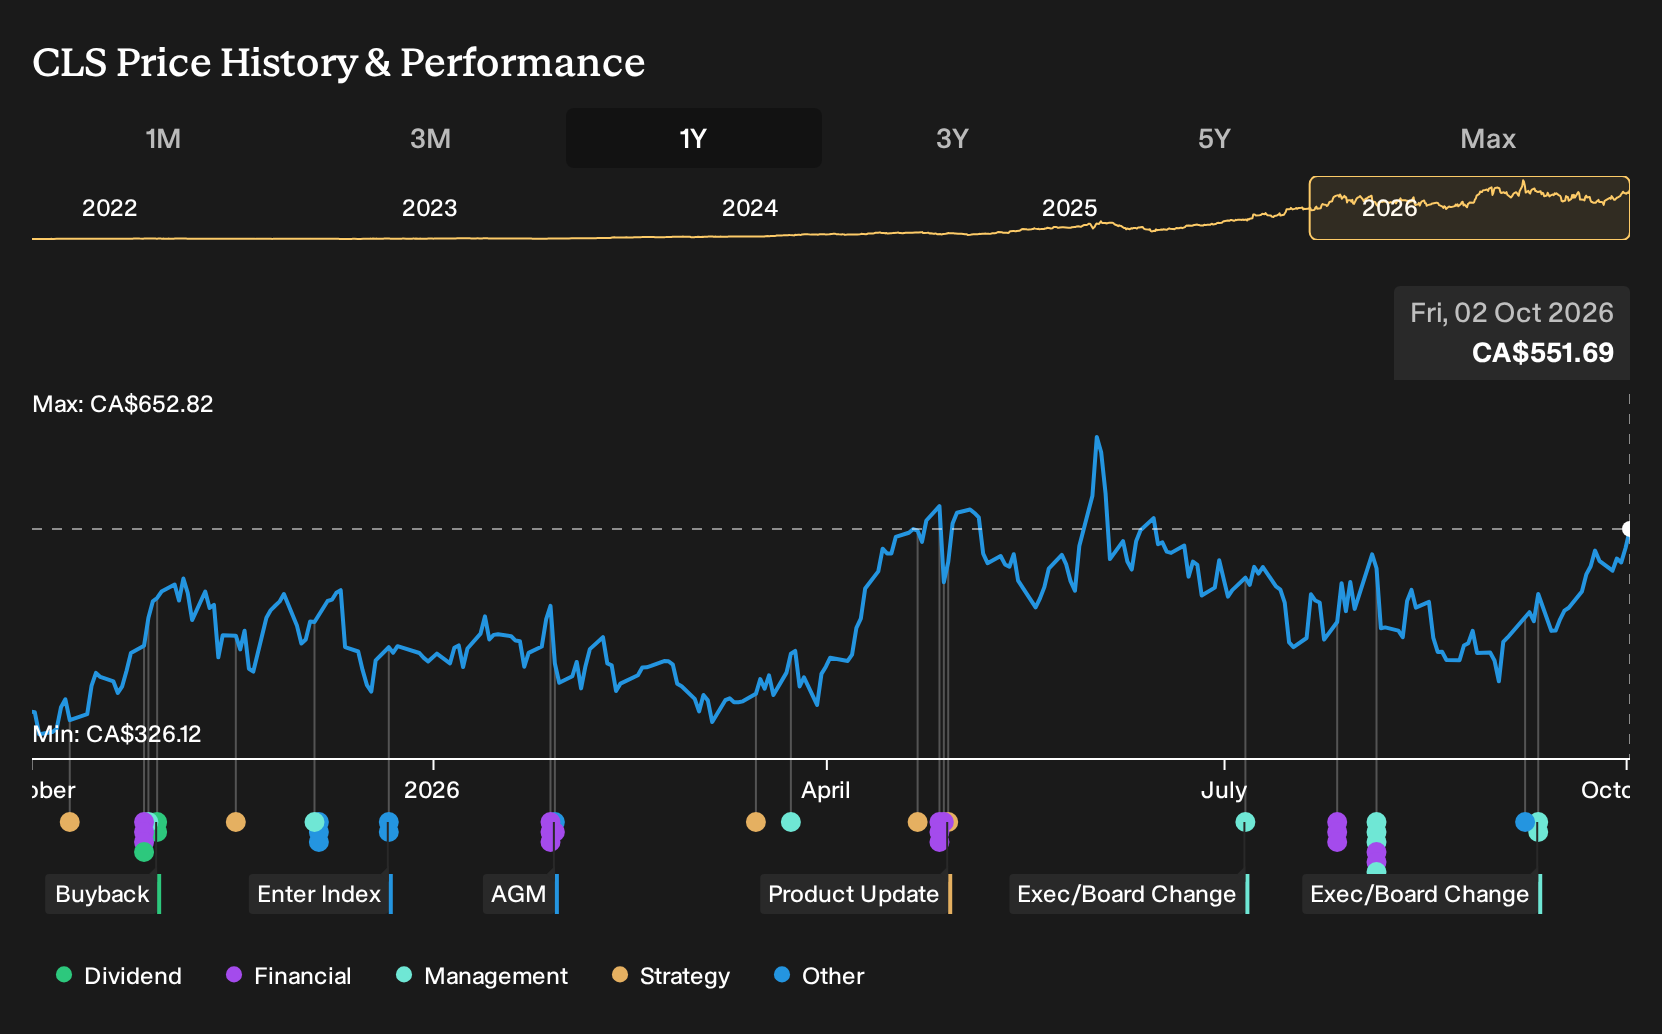
- Celestica recently completed a C$3b equity offering to fund expansion in AI infrastructure and data-center hardware, alongside introducing a new leadership structure and preparing for its 2026 Investor and Analyst Day on October 27.
- The capital raise indicates that Celestica is committing significant resources to scale with hyperscaler AI demand, which could reshape its mix of customers, programs, and long-term cost base.
- We will now explore how Celestica's investment narrative could change in light of its large AI-focused equity raise.
Celestica Investment Narrative Recap
To own Celestica, you need to believe the build out of AI infrastructure and next generation networking gear remains a durable opportunity, and that the firm can keep converting program wins into solid margins. The recent C$3b equity raise strengthens the balance sheet for that expansion, so the near term catalyst still sits in execution on AI heavy customer ramps.
The biggest risk remains concentration in a handful of hyperscaler clients and a revenue base dominated by the CCS segment. If those customers slow orders or shift vendors, the enlarged cost base linked to AI and data center capacity could pressure profitability rather than support it.
The most relevant announcement is the C$3b equity offering aimed at funding global AI infrastructure and data center hardware capacity. That move enlarges Celestica's room to invest in manufacturing footprint, higher speed networking programs, and full rack integration tied to hyperscaler demand.
Fresh equity funding also raises the bar on execution. Investors will likely watch how quickly that capital converts into new 800G and 1.6T program ramps, how much it affects margins in CCS versus ATS, and whether the larger share count is offset by stronger earnings power in AI infrastructure over the next few years.
Celestica's narrative projects $41.7b revenue and $2.7b earnings by 2029. This implies 38.8% yearly revenue growth and an earnings increase of about 2.5x from $1.1b today.
Discover how Celestica's fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about 677 and 774, which points to tight but still varied expectations around Celestica. These views do not yet factor in the new C$3b equity raise or hyperscaler concentration risk, so you are seeing pre-financing opinions that may diverge further as AI spending patterns evolve.
Explore 2 other Celestica fair value estimates, including one that suggests there could be as much as 40% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Celestica research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Celestica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Celestica's overall financial health at a glance.
Looking for more Celestica style investment ideas?
If the Celestica story has you thinking about where else significant capital and solid fundamentals might line up, it can help to widen the lens and scan for other opportunities with clear financial footing.
- For investors who care about balance sheet strength and staying power, the list of solid balance sheet and fundamentals (7 results) can help surface companies that may better match a comfort level with financial resilience.
- If the priority is risk control and sleeping well at night, use the 8 resilient stocks with low risk scores to filter for businesses that align with a more defensive profile.
- Those hunting for lesser known opportunities with strong fundamentals can turn to the 9 high quality undiscovered gems to find candidates that are not yet widely followed but still pass key quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com