
Is Cipher Digital (CIFR) Undervalued After Extending Barber Lake And Lifting Contracted Revenue Above $9b?
Cipher Digital (CIFR) extended the Barber Lake data center lease in Texas to 20 years, increasing total contracted revenue to more than US$9b and securing an additional 10-year commitment from an AI lab.
Cipher Digital’s latest Barber Lake update arrived in a mixed price backdrop, with the share price up 1.62% over the past day but down 11.44% over 30 days and 27.70% over 90 days. The 1-year total shareholder return of 6.87% and very large 3-year total shareholder return indicate that long term holders have still seen strong gains even as short term momentum has faded.
Scan how Cipher Digital fits into the wider buildout of compute infrastructure by comparing it with hand picked 90 AI infrastructure stocks fueling the same AI and data center demand story.
Cipher Digital now sits between two clear narratives. One says a 20 year, US$9b contract stack points to durability. The other flags execution risk and recent share price weakness. Which side does the valuation lean toward next?
Most Popular Narrative: 51% Undervalued
The most followed narrative on Cipher Digital values the shares at $31.78 against a last close of $15.71, framing today's pullback as a discount to modeled cash flows built on AI hosting and Bitcoin-linked capacity.
Industry-wide demand for large-scale, flexible, and energy-rich data center sites, driven by accelerating institutional and mainstream adoption of digital assets and AI, aligns with Cipher's strategy to develop infrastructure that can quickly pivot between Bitcoin mining and high-performance computing (HPC). This creates upside potential for both revenue diversification and earnings stability.
See why 92 investors see Cipher Digital as 51% undervalued.
Result: Fair Value of $31.78 (UNDERVALUED)
Still, the narrative around Cipher Digital could crack if Bitcoin-exposed revenue hits a prolonged downswing or if high capex and ERCOT related delays strain returns.
Find out about the key risks to this Cipher Digital narrative.
Another View: Cipher Digital Through The Sales Lens
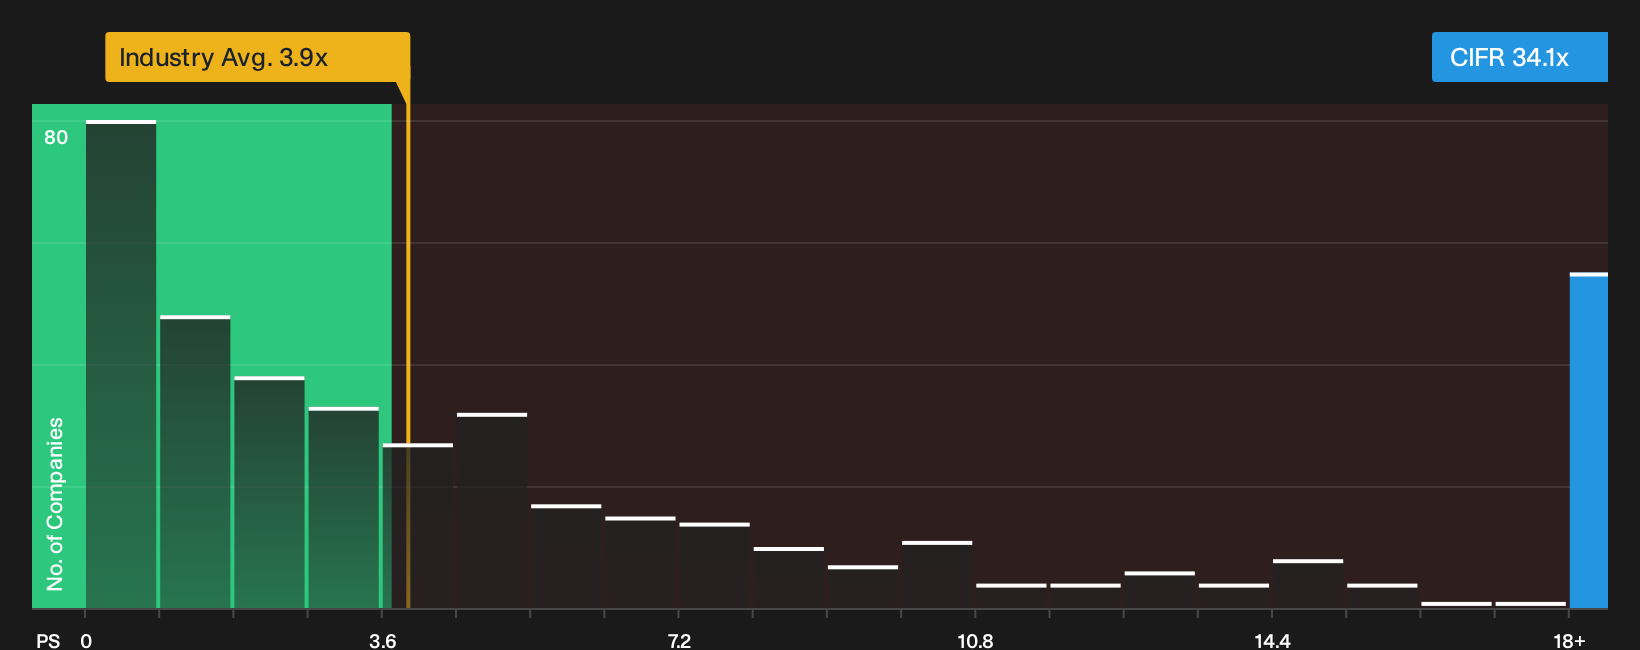
There is a very different message when Cipher Digital is viewed through its P/S ratio. The stock trades on 34.1x sales against 3.9x for the wider US Software group and 15.8x for peers, while the fair ratio sits at 3.4x. That gap suggests a lot of optimism is already in the price. The real question is whether you see that as upside already recognised or risk if expectations slip.
For a closer look at how this sales based view lines up with earnings power and cash flows over time, check the full valuation breakdown next, then test those inputs against your own expectations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Cipher Digital feels familiar, consider this a prompt to review the data independently, act promptly while sentiment remains divided, and then weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Cipher Digital?
You have already done the hard work on Cipher Digital. Do not stop here when a wider set of opportunities could sharpen your whole portfolio.
- Target potential mispricings by scanning a curated pool of stocks that combine quality fundamentals with attractive valuations using the 31 high quality undervalued stocks.
- Strengthen your foundation by focusing on businesses with robust finances through a carefully filtered list of solid balance sheet and fundamentals (25 results).
- Hunt for tomorrow's potential standouts before the crowd catches on by reviewing a focused list of 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com