
First Hawaiian (FHB) Sets October 23 Results As Pullback Puts Value Question Back In Focus
First Hawaiian (FHB) plans to release its third quarter 2026 financial results on October 23 before the market opens, with a webcast and conference call giving investors fresh detail on the regional bank's performance.
At a share price of US$25.26, First Hawaiian has seen its 90-day share price return fall 16.74%, even as the 1-year total shareholder return of 6.84% and 3-year total shareholder return of 60.32% point to momentum that has built over a longer horizon.
Scan how First Hawaiian compares with other regional financials by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Recent gains over one and three years suggest First Hawaiian has rewarded patient holders, while the 90 day pullback raises a fresh question. Is most of the upside already spent? Or does valuation still leave room ahead?
Price-to-Earnings of 10.8x: Is it justified?
On recent pricing, First Hawaiian trades on a P/E of 10.8x, which sits below both the broader US Banks industry and its direct peer group, even as the stock pulls back over the last 90 days.
The P/E ratio compares what investors pay for each dollar of earnings. For a regional bank like First Hawaiian it gives a quick read on how the market values its profit stream relative to other lenders that face similar funding, credit and regulatory conditions.
First Hawaiian is described as trading at good value on this metric, with its 10.8x P/E below the US Banks industry average of 11.6x and well under the peer average of 21.8x. This signals the market is attaching a lower earnings multiple than both its sector and closer comparables. Against an estimated fair P/E of 16.5x, that gap looks even wider and points to a level the multiple could move toward if sentiment and fundamentals stay aligned with that fair ratio work.
Explore the SWS fair ratio for First Hawaiian.
Result: Price-to-Earnings of 10.8x (UNDERVALUED)
Still, the 16.74% drop over 90 days, together with First Hawaiian’s role as a lender tied to broader credit conditions, could challenge any simple undervaluation story.
Find out about the key risks to this First Hawaiian narrative.
Another View On First Hawaiian’s Value
On one hand, First Hawaiian looks inexpensive on a 10.8x P/E. On the other, the SWS DCF model points to a fair value of about $46.42 a share, which is well above the current $25.26 price. If that cash flow work holds up, is the gap a margin of safety or a warning sign?
Look into how the SWS DCF model arrives at its fair value.
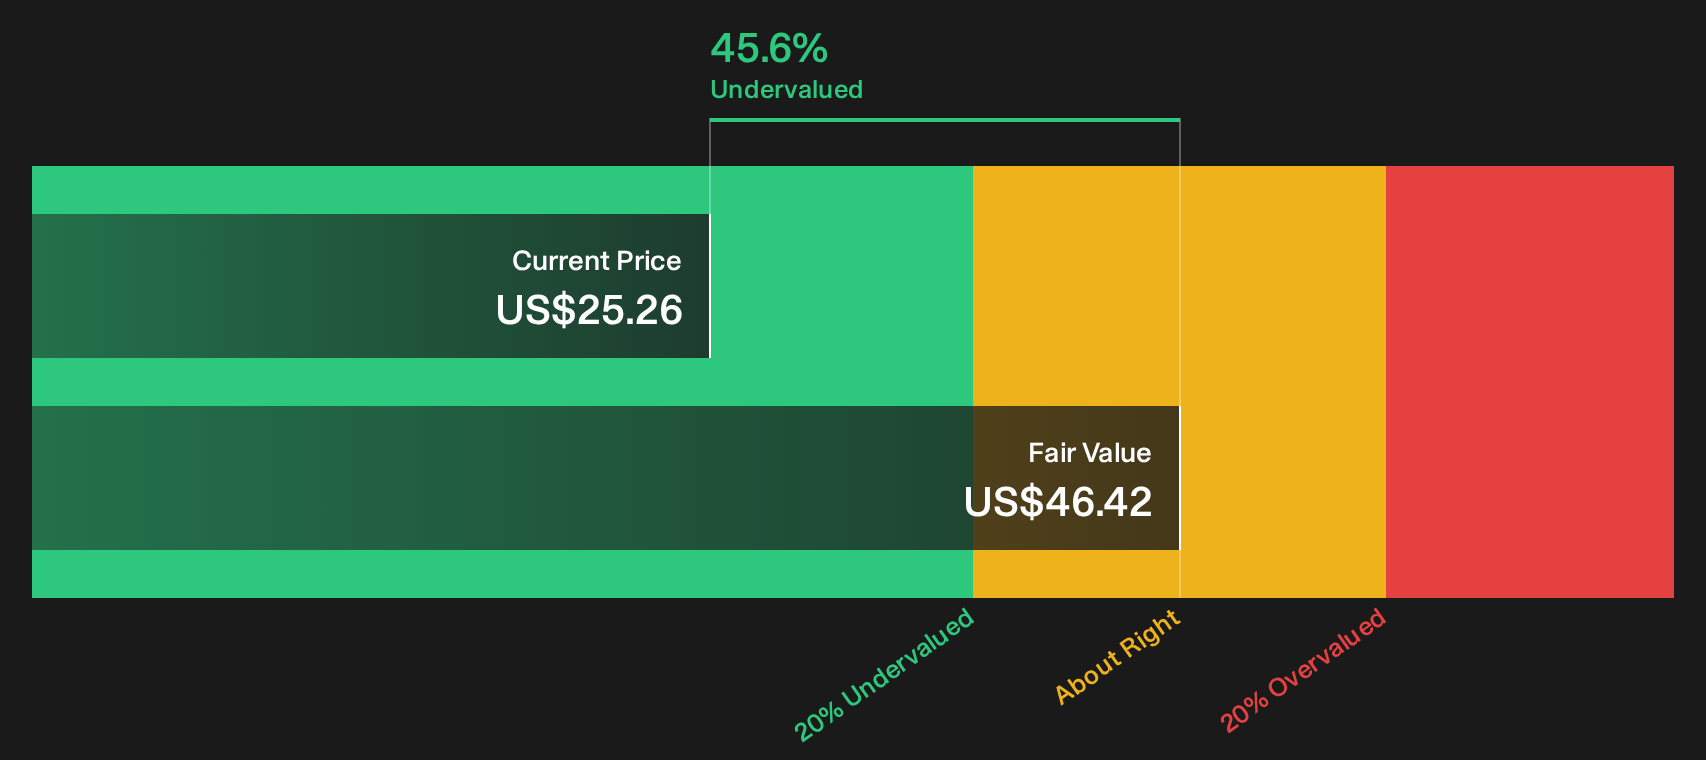
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Hawaiian for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on First Hawaiian mixed between recent weakness and longer term rewards, it helps to move quickly and review the numbers yourself. To see what the optimism is based on, start with the 4 key rewards.
Hunting for more ideas beyond First Hawaiian?
If First Hawaiian has you thinking about what else might fit your portfolio, do not stop here. Broaden your watchlist now and give yourself more options.
- Target resilient businesses that aim to smooth the ride in rough markets by scanning the 31 resilient stocks with low risk scores.
- Spot companies that combine quality fundamentals with appealing pricing by checking the 19 high quality undiscovered gems.
- Focus on potential income anchors for your portfolio by reviewing the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com