
United Bankshares (UBSI) Could Be 29% Below Fair Value After Its Recent Pullback
United Bankshares (UBSI) has drawn fresh attention after recent trading left the share price near $47.04. Investors are weighing that move against the bank’s multi-year total return record and current valuation metrics.
Momentum in United Bankshares has cooled slightly over the past month, with a 30 day share price return that declined 1.65%. This comes even as the year to date share price return of 22.53% and 3 year total shareholder return of 90.91% point to a stronger longer term story that investors are still digesting against today’s valuation.
Scan how United Bankshares stacks up against other banks and financials by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
For United Bankshares, a cooler 30 day stretch after a strong multi year run raises a simple tension: Is this price near $47 an entry to lean into, or a level to watch while waiting for a better pitch?
Preferred P/E of 12.4: Is it justified?
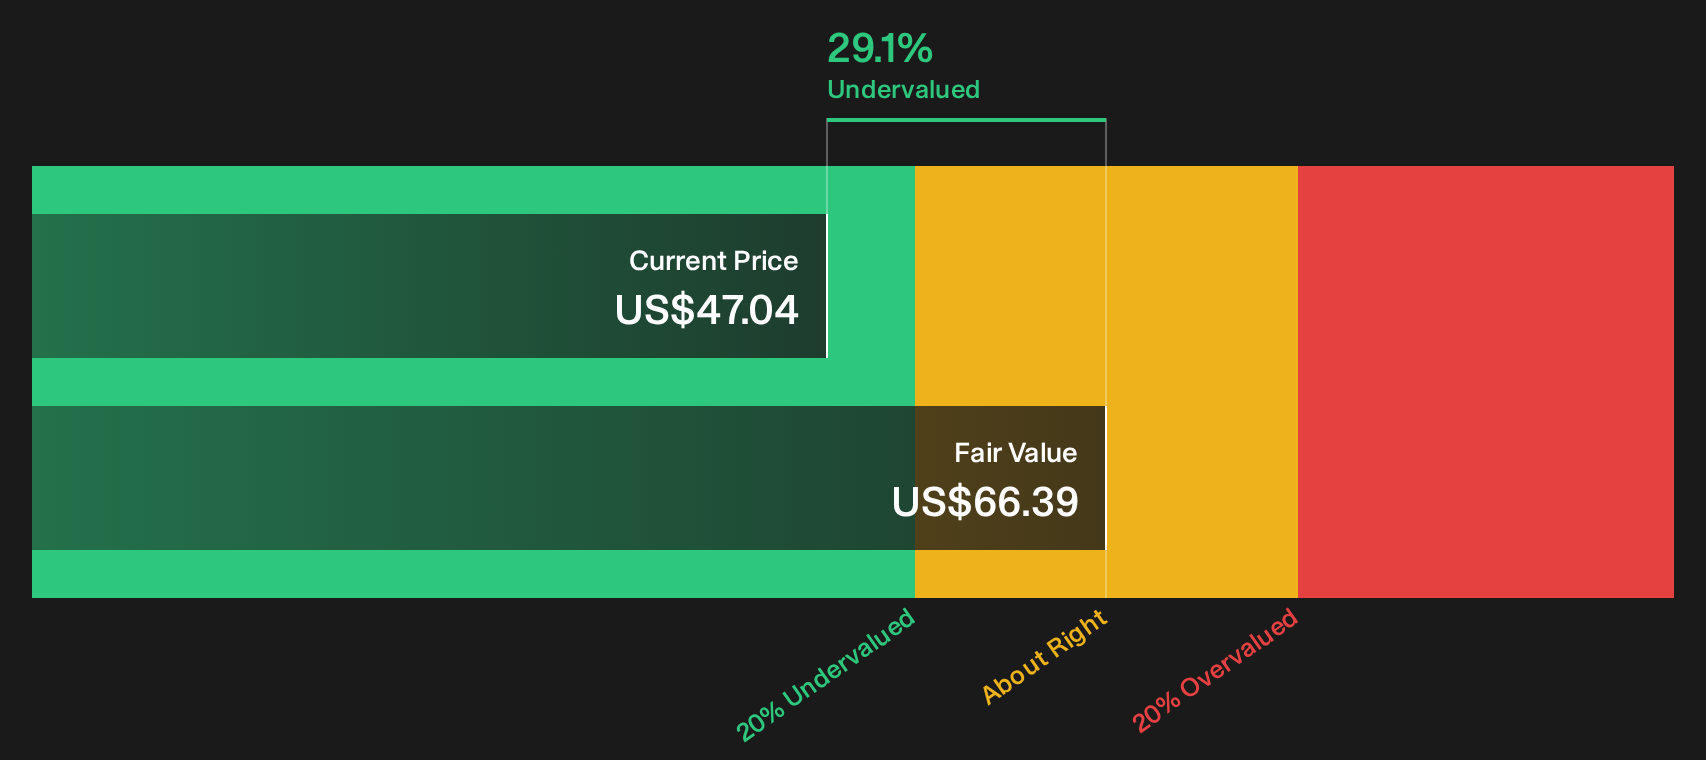
Valuation work on United Bankshares points to a mixed picture, with the stock trading at a P/E of 12.4 while still sitting about 29.1% below an internal fair value estimate based on future cash flows of $66.39 versus a last close of $47.04.
The P/E ratio compares the share price to earnings per share, so you are effectively being told how many dollars the market is willing to pay today for each dollar of profit. For a bank like United Bankshares, this matters because earnings power and balance sheet strength tend to be the main drivers of long term shareholder returns.
United Bankshares is described as expensive on a P/E of 12.4x compared with a fair P/E estimate of 10.8x. This suggests the current price embeds a richer earnings tag than that fair ratio implies. At the same time, the same dataset calls the stock good value versus peer P/Es of 13.7x, and more expensive than the broader US Banks industry on 11.6x. This shows the market is pricing in stronger characteristics than the typical bank but not giving it the highest premium in the group.
Result: Price-to-earnings of 12.4x (ABOUT RIGHT)
Explore the SWS fair ratio for United Bankshares.Still, the United Bankshares story can change quickly if credit quality weakens or if loan growth slows compared with its recent revenue and net income trends.
Find out about the key risks to this United Bankshares narrative.
Another view on United Bankshares valuation
The first check on United Bankshares focused on the P/E ratio. A different lens presents an additional perspective. The SWS DCF model calculates a fair value of $66.39 per share, compared with the current $47.04 price. This suggests investors might be assigning a lower value to the projected cash flows, or simply exercising caution.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed tone on United Bankshares has you curious rather than convinced, move fast and stress test the numbers yourself, then weigh the 3 key rewards
Looking for more United Bankshares investment ideas?
United Bankshares is only one option. If you want a fuller watchlist that matches your style, use the Simply Wall Street Screener before the next opportunity passes.
- Target quality at a discount by scanning the 31 high quality undervalued stocks that combine stronger fundamentals with prices that still look reasonable on the numbers.
- Lock in potential income streams by reviewing the 7 dividend fortresses that focus on higher yields with supporting financial strength.
- Raise the bar on risk control by filtering through the 31 resilient stocks with low risk scores built to highlight businesses with sturdier balance sheets and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com