
Is Archer-Daniels-Midland (ADM) Fully Priced On Its New Feed Amino Acid Venture?
Archer-Daniels-Midland stock reacts to new feed-grade amino acid joint venture
CJ CheilJedang and Archer-Daniels-Midland (ADM) have agreed to create a joint venture focused on fermentation-based feed-grade amino acids in the Americas, giving the partnership exclusive regional manufacturing and sales rights.
At a share price of US$80.45, Archer-Daniels-Midland has delivered a 36.24% year-to-date share price return. The 1-year total shareholder return of 35.65% and 5-year total shareholder return of 46.41% point to momentum that has been building rather than fading as the new joint venture and talks on expanding its presence in India reshape how investors view its growth potential and risk profile.
Scan 31 high quality undervalued stocks that, like Archer-Daniels-Midland, are using supply chain partnerships and sector tailwinds to support momentum in their share prices.
Archer-Daniels-Midland now has a bigger feed and nutrition footprint and a share price that reflects renewed confidence. The central question is straightforward: Does the current valuation still leave enough upside for new buyers?
Most Popular Narrative: 0% Overvalued
Archer-Daniels-Midland is trading almost exactly in line with the most followed fair value estimate of $80.10, so the joint venture story sits on top of a valuation that already incorporates moderate growth and margin gains.
Enterprise-wide productivity and cost simplification initiatives, including the 3 to 5 year program targeting US$500 million to US$750 million of cumulative savings and early progress such as a roughly 25% reduction in accounts payable cost per transaction, are aimed at structurally lowering Archer-Daniels-Midland’s cost base and supporting operating earnings and return on invested capital.
See why 99 investors see Archer-Daniels-Midland as 0% overvalued.
Result: Fair Value of $80.10 (ABOUT RIGHT)
Still, Archer-Daniels-Midland’s narrative can be knocked off course if liquid sweetener margins stay under pressure or if governance and litigation costs drag on sentiment.
Find out about the key risks to this Archer-Daniels-Midland narrative.
Another View: Archer-Daniels-Midland through a cash flow lens
While analyst targets cluster around a fair value of $80.10, the Simply Wall St DCF model presents a different picture. On that framework, Archer-Daniels-Midland at $80.45 sits well below an estimated future cash flow value of $122.01, which suggests a wide gap in how the market is pricing its long term cash generation.
Investors now have two very different anchors in front of them: one based on earnings multiples and one on discounted cash flows. The key question is which set of assumptions appears more realistic for the next several years.
Look into how the SWS DCF model arrives at its fair value.
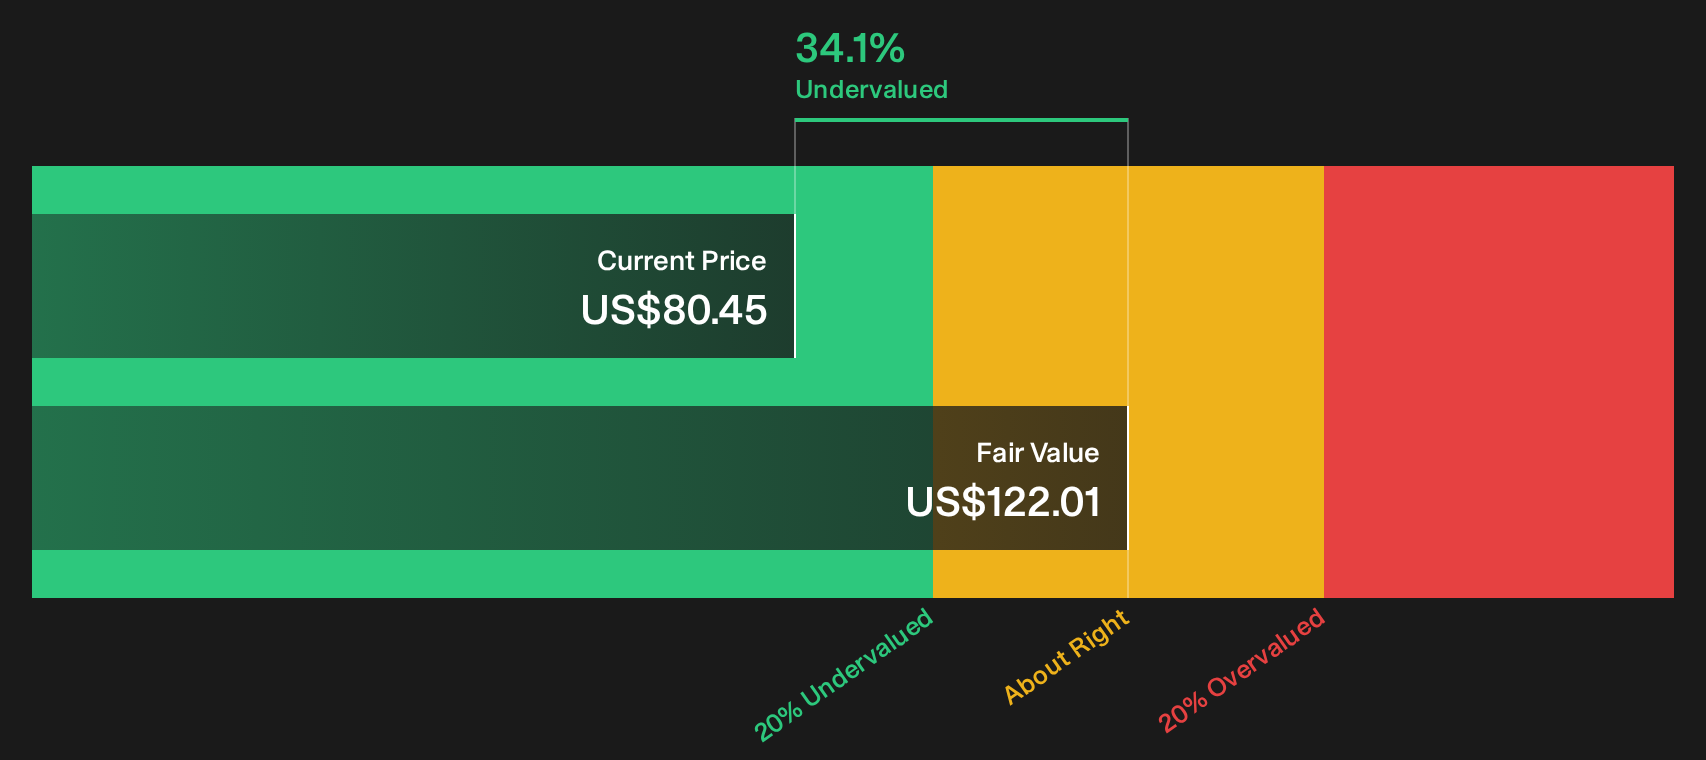
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Archer-Daniels-Midland for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the mixed message around Archer-Daniels-Midland’s valuation and cash flow story? Act while the data is fresh and test the optimism yourself with 3 key rewards.
Looking for more investment ideas beyond Archer-Daniels-Midland?
If Archer-Daniels-Midland has sharpened your focus on quality, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilient returns by scanning companies on the 31 resilient stocks with low risk scores that aim to pair steadier price action with more measured business profiles.
- Hunt for potential mispriced opportunities through the 31 high quality undervalued stocks that filters for solid fundamentals at prices that may not fully reflect them.
- Spot stronger balance sheets before the crowd by using the list of solid balance sheet and fundamentals (25 results) that highlights businesses with sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com