
Is Arthur J. Gallagher (AJG) Undervalued On Its Digital Margin Expansion Story?
Arthur J. Gallagher (AJG) has been under pressure recently, with the share price down over the past month and past 3 months. That pullback puts the insurance broker’s long run performance into sharper focus.
Over the past year, Arthur J. Gallagher has shifted from steady compounder to laggard, with the share price down 11.68% year to date and a 1-year total shareholder return falling 26.32%. However, the 5-year total return of 52.96% still reflects a much stronger long haul. This suggests that momentum has clearly faded recently as investors reassess growth prospects and risk around the current US$226.11 share price.
Scan how Arthur J. Gallagher’s recent pullback compares with peers by lining it up against 31 resilient stocks with low risk scores that have held up better through recent volatility.
After a long run that left Arthur J. Gallagher sitting on a 5 year total return of 52.96%, the recent slide has reset expectations. Is most of the upside already earned, or does the current valuation still leave room ahead?
Most Popular Narrative: 22% Undervalued
On the most followed view of Arthur J. Gallagher, a fair value of about $291 sits well above the recent $226.11 close. This puts the recent pullback against a valuation framework built on detailed growth, margin and discount rate assumptions.
Broader adoption of digital tools, enhanced data analytics and AI projects inside Arthur J. Gallagher’s operations is now backed by explicit targets for 5% production layer, 10 to 15% support layer and 20 to 30% back office cost savings over 3 to 5 years. If achieved, these would flow through to higher underlying EBITDAC margins and earnings.
See why 22 investors see Arthur J. Gallagher as 22% undervalued.
Result: Fair Value of $291.28 (UNDERVALUED)
Still, the bullish Arthur J. Gallagher narrative relies on property pricing not softening further and on acquisitions like AssuredPartners actually delivering the planned cost savings.
Find out about the key risks to this Arthur J. Gallagher narrative.
Another View: Arthur J. Gallagher Through Earnings Multiples
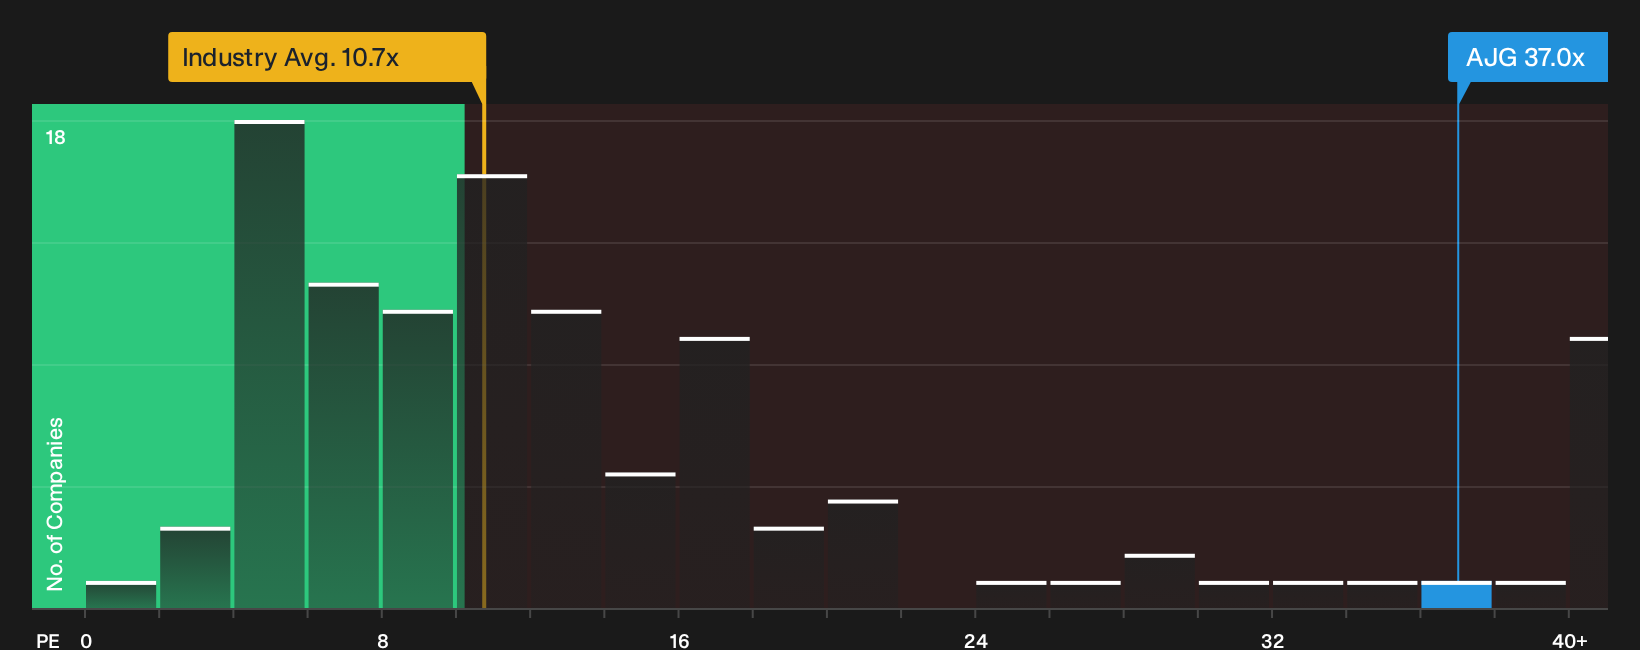
The narrative around Arthur J. Gallagher leans on a fair value of about $291, yet the current P/E of 37x tells a tougher story. That ratio is far above the US Insurance industry at 10.7x, peers at 17.2x, and a fair ratio of 14.8x, which flags meaningful valuation risk if sentiment cools.
Our earnings based view presents Arthur J. Gallagher as expensive relative to both sector and fair ratio anchors, even with the pullback. For anyone weighing that against the bullish fair value case, the key question is which yardstick will matter more when expectations reset: the cash flow model or the richer multiple being paid today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Arthur J. Gallagher story so far. Act quickly, review the full data set, and weigh 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Arthur J. Gallagher?
Do not stop with Arthur J. Gallagher. Use this pullback as a prompt to scan fresh opportunities and line up a watchlist you actually feel excited about.
- Target resilience by reviewing a curated 31 resilient stocks with low risk scores that have historically held up better when markets get choppy.
- Hunt for value by checking a focused 31 high quality undervalued stocks that pair stronger balance sheets with pricing that still looks reasonable.
- Prioritise income by scanning a hand picked 7 dividend fortresses that offer higher yields while backing them with sturdier financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com