
FactSet Research Systems (FDS) Tests Its Valuation After Earnings And New 2027 Outlook
Why FactSet Research Systems drew fresh attention
FactSet Research Systems (FDS) just packed several material updates into a single week, combining a new earnings report, fresh 2027 guidance, bylaw changes, a buyback update, and a board appointment.
Investors have reacted quickly to the latest bundle of updates from FactSet Research Systems, with the share price falling 11.91% over the past 30 days and slipping 6.63% year to date, while the 1-year total shareholder return is down 4.10% and the 3-year total shareholder return has declined 38.99%. This points to fading longer term momentum even after a 5.47% 90-day share price gain.
Compare how FactSet Research Systems stacks up against other financial data and analytics players by scanning a curated set of 19 high quality undiscovered gems that may be flying under most investors’ radar.
FactSet Research Systems now trades below both internal fair value estimates and the average analyst target after that earnings wobble. Is that discount compensation for real earnings risk, or is it an overreaction that misprices the core franchise?
Most Popular Narrative: 2.8% Overvalued
FactSet Research Systems closed at $266, only slightly above the $258.69 fair value implied by the most followed narrative, which frames the stock as just a touch rich rather than materially mispriced.
Josh Warren made one declarative statement this morning that has no equivalent in any prior period: “We believe that FY 2026 operating margins represented a floor.”
Margin compression was the most interrogated topic of the prior earnings period; adjusted operating margin fell roughly 300 basis points year-over-year, driven by performance-based compensation and structural investments. The earlier response was “clear line of sight to margin improvement.” Today’s response retroactively closes the investment cycle: the infrastructure work (multi-cloud migration, machine-ready data) is framed as “one-time” and non-repeating. These are not investments being repaid over a multi-year clock. They are investments being declared complete.
See why 1 investors see FactSet Research Systems as 3% overvalued.
Result: Fair Value of $258.69 (OVERVALUED)
Still, the FactSet Research Systems narrative could be tested if consumption based pricing further clouds revenue visibility or if key AI partnerships continue to fade from management’s updates.
Find out about the key risks to this FactSet Research Systems narrative.
Another View On FactSet Research Systems' Value
The narrative fair value of $258.69 presents FactSet Research Systems as slightly overvalued at $266. Yet our DCF model points in the opposite direction, with an estimate of $434.68 and a 38.8% gap that frames the shares as trading well below that future cash flow value. Which lens should carry more weight for you?
To see how this cash flow based view is built from the ground up, and what has to go right for it to hold, Look into how the SWS DCF model arrives at its fair value.
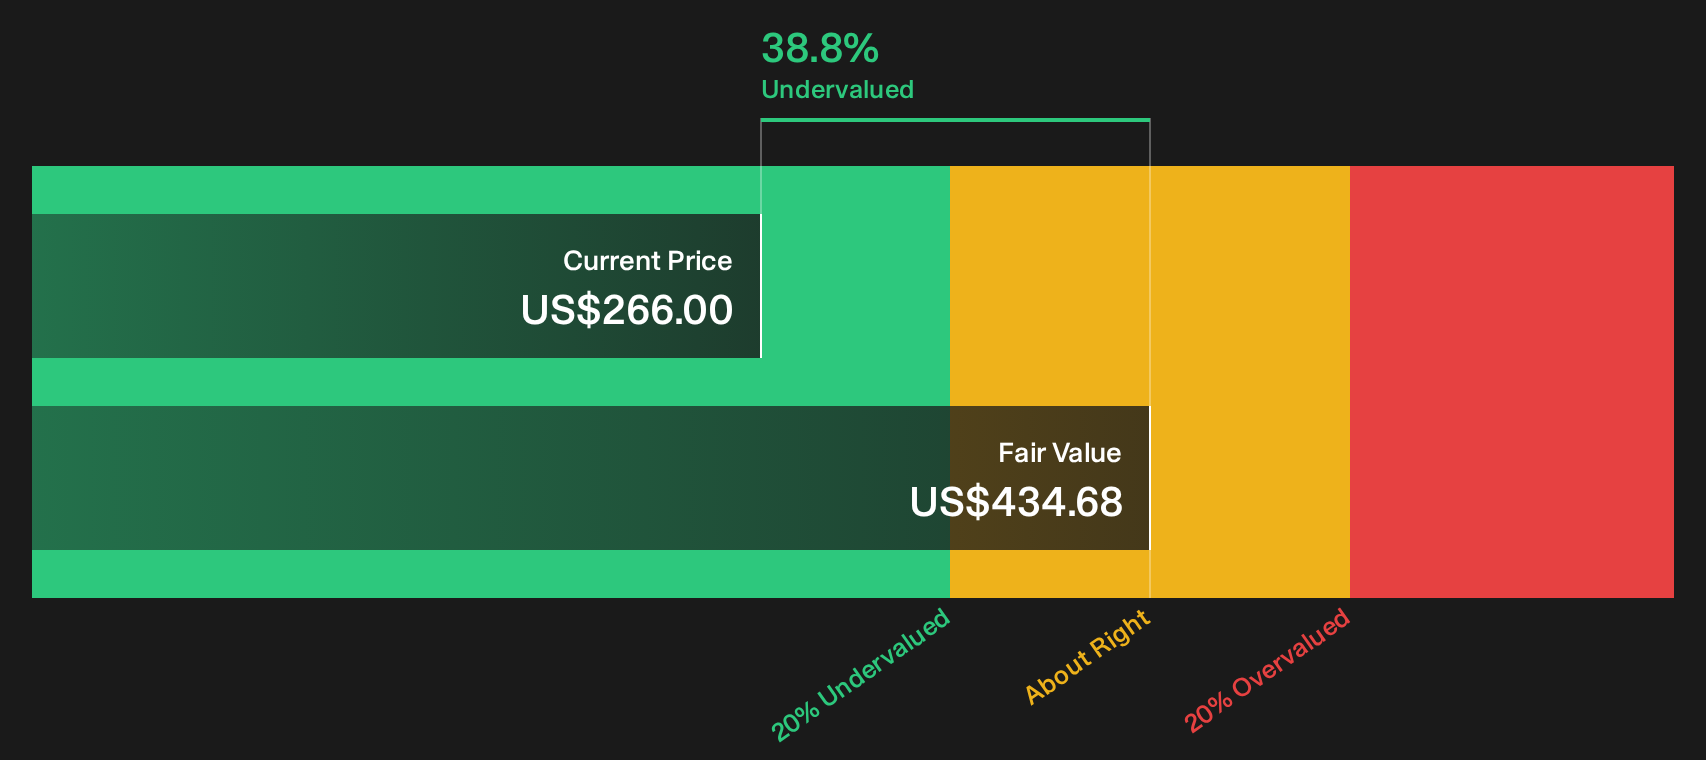
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FactSet Research Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this FactSet Research Systems story feels mixed, that is the point, with clear risks but also real upside arguments on the table. Act quickly, review the underlying numbers, and weigh both sides for yourself with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FactSet Research Systems?
If FactSet Research Systems has your attention, do not stop here. Broaden your watchlist, stress test your thesis, and keep fresh ideas flowing with targeted stock screens.
- Target resilient balance sheets by reviewing a curated list of solid balance sheet and fundamentals (25 results) that focuses on companies pairing cleaner finances with underlying business quality.
- Hunt for mispriced opportunities using the 31 high quality undervalued stocks that highlights stocks combining stronger fundamentals with currently compressed valuations.
- Prioritise stability and income potential through the 7 dividend fortresses that zeroes in on higher yielding payers with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com