
AAR (AIR) First Quarter Growth Puts Its Valuation Story Back In Focus
AAR (AIR) just posted first quarter results that showed year over year gains in both sales and profit, with revenue of US$918 million and net income of US$40.1 million catching investors’ attention.
AAR’s latest update lands after an active few months, with a fresh ESOP related shelf registration filed on October 1 and a long running buyback program now fully executed. Despite a 1 day share price return of 2.61% to US$102.51, shorter term momentum has faded, with the 7 day and 30 day share price returns down 11.71% and 18.99%. Longer term performance remains positive, with a 1 year total shareholder return of 25.32% and a 5 year total shareholder return of 203.91%, suggesting the broader story is still supportive even through the recent pullback.
Scan AAR alongside other aviation and industrial names with resilient balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (25 results).
Bulls see AAR’s pullback after strong quarterly numbers as a fresh entry point, while bears argue the valuation already bakes in the good news. Which side do the current multiples and cash flows lean toward next?
Most Popular Narrative: 34% Undervalued
AAR last closed at $102.51, while the most followed valuation storyline anchors fair value at $154.50. The gap that analysts see rests on how durable earnings and margins prove to be over time.
The commercialization of additional MRO capacity in Oklahoma City and Miami, both already sold out before opening, positions AAR to capitalize on the expected long-term rise in global air travel and the need for ongoing maintenance of aging aircraft fleets, supporting robust revenue growth and improved earnings visibility. AAR's strong growth in new parts Distribution (25%+ organic, significantly above market) directly aligns with increasing demand for resilient supply chains and more diversified inventory management from both commercial and government customers, indicating sustained future revenue expansion and potential for higher margins.
See why 11 investors see AAR as 34% undervalued.
Result: Fair Value of $154.50 (UNDERVALUED)
Still, if airline customers cut flying or original equipment makers keep expanding in the aftermarket, the bullish AAR valuation story could lose momentum.
Find out about the key risks to this AAR narrative.
Another View: Cash Flows Tell A Tougher Story For AAR
While analysts frame AAR as materially undervalued on their earnings based fair value of $154.50, the SWS DCF model points in the opposite direction. On that view, the current price of $102.51 sits above an estimated future cash flow value of $77.89, which implies the stock screens as overvalued on this method.
That gap between an earnings based upside case and a cash flow based downside reading leaves investors with a genuine judgment call. Which signal matters more for you: headline growth expectations or the harder math of discounted cash generation
Look into how the SWS DCF model arrives at its fair value.
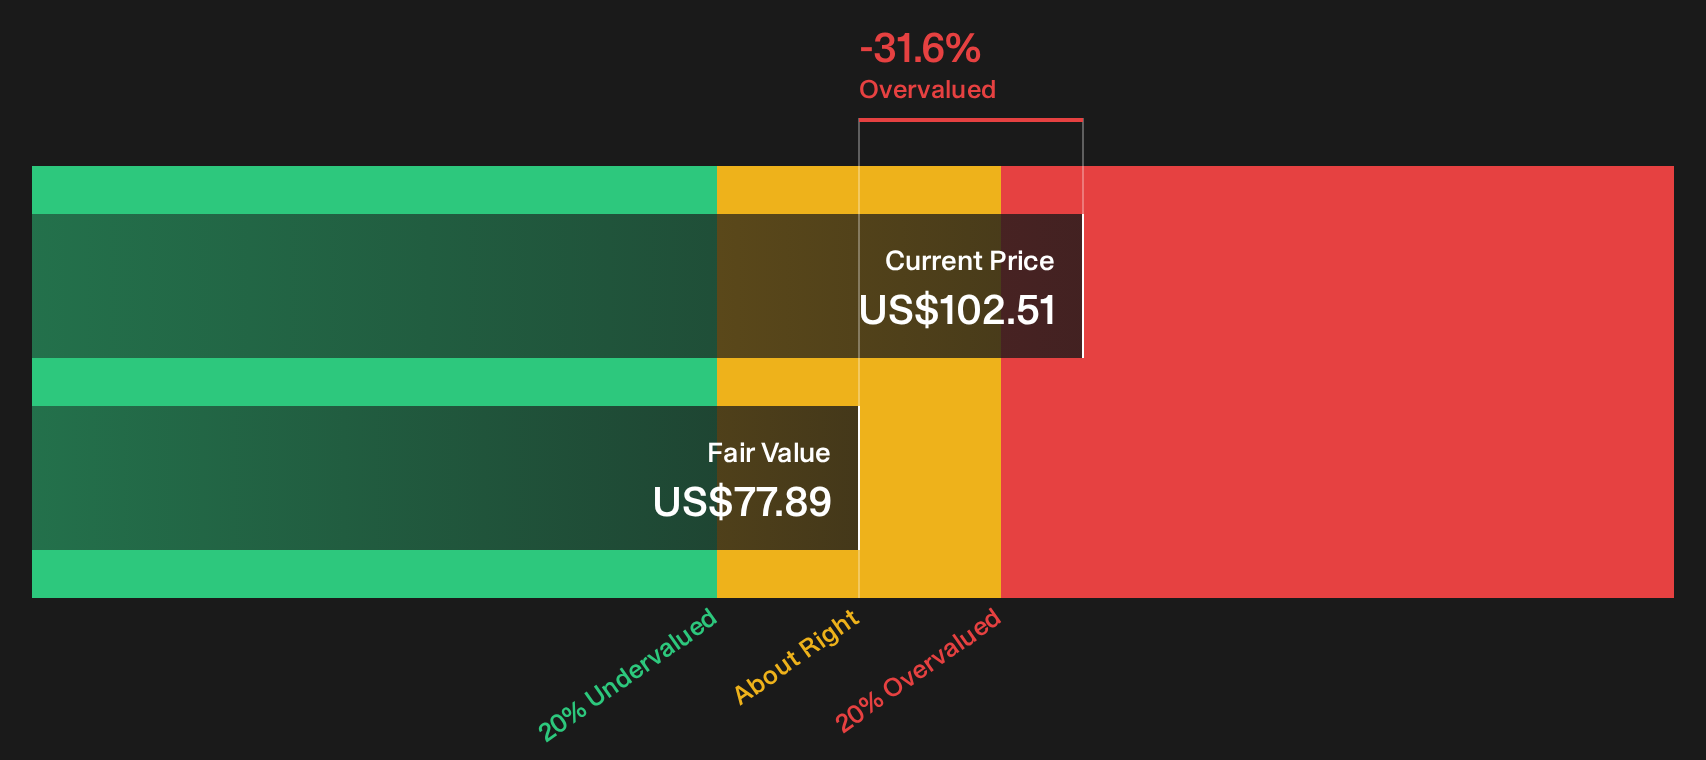
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AAR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn after the mixed signals around AAR and its valuation frameworks? Consider reviewing the full risk and reward profile carefully and weigh the 5 key rewards and 1 important warning sign.
Looking for more AAR investment ideas beyond this stock?
Do not stop with AAR alone. Use the Simply Wall Street Screener to surface fresh ideas that match your risk appetite, income goals, and value focus.
- Target potential value opportunities by reviewing companies highlighted in our 31 high quality undervalued stocks and see which stocks line up with your return expectations.
- Strengthen your income stream by scanning for reliable payers through the 7 dividend fortresses so you are not relying on capital gains alone.
- Dial back portfolio stress by focusing on financially resilient businesses using the 31 resilient stocks with low risk scores before capital moves somewhere else first.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com