
Is Denison Mines (TSX:DML) Undervalued Following Its ROTH Conference Spotlight?
Conference spotlight and recent share performance
Denison Mines (TSX:DML) stepped into the spotlight at the ROTH Critical Mass in Emerging Nuclear Technology Conference in New York on 1 October 2026, drawing attention to its Wheeler River uranium project.
The appearance comes after a period in which the stock declined 22% over the past month and 20% over the past 3 months, prompting some investors to reassess how current pricing reflects the company’s uranium focused asset base.
For context, Denison Mines is trading at CA$3.67 after a 30 day share price return of down 22.25% and a year to date share price return of down 11.35%. However, the three year total shareholder return of 68.35% and five year total shareholder return of 115.88% point to a much stronger longer term story. This suggests that recent weakness reflects a shift in near term sentiment or risk perception rather than the whole picture.
Spot fresh uranium infrastructure opportunities by scanning the hand picked 19 nuclear energy infrastructure stocks, which is aligned with the same nuclear energy theme as Denison Mines.After a drop of more than 20% in three months, Denison Mines now sits well below recent levels and below analyst targets. Is this the moment to step in, or does patience on the entry point still make more sense?
Preferred Price-to-Book of 11.5x for Denison Mines: Is it justified?
Valuation for Denison Mines currently hinges on a P/B figure of 11.5x against a share price of CA$3.67. The broader peer group trades on much lower levels and the stock also screens as deeply discounted on some intrinsic value models.
P/B compares the market value of a business to its net assets and is often used for asset heavy sectors like resources. In these sectors, investors may focus on how much they are paying for projects and balance sheet value rather than earnings alone.
An 11.5x multiple implies the market is pricing Denison Mines at more than eleven times its book value. This indicates that expectations around future uranium cash flows and the Wheeler River project are carrying a large premium to the accounting base.
The gap to the Canadian Oil and Gas industry is wide, as peers trade at an average P/B of 1.9x. This signals that Denison Mines is priced far more expensively on this metric than the sector benchmark.
Result: Price-to-book of 11.5x (OVERVALUED).
See what the numbers say about this price — find out in our valuation breakdown.
Still, Denison Mines faces clear pressure points if uranium sentiment cools further or if progress at Wheeler River lags behind current market expectations.
Find out about the key risks to this Denison Mines narrative.
Another view on Denison Mines valuation
Using a very different set of assumptions, the SWS DCF model points to a fair value of CA$13.50 per share for Denison Mines, compared with the current CA$3.67 price. That implies the stock trades at roughly a 73% discount. Is this a genuine gap or simply model optimism meeting market caution?
Look into how the SWS DCF model arrives at its fair value.
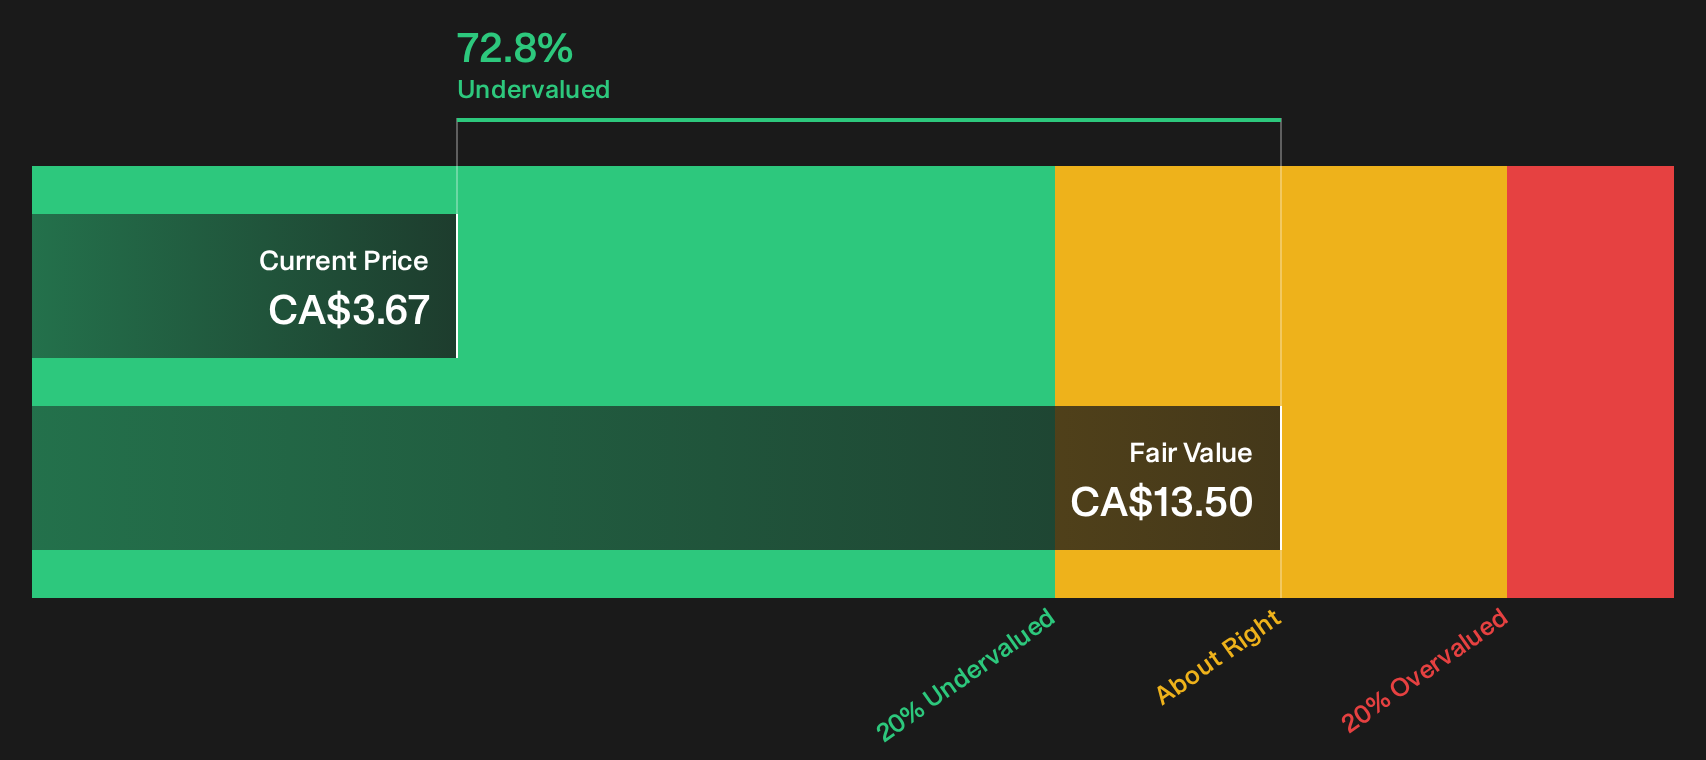
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Denison Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Denison Mines has clearly split opinions, with both clear risks and real upside arguments on the table. Act quickly, review the data for yourself, and pressure test both sides by weighing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Denison Mines?
If Denison Mines has your attention but you want a broader watchlist, use the Simply Wall St Screener to surface fresh, data driven opportunities quickly.
- Target potential mispricings by scanning the 6 high quality undervalued stocks that combine quality fundamentals with discounted market prices.
- Secure more predictable income streams by reviewing the 1 dividend fortresses that focus on higher yielding, established payouts.
- Sleep easier during volatility by checking the 8 resilient stocks with low risk scores that score well on balance sheet strength and risk factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com