
Asian Stocks That May Be Priced Below Intrinsic Estimates In October 2026
In October 2026, Asian markets are navigating a complex landscape shaped by fluctuating oil prices and elevated bond yields, mirroring broader global economic uncertainties. Amid these challenges, investors are increasingly focused on identifying stocks that may be trading below their intrinsic value, offering potential opportunities for those seeking to capitalize on market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shanghai Flyco Electrical Appliance (SHSE:603868) | CN¥31.09 | CN¥61.62 | 49.5% |
| Nissui (TSE:1332) | ¥1098.00 | ¥2180.59 | 49.6% |
| Kingnet Network (SZSE:002517) | CN¥16.01 | CN¥31.56 | 49.3% |
| Innodisk (TPEX:5289) | NT$1295.00 | NT$2530.08 | 48.8% |
| Ichikoh Industries (TSE:7244) | ¥540.00 | ¥1066.37 | 49.4% |
| Hainan Jinpan Smart Technology (SHSE:688676) | CN¥61.53 | CN¥121.78 | 49.5% |
| Foxconn Industrial Internet (SHSE:601138) | CN¥58.20 | CN¥113.22 | 48.6% |
| ENN Energy Holdings (SEHK:2688) | HK$48.62 | HK$96.82 | 49.8% |
| Double Medical Technology (SZSE:002901) | CN¥40.86 | CN¥79.59 | 48.7% |
| China Coal Energy (SEHK:1898) | HK$10.17 | HK$20.10 | 49.4% |
Let's take a closer look at a couple of our picks from the screened companies.
Fujian Funeng (SHSE:600483)
Overview: Fujian Funeng Co., Ltd., along with its subsidiaries, is involved in the production and sale of electricity and heat in China, with a market capitalization of approximately CN¥30.64 billion.
Operations: The company's revenue is primarily derived from the production and sale of electricity and heat within China.
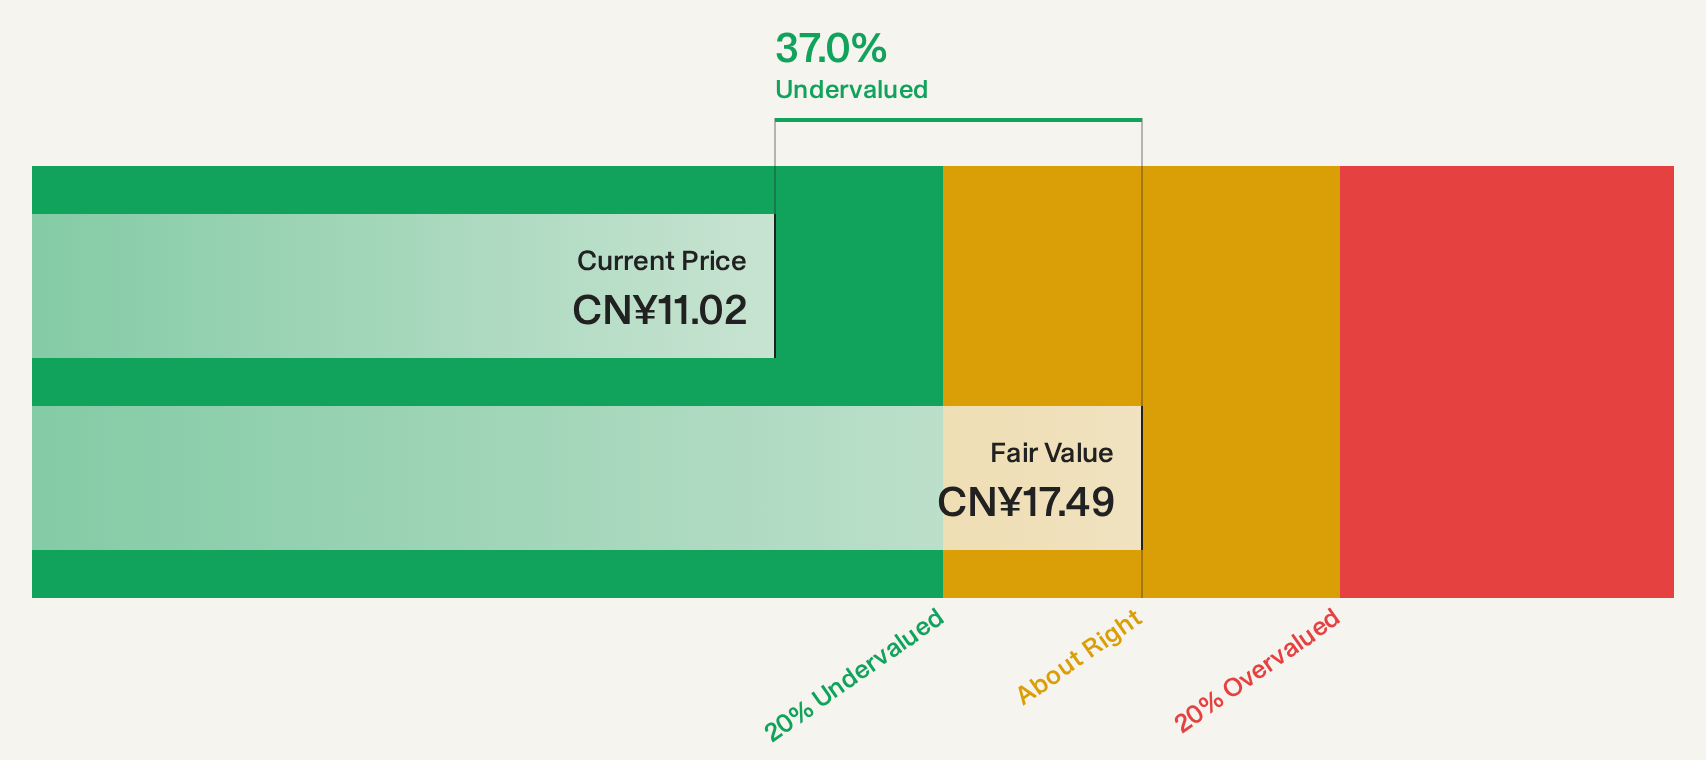
Estimated Discount To Fair Value: 37%
Fujian Funeng trades at CN¥11.02, significantly below its estimated future cash flow value of CN¥17.49, suggesting undervaluation based on cash flows. The stock is priced 37% below fair value and analysts expect a 25.2% price rise. Despite stable revenue growth of 14% annually, it lags behind the market's 17.1%. Recent earnings show stable sales but flat net income year-over-year with diluted EPS declining slightly from CN¥0.48 to CN¥0.42.
- Upon reviewing our latest growth report, Fujian Funeng's projected financial performance appears quite optimistic.
- Dive into the specifics of Fujian Funeng here with our thorough financial health report.
Tasly Pharmaceutical Group (SHSE:600535)
Overview: Tasly Pharmaceutical Group Co., Ltd operates in China focusing on the research, development, production, and sale of pharmaceuticals with a market capitalization of approximately CN¥20.92 billion.
Operations: Tasly Pharmaceutical Group Co., Ltd's revenue is derived from its core activities in the research, development, production, and sale of pharmaceuticals within China.
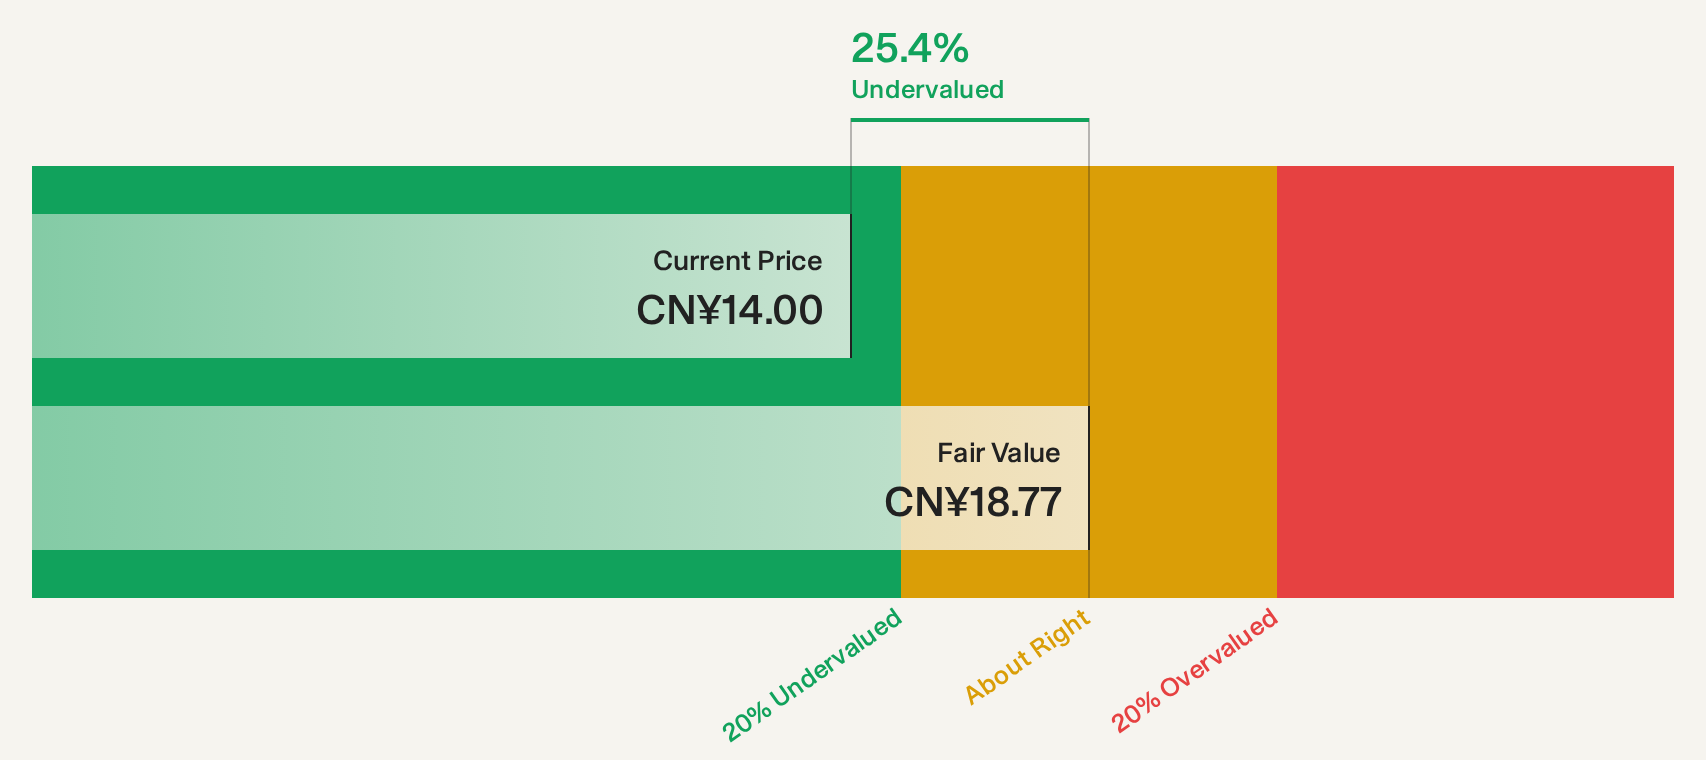
Estimated Discount To Fair Value: 25.4%
Tasly Pharmaceutical Group, trading at CN¥14, is undervalued based on cash flows with a future cash flow value of CN¥18.77. Analysts anticipate a 23.5% price increase, although revenue growth of 8.7% annually lags the market's 17.1%. Recent earnings show net income rose to CNY 892.68 million from CNY 774.7 million last year, despite sales dipping slightly to CNY 4.20 billion from CNY 4.29 billion in the same period.
- Our growth report here indicates Tasly Pharmaceutical Group may be poised for an improving outlook.
- Take a closer look at Tasly Pharmaceutical Group's balance sheet health here in our report.
Lepu Medical Technology (Beijing) (SZSE:300003)
Overview: Lepu Medical Technology (Beijing) Co., Ltd. focuses on the research, development, and manufacturing of cardiac interventional medical devices both in China and internationally, with a market cap of CN¥21.49 billion.
Operations: Lepu Medical Technology (Beijing) Co., Ltd. generates revenue primarily from its cardiac interventional medical devices, serving both domestic and international markets.
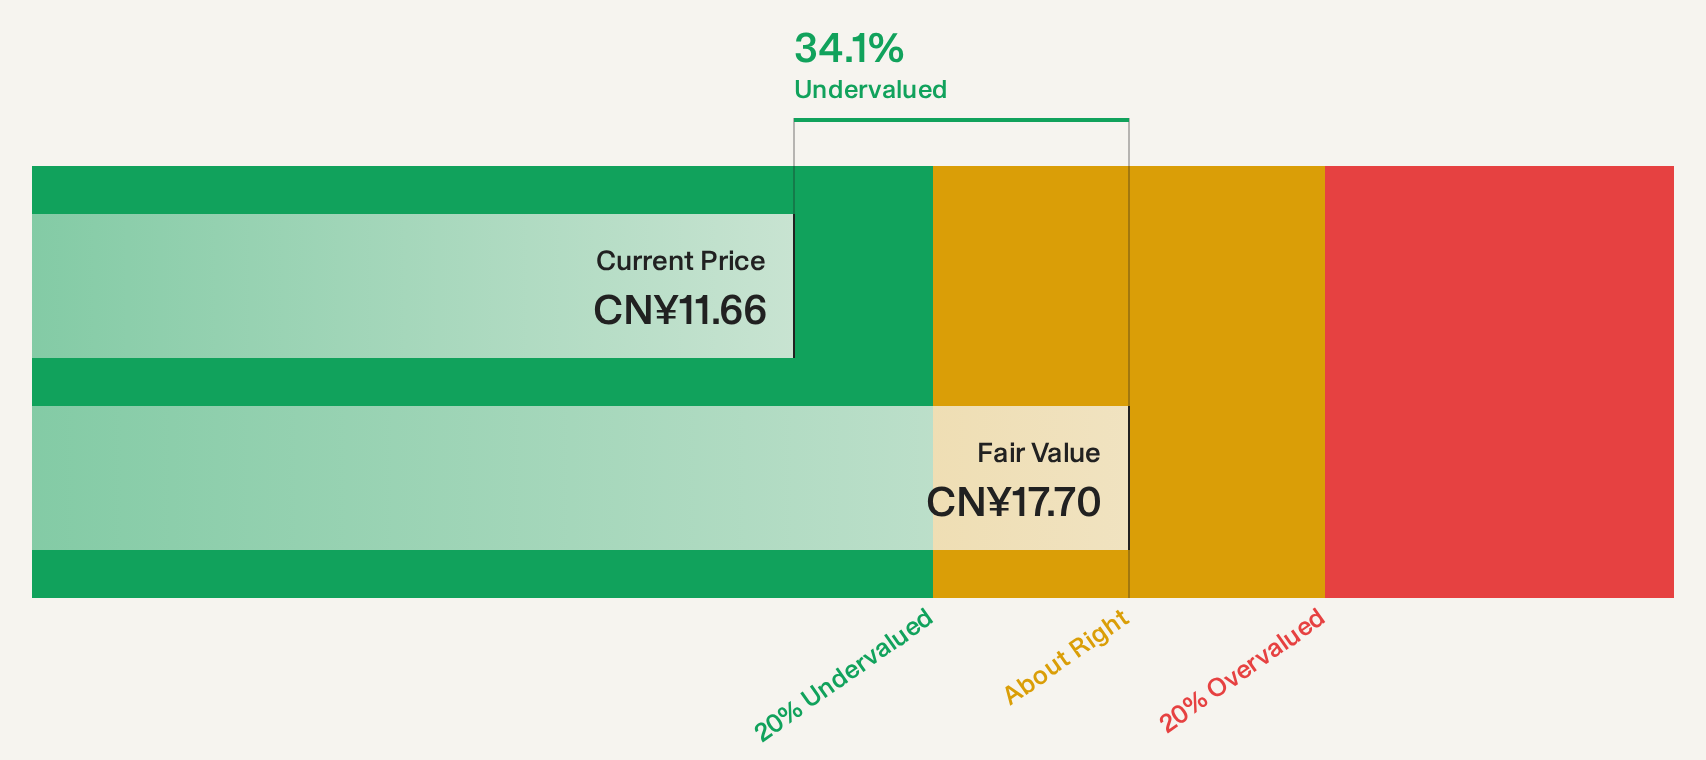
Estimated Discount To Fair Value: 34.1%
Lepu Medical Technology (Beijing), trading at CN¥11.66, is undervalued with a future cash flow value of CN¥17.7, more than 20% below its estimated worth. Despite a decline in net income to CNY 499.48 million from CNY 690.93 million last year, earnings are projected to grow significantly at over 20% annually for the next three years, though revenue growth remains slower than the market average at 10.6%.
- Our earnings growth report unveils the potential for significant increases in Lepu Medical Technology (Beijing)'s future results.
- Navigate through the intricacies of Lepu Medical Technology (Beijing) with our comprehensive financial health report here.
Taking Advantage
- Embark on your investment journey to our 166 Undervalued Asian Stocks Based On Cash Flows selection here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com