
3 Asian Growth Stocks With High Insider Ownership And Earnings Growth Over 24%
As the Asian markets continue to navigate through global economic challenges, including fluctuating oil prices and shifts in monetary policies, investors are increasingly focusing on growth opportunities within the region. In this context, companies with high insider ownership and robust earnings growth stand out as potentially attractive investments for those looking to capitalize on the resilience and potential of Asia's dynamic economies.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| HUMAN MADE (TSE:456A) | 29.1% | 29.5% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's dive into some prime choices out of the screener.
Smoore International Holdings (SEHK:6969)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Smoore International Holdings Limited is an investment holding company that provides vaping technology solutions, with a market cap of HK$57.25 billion.
Operations: The company's revenue is primarily derived from the sale of APV and vaping devices and components, totaling CN¥15.45 billion.
Insider Ownership: 39.6%
Earnings Growth Forecast: 28.8% p.a.
Smoore International Holdings demonstrates strong growth potential with earnings forecasted to grow significantly at 28.8% annually, outpacing the Hong Kong market. Despite trading well below estimated fair value, its return on equity is expected to remain low at 10.1%. Recent financial results showed increased sales of CNY 7.21 billion and net income of CNY 571.92 million for the first half of 2026, reflecting robust performance despite concerns over dividend sustainability and lack of recent insider trading activity.
- Unlock comprehensive insights into our analysis of Smoore International Holdings stock in this growth report.
- Our valuation report here indicates Smoore International Holdings may be overvalued.
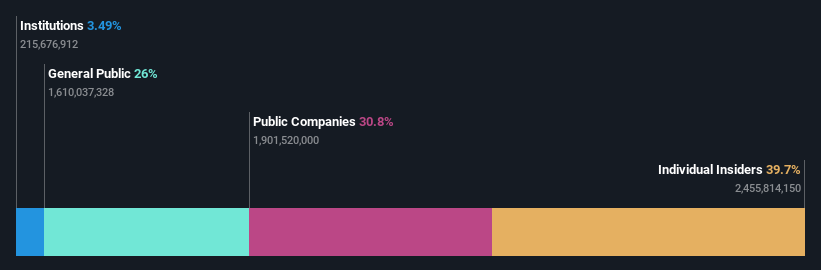
UMS Integration (SGX:558)
Simply Wall St Growth Rating: ★★★★★☆
Overview: UMS Integration Limited is an investment holding company that offers equipment manufacturing and engineering services to semiconductor original equipment manufacturers across several countries, including Singapore, Malaysia, Taiwan, the United States, South Korea, and China; it has a market cap of SGD2.57 billion.
Operations: The company's revenue primarily comes from its Semiconductor segment, contributing SGD241.77 million, followed by the Aerospace segment at SGD28.89 million.
Insider Ownership: 14.2%
Earnings Growth Forecast: 24.7% p.a.
UMS Integration shows promising growth prospects with earnings expected to grow significantly at 24.68% annually, surpassing the Singapore market. Recent financials reveal a strong performance with second-quarter sales of S$87.14 million and net income of S$19.4 million, year-over-year increases driven by robust revenue growth forecasts at 21%. Despite no recent insider trading activity, the company is expanding its footprint in Asia through a new subsidiary in Vietnam, enhancing its strategic positioning.
- Get an in-depth perspective on UMS Integration's performance by reading our analyst estimates report here.
- Our valuation report unveils the possibility UMS Integration's shares may be trading at a premium.

Northsand (TSE:446A)
Simply Wall St Growth Rating: ★★★★★★
Overview: Northsand, Inc. offers IT and business consulting services both in Japan and internationally, with a market cap of ¥177.47 billion.
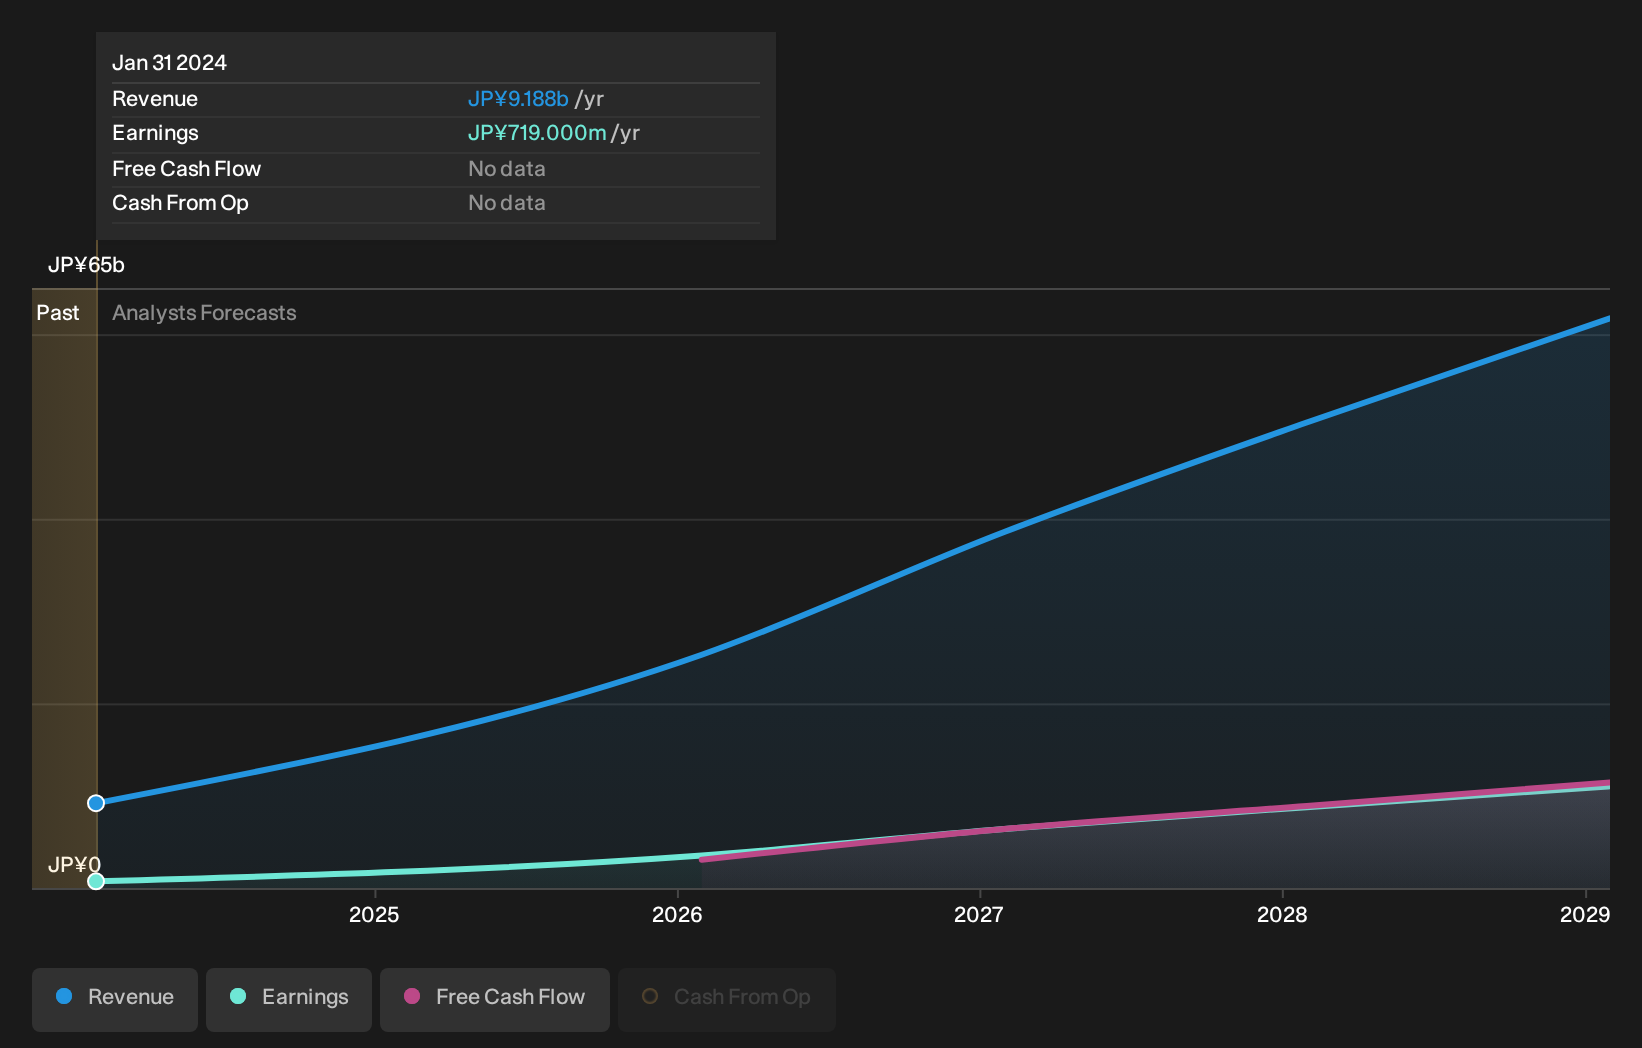
Operations: The company generates revenue primarily from its Software & Programming segment, amounting to ¥9.19 billion.
Insider Ownership: 21.1%
Earnings Growth Forecast: 34.5% p.a.
Northsand is poised for substantial growth, with earnings forecasted to rise significantly at 34.5% annually, outpacing the Japanese market. Revenue growth is also expected to be robust at 29.3% per year. Despite recent share price volatility and no significant insider trading activity, Northsand has revised its financial forecasts upward due to strong consultant recruitment and increased billing rates, projecting net sales of ¥40.56 billion and a profit of ¥6.82 billion for the fiscal year ending January 2027.
- Delve into the full analysis future growth report here for a deeper understanding of Northsand.
- Our comprehensive valuation report raises the possibility that Northsand is priced higher than what may be justified by its financials.
Make It Happen
- Access the full spectrum of 497 Fast Growing Asian Companies With High Insider Ownership by clicking on this link.
- Want To Explore Some Alternatives? We've found 8 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com