
First Industrial Realty Trust (FR) Could Be 18% Undervalued On Argus Downgrade
Argus downgrade puts fresh spotlight on First Industrial Realty Trust
Argus cut its rating on First Industrial Realty Trust (FR) to HOLD, a move that refocused attention on the industrial REIT's positioning, trading activity, and current investor expectations around its US logistics portfolio.
The Argus downgrade landed after a patch of softer momentum, with the 30-day share price return down 3.86% and the 90-day share price return down 5.68%. Even so, First Industrial Realty Trust still shows an 18.82% 1-year total shareholder return that points to longer term holders having fared much better than recent traders.
Stress test your view on First Industrial Realty Trust by comparing it with our handpicked list of solid balance sheet and fundamentals (25 results) that have held up under different analyst calls.
First Industrial Realty Trust now carries a HOLD call from Argus, a softer three month price trend, and a last close of $59.46. Does that mix still leave enough upside to justify the current risk?
Most Popular Narrative: 18% Undervalued
Against Argus' HOLD call and a last close of $59.46, the most followed narrative on First Industrial Realty Trust argues for a fair value of $72.25, implying a meaningful valuation gap even after a solid 1-year total return.
The speculative development program that has generated about US$1.3b of value over the past decade at roughly 7% cash yields is being extended through new projects in markets like Philadelphia, Miami and Arlington underwritten at similar yields, which points to additional future contributions to earnings and net asset value as these assets lease.
Tightening land and entitlement conditions in infill regions such as Southern California, Baltimore Washington, Nashville and South Florida, where industrial projects are increasingly hard to permit, limit competing supply and can support pricing power for First Industrial Realty Trust in those markets, which feeds through to rent growth and same store NOI.
See why 10 investors see First Industrial Realty Trust as 18% undervalued.
Result: Fair Value of $72.25 (UNDERVALUED)
Still, the First Industrial Realty Trust narrative hinges on occupancy lifting toward guidance and on activism related costs not eroding margins if they remain elevated.
Find out about the key risks to this First Industrial Realty Trust narrative.
Another View: What Multiples Say About First Industrial Realty Trust
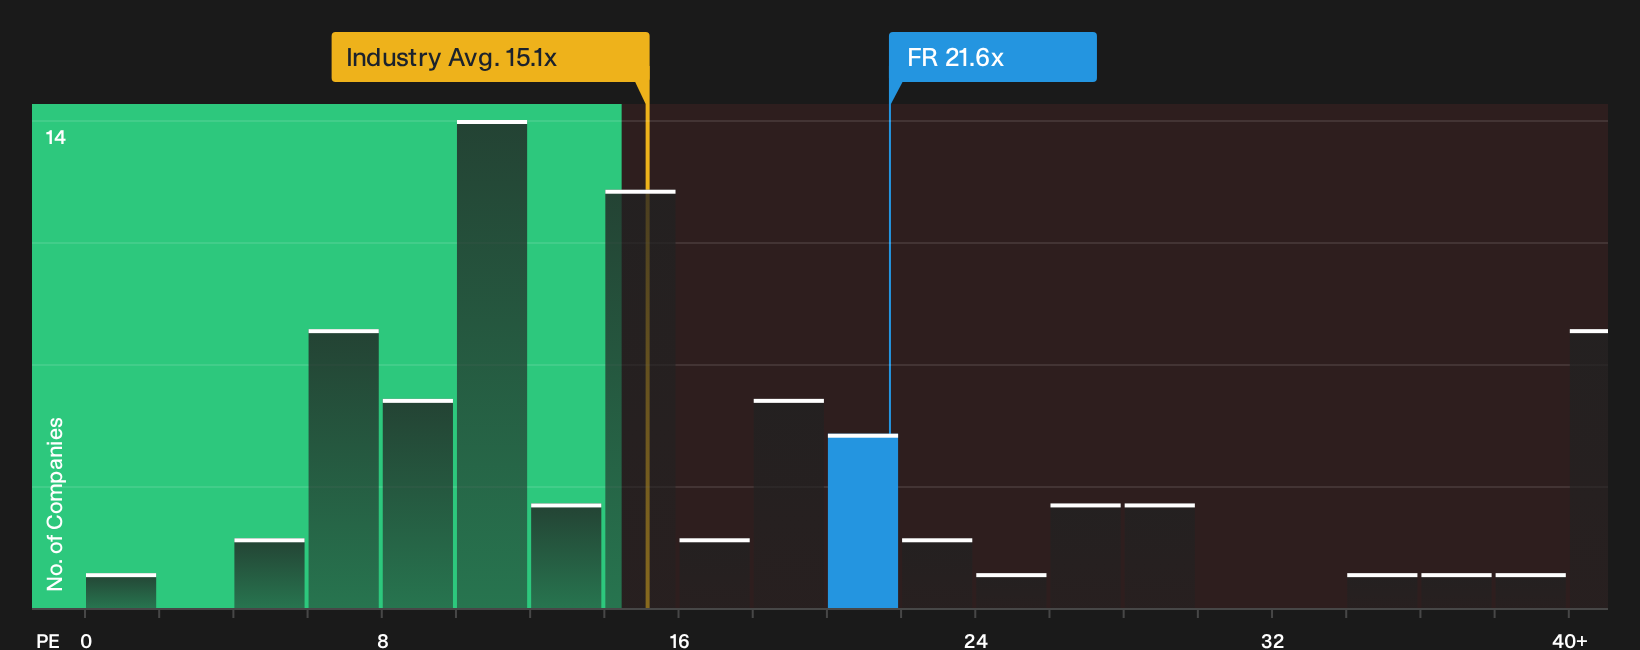
The SWS DCF model points to First Industrial Realty Trust trading at a discount, yet the simple P/E check tells a different story. FR changes hands at 21.6x earnings versus 15.1x for the global Industrial REITs group, while the fair ratio sits higher at 27.5x. That mix hints at both valuation support and the risk that peers or the fair ratio, not the current market level, end up being the anchor. Which reference point do you trust most when analyst targets and Argus now pull in different directions?
To pressure test that second view further, it is worth walking through how the earnings multiple stacks up against both industry averages and the fair ratio in more detail. From there, it becomes a question of whether that spread feels like a margin of safety or a premium you are comfortable paying relative to alternatives in the same sector. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around First Industrial Realty Trust can be confusing. Consider reviewing the data for yourself and weighing both sides of the story by checking the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond First Industrial Realty Trust?
If the First Industrial Realty Trust story has you thinking harder about where to put fresh capital, you can use this moment to broaden your opportunity set with a few targeted screens.
- Target potential mispricings by scanning for quality businesses trading below what their fundamentals suggest through our 31 high quality undervalued stocks.
- Focus on resilience first by filtering for companies with stronger finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities by zeroing in on financially healthy smaller stocks with our 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com