
Learn Why The Bull Case For H M Could Change Following Q3 Earnings And Guidance
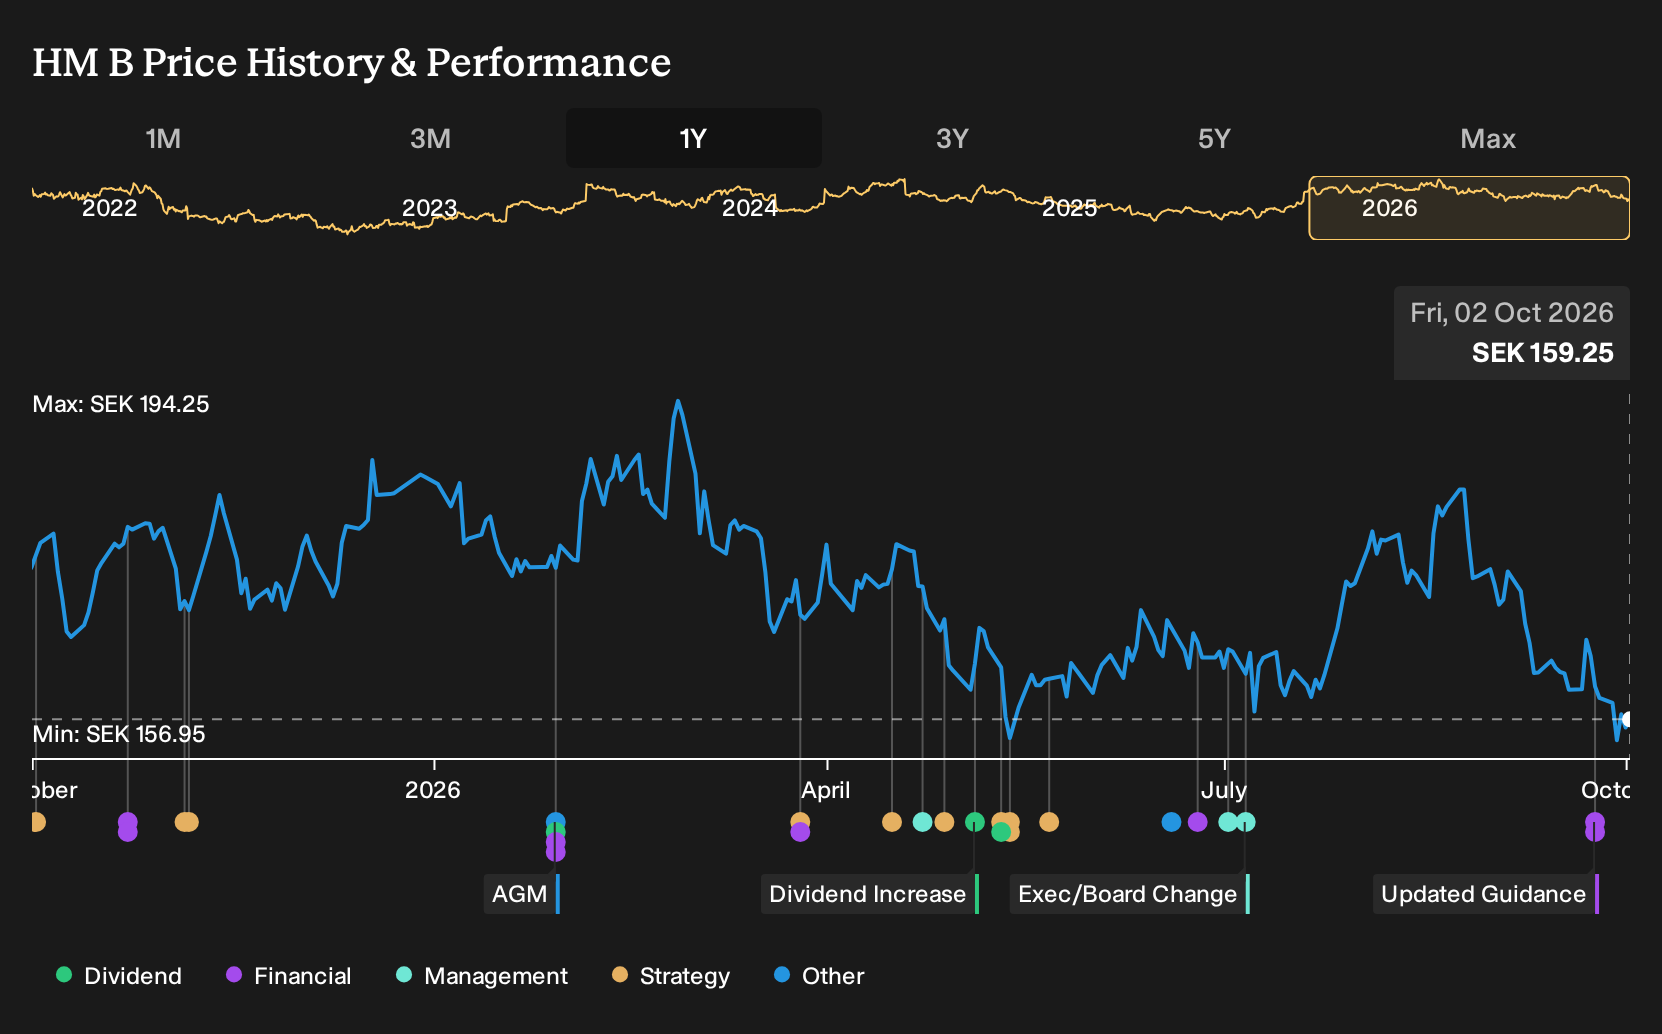
- H & M Hennes & Mauritz reported third quarter 2026 sales of SEK 57,189 million and net income of SEK 4,123 million, and guided to 1% year on year sales growth for September after the results were released on 24 September 2026.
- Profitability metrics moved ahead of top line progress, with basic earnings per share from continuing operations reaching SEK 2.58 for the quarter and SEK 5.53 for the first nine months of 2026 despite lower nine month sales than a year earlier.
- We will now assess how H & M Hennes & Mauritz's higher earnings per share shape the investment narrative built around margin improvement.
Compare H & M Hennes & Mauritz's margin driven earnings story with other retailers by scanning our hand picked 192 high quality undervalued stocks, which combine resilient cash flows with balance sheet strength.
H & M Hennes & Mauritz Investment Narrative Recap
To stay a shareholder in H & M Hennes & Mauritz, you need to be comfortable with a story built on margin repair more than strong top line momentum. The latest quarter showed higher earnings per share alongside broadly flat quarterly sales and softer nine month revenue, so the near term thesis leans on pricing, mix and cost discipline rather than volume.
The key short term catalyst is whether that margin work can hold while the company targets only 1% September sales growth, particularly in weaker regions and with store closures still in the background. The main risk right now is that higher inventory and purchasing costs or heavier markdowns start to erode those improved profit margins.
The most relevant update for that debate is the third quarter and nine month 2026 earnings report. H & M Hennes & Mauritz posted SEK 57,189 million of sales in the quarter and SEK 4,123 million of net income, with earnings per share from continuing operations at SEK 2.58. Across the first nine months, earnings per share reached SEK 5.53 even though revenue was lower than the prior year.
That pattern puts execution squarely in focus. Investors are watching whether management can keep lifting profitability through store portfolio optimisation, pricing and sourcing initiatives while coping with weaker key markets, higher costs and ongoing store closures. If those pressures start to bite harder, the margin led earnings story that underpins the current H & M Hennes & Mauritz narrative becomes harder to sustain.
H & M Hennes & Mauritz's current earnings are SEK 12.3b, with analysts expecting profits to reach SEK 14.9b and revenues SEK 237.8b by 2029. This implies 2.5% yearly revenue growth and an earnings increase of SEK 2.6b from today.
Uncover why H & M Hennes & Mauritz's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate lens focuses less on margins and more on the risk that H & M Hennes & Mauritz faces from fast rising digital competitors. The most cautious analysts were sketching in fairly flat revenue at about SEK 227.0b and earnings nearer SEK 11.1b by 2029, before this latest 1% September sales guidance and earnings update. Those expectations reflect a far more pessimistic storyline than consensus, so use them as a prompt to stress test your own view of how this new information might reshape future forecasts.
Explore 3 other H & M Hennes & Mauritz fair value estimates, including one that suggests it could be worth just SEK154.54.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H & M Hennes & Mauritz research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H & M Hennes & Mauritz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H & M Hennes & Mauritz's overall financial health at a glance.
Looking for more investment ideas beyond H & M Hennes & Mauritz?
If the margin story at H & M Hennes & Mauritz has you thinking about portfolio balance, it can help to line it up against other shares that offer different mixes of value, income and resilience using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your returns, consider stocks with robust payouts by scanning our curated 168 dividend fortresses that have been filtered for higher yields.
- If capital preservation is top of mind, focus on stability first and growth second by reviewing a 227 resilient stocks with low risk scores that have been assessed with lower risk scores.
- If you would rather search for overlooked opportunities, start with a 615 high quality undiscovered gems that combine quality fundamentals with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com