
3 British Penny Stocks For October 2026
With UK bond markets grappling with higher long term yields and investors questioning traditional safe havens, attention has shifted toward smaller, financially healthier companies that do not rely heavily on borrowing. That is where carefully screened low priced UK shares with stronger balance sheets come in. This article highlights three of the more robust options from this group to help you focus your penny stock research.
The three stocks featured next are just a small sample of what fits this theme. The full screen surfaces around 250 more financially solid penny companies with equally compelling stories that are not covered here. If you want to go straight to the source and identify your own candidates, head into the Financially Fit Penny Stocks screener to filter, analyze, and focus on the highest conviction ideas for your watchlist.
Luceco (LSE:LUCE)
Overview: Luceco is a UK based electrification specialist supplying wiring accessories, LED lighting and portable power products, including EV chargers, to households and commercial customers worldwide.
Operations: Luceco generates most of its £288 million revenue from Wiring Accessories (£135 million), with LED Lighting (£81 million) and Portable Power (£72 million), and primarily serves UK customers (£226 million).
Market Cap: £312 million
Luceco fits this Financially Fit Penny Stocks theme because it links everyday electrical hardware with EV charging and portable power. This provides direct exposure to electrification through a business that already sells into homes, trade counters and commercial projects.
"New product launches, particularly in the EV charger segment including commercial AC chargers and the forthcoming Home Energy Management System, are expected to drive revenue growth by tapping into expanding markets for residential and commercial EV solutions, as well as integrated energy management."
The key issue from here is how shifting cost pressures feed through to those electrification driven margins investors are watching.
Those cost pressures are only half the story, and the full narrative for Luceco sets out how Luceco’s pricing power, product mix and capital choices could reshape the risk reward balance.

Hollywood Bowl Group (LSE:BOWL)
Overview: Hollywood Bowl Group runs ten pin bowling, mini golf and family entertainment centers in the UK and Canada, generating recurring leisure cash flows.
Operations: Hollywood Bowl Group generates about £263 million from recreational activities, with roughly £223 million from the UK and £40 million from Canada.
Market Cap: £414 million
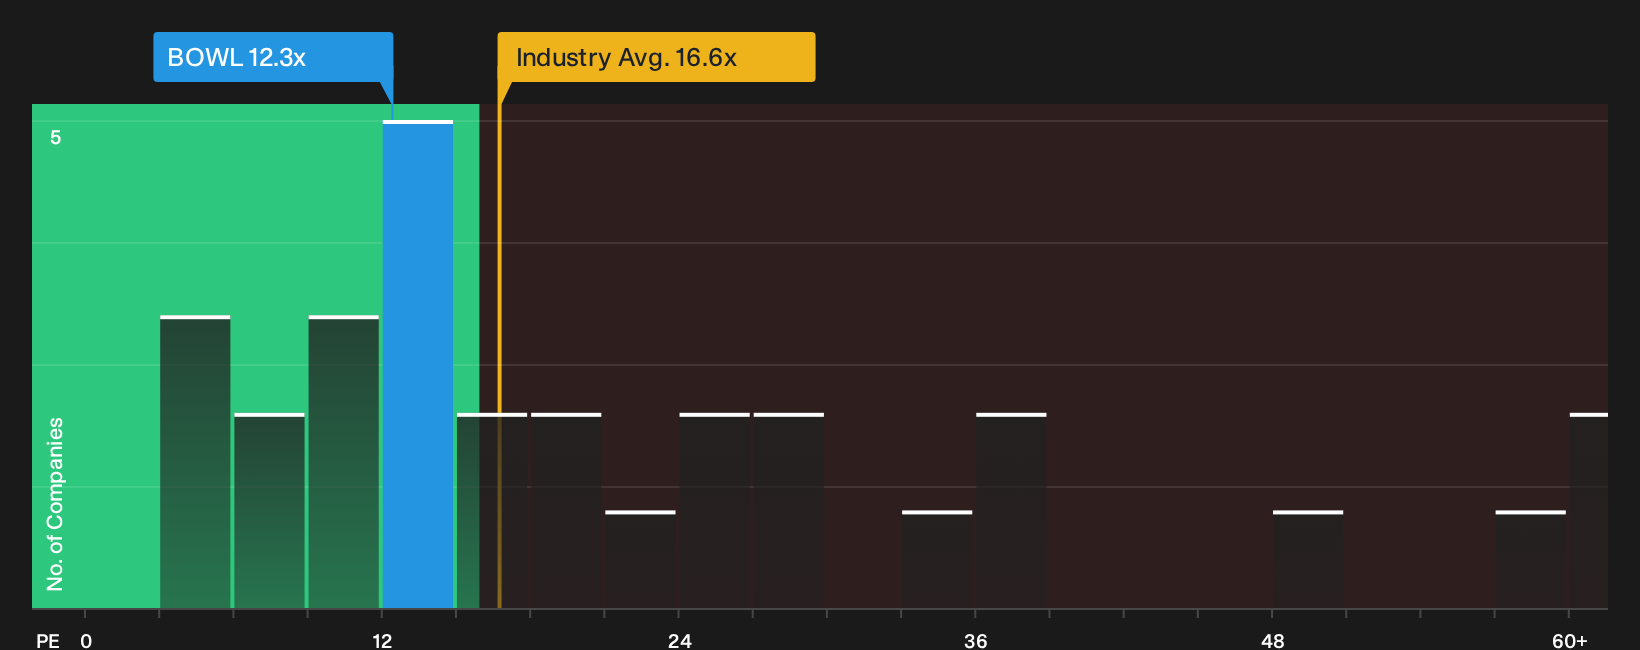
Hollywood Bowl Group brings the Financially Fit Penny Stocks theme to life through busy bowling alleys, mini golf courses and arcades that keep families coming back, feeding steady cash flows into a relatively small cap business. With a P/E around 12.3x against higher hospitality benchmarks and ROE above 21%, the key question is how one unseen funding pressure may influence that cash generation story.
That unseen pressure sits in the background as you weigh Hollywood Bowl Group’s cash engine, so head to the analysis report for Hollywood Bowl Group for what could be driving the next move.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is an infrastructure and private equity manager that channels growth capital into early-stage and emerging companies.
Operations: Foresight Group Holdings generates about £115 million from Real Assets and £50 million from Private Equity, mostly from the UK.
Market Cap: £504 million
Foresight Group Holdings matters for the Financially Fit Penny Stocks theme because it backs younger, earlier stage businesses while running a profitable, fee based investment platform that already throws off cash for shareholders.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
Much now turns on how one quietly rising cost line shapes the balance between those richer fee streams and the rewards investors are hoping for.
That rising cost line is only half the story, and the full narrative for Foresight Group Holdings explains how Foresight Group Holdings could still turn accelerating fee income into a stronger long term compounding engine.

Seeking Fresh Alternatives Before They Run
Markets move fast and the best breakout ideas rarely stay under the radar for long. Scan these fresh stock lists before momentum gets fully priced in and act now.
- Spot durable income opportunities by running through the 1 dividend fortresses while yields still look attractive and prices have not fully caught up.
- Track the next wave of automation by filtering for leaders inside the 89 robotics and automation stocks before investor enthusiasm sends valuations higher.
- Position ahead of the energy backbone upgrade by reviewing the curated 40 power grid technology and infrastructure stocks while the story is still forming and liquidity remains favorable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com