
LSL Property Services And 2 Other British Value Stocks To Watch
Energy prices have been climbing as strikes threaten North Sea oil output, which keeps inflation pressures alive and tightens the screws on UK consumers and companies. Markets tend to focus on headlines, so cash rich British businesses that quietly generate steady cash can slip through the cracks and trade cheaply. This piece looks at three UK stocks whose cash flows appear to be undervalued today.
These three ideas are only a starter pack, and the full screen has flagged 26 more cash rich, discounted businesses with stories that are just as compelling but not covered below. If you want to identify and analyze the highest conviction setups on this theme, head straight into the Undervalued Stocks Based On Cash Flows screener.
LSL Property Services (LSE:LSL)
Overview: LSL Property Services runs a capital light, fee-based property services group focused on UK surveying, mortgage advice and franchised estate agencies.
Operations: The group generates about £110.7 million from Surveying and Valuation, £48.2 million from Financial Services and £26.7 million from Estate Agency, all in the UK.
Market Cap: £244 million
LSL Property Services matters for this cash flow focused screen because its surveyor-led valuation work and mortgage advice networks produce recurring fees that can be mapped cleanly into a discounted cash flow model, particularly in periods when housing activity and refinancing cycles are supportive.
"Rising mortgage refinancing activity, with large volumes of two year and five year products maturing, should sustain higher new lending flows through LSL’s adviser network and underpin continued growth in Financial Services revenue and earnings."
The key issue from here is how one less obvious cost and pricing pressure shapes future margins on those steady fees.
Those margin questions make the next step clear: read the full narrative for LSL Property Services to see how LSL Property Services could turn pricing pressure into an advantage.

Distribution Finance Capital Holdings (AIM:DFCH)
Overview: Distribution Finance Capital Holdings is a UK lender that provides working capital and asset finance to manufacturers and distributors, generating recurring cash-driven interest income.
Operations: The group earns £60 million from commercial financial services in the United Kingdom, mainly through inventory, equipment and working capital lending.
Market Cap: £122 million
Distribution Finance Capital Holdings matters for this cash flow focused screen because its commercial lending book turns manufacturer and dealer financing into relatively steady interest receipts that can be mapped into a discounted cash flow model.
"The expansion from pure inventory finance into asset finance and structured finance gives Distribution Finance Capital Holdings more ways to serve the same manufacturers and dealers. This can support higher loan volumes and fee income over time, benefiting revenue and earnings."
The key variable now is how funding costs and credit losses evolve, because either could reshape those cash driven margins.
Those funding and credit swings are exactly why it pays to read the full narrative for Distribution Finance Capital Holdings, where Distribution Finance Capital Holdings’ risk curve and upside case are mapped out clearly.

Smiths News (LSE:SNWS)
Overview: Smiths News distributes newspapers and magazines and runs related logistics services that generate relatively predictable cash flows in the UK.
Operations: The group generates about £1.04b from Smiths News including DMD, with revenue almost entirely earned in the United Kingdom.
Market Cap: £190 million
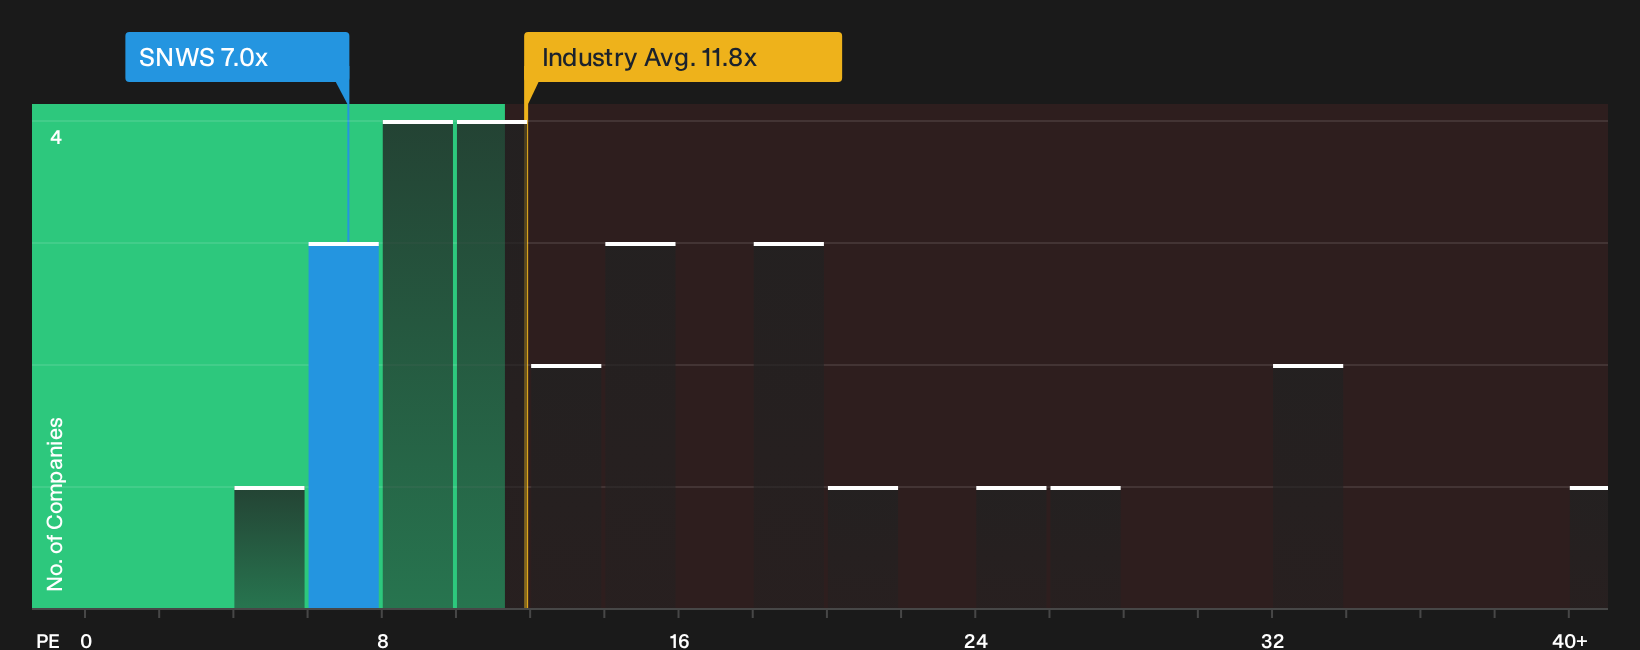
Smiths News fits this cash flow led screen because its UK newspaper and magazine logistics arm produces regular, contract backed income. At the same time, the stock trades on a P/E of 7x, below both its estimated fair P/E and peers near 29x. Investor interest centres on how one long term volume shock may influence those carefully modelled cash streams.
To see how that low P/E compares with contracts, the balance sheet and cash returns, head straight to the analysis report for Smiths News for the full picture.
Seeking Fresh Alternatives Before They Fly
Fresh breakouts, early momentum and under the radar setups rarely stay quiet for long. Prices move, narratives shift and edges decay fast. Scan these ideas before the crowd to explore opportunities at an earlier stage.
- Explore strong cash generators with room to rerate by scanning a curated mix of quality businesses using the 9 high quality undervalued stocks.
- Track the next wave of smarter automation by following hand picked enablers of machine intelligence through the 89 robotics and automation stocks.
- Monitor demand in critical materials by filtering focused producers through the 16 top copper producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com