
ASM Stock In Focus After New Chipmaking Film Launch
- ASM International launched XP8 Vertos Flowable Carbon, a PECVD flowable carbon film that combines gap fill and planarization in one process, targeting advanced logic and memory manufacturing.
- The product aims to cut process steps and defect risk by enabling void free, self planarizing gap fill without separate CMP or etch back stages, which directly affects cost and complexity in 3D scaling.
- This development may influence how ASM International's investment narrative is framed, as Vertos Flowable Carbon consolidates critical patterning steps.
Scan other patterning leaders riding the same 3D scaling trend as ASM International by zeroing in on our curated list of 90 AI infrastructure stocks.
ASM International Investment Narrative Recap
To own ASM International, you need to be comfortable with a story built on leading deposition and patterning gear tied to advanced logic and memory, while accepting real cyclicality and customer concentration. The biggest near term swing factor remains order intake at key 2 nm and 1.4 nm customers, after a period where bookings and book to bill trends have softened.
The XP8 Vertos Flowable Carbon launch sits in that context as a product execution milestone rather than a clear near term demand catalyst. It reinforces ASM International’s position in complex 3D patterning, but the larger risks around China exposure, currency swings and weaker segments like power and 3D NAND do not materially change on this news alone.
The most relevant recent development for this story is still the broader ramp of advanced nodes and high bandwidth memory that analysts link to ASM International’s addressable market. Vertos Flowable Carbon fits directly into that trend because it targets the complex, high aspect ratio structures used in leading edge logic and DRAM manufacturing.
For you as an investor, the question is whether ASM International can convert this type of product into sustained tool placements and a larger installed base, which can then support higher margin services. Execution risk remains, given reliance on a small group of leading customers and ongoing China and currency headwinds, but successful adoption would align with the existing earnings and revenue growth expectations that analysts have outlined.
ASM International Analyst Assumptions and Valuation Setup
ASM International's narrative projects €6.7b revenue and €1.8b earnings by 2029. According to these assumptions, analysts are factoring in 25.8% yearly revenue growth and an earnings increase of €0.7b from €1.1b today.
Uncover why ASM International's fair value indicates a 19% potential upside to its current price before the market closes that gap.
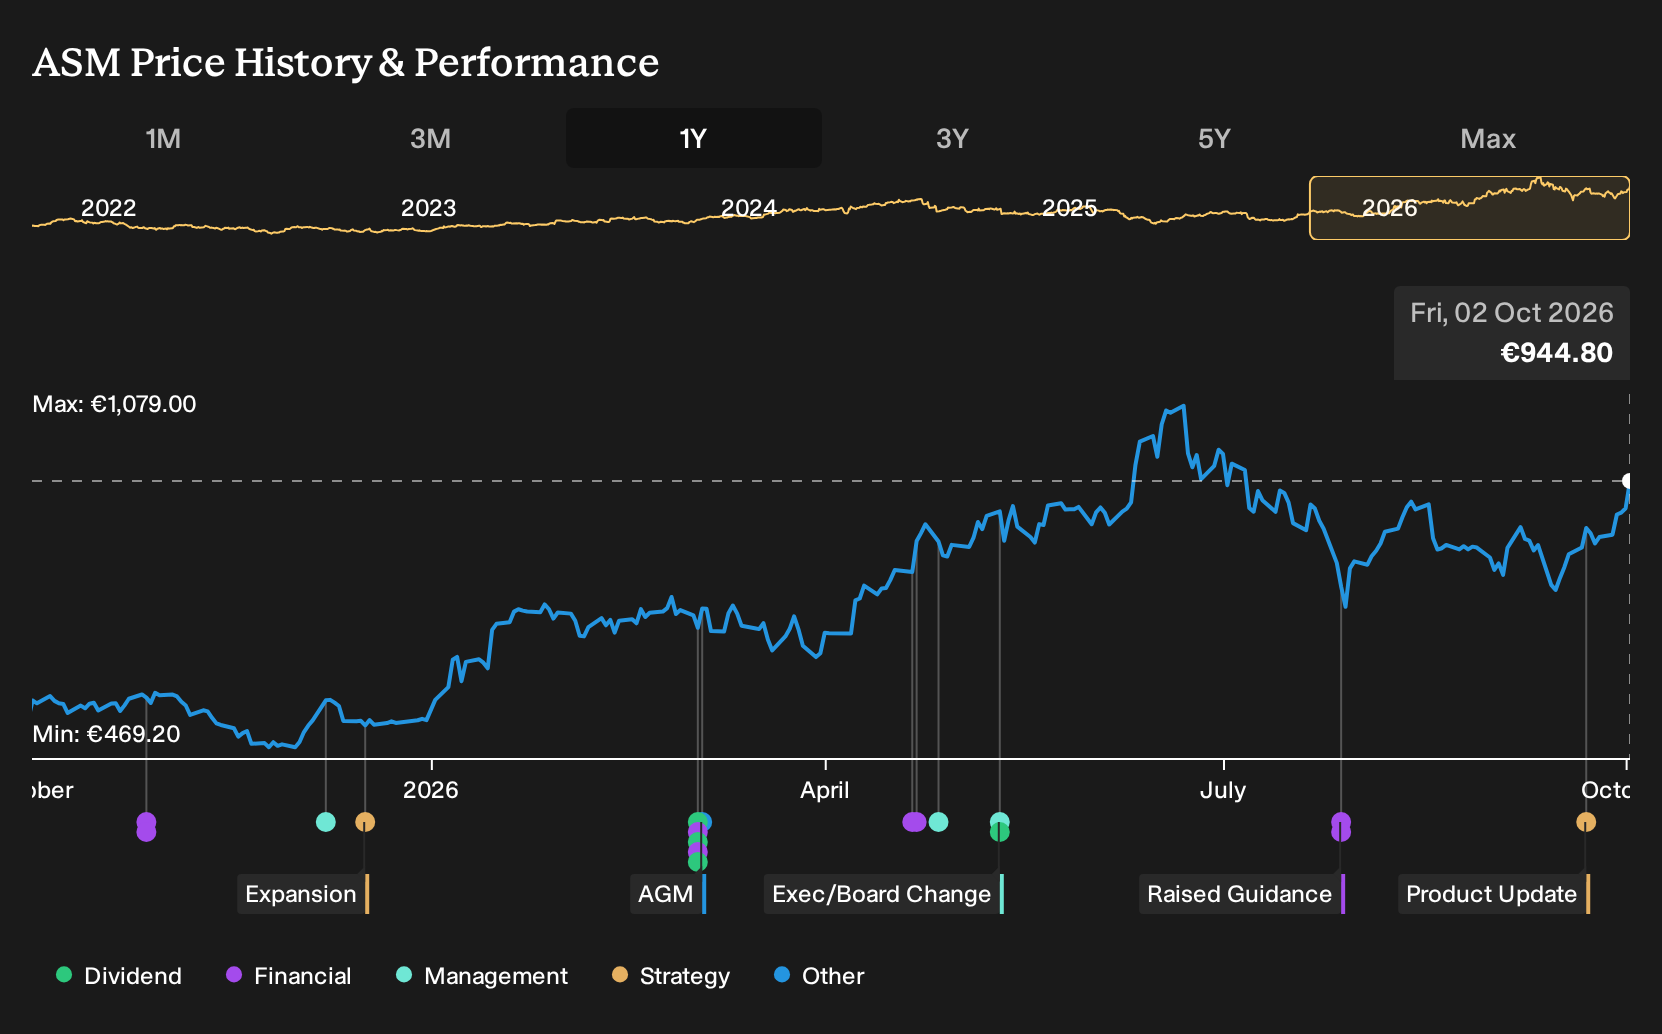
Exploring Other Perspectives
Some of the lowest ASM International forecasts lean hard into supply chain risk around new areas like flowable carbon PECVD. Those analysts were pencilling in about €6.5b revenue and €1.7b earnings by 2029, in contrast with more bullish peers closer to €2.5b earnings. You can treat the Vertos news as a fresh reason to compare these opposing views.
Explore 4 other ASM International fair value estimates, including one that suggests as much as 36% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ASM International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASM International's overall financial health at a glance.
Looking for more investment ideas beyond ASM International?
Once you have a handle on ASM International, it can help to cross check your thesis against other opportunities with different risk and income profiles. The Simply Wall St Screener gives you a fast way to scan wider markets without losing sight of balance sheet quality or valuation discipline.
- If capital preservation sits high on your list, you could start with a basket of resilient businesses via the 227 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors focused on cash flow today rather than only potential share price moves, consider using the 168 dividend fortresses to find income ideas with higher yield profiles.
- If you want to broaden your watchlist beyond well covered tickers, the 615 high quality undiscovered gems can surface smaller companies with solid underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com