
Natera (NTRA) Wins Japan Approval As Investors Ask If The Story Is Already Priced In
Natera (NTRA) is back in focus after Japan’s regulator cleared its Signatera test as a companion diagnostic for muscle invasive bladder cancer, directly linking its assay to adjuvant atezolizumab treatment decisions.
Natera’s latest regulatory win in Japan comes after a strong run in the ticker, with a 30-day share price return of 25.04% and a 90-day gain of 44.59%. This has contributed to a 79.32% year-to-date move and a 1-year total shareholder return of 145.20%.
Scan for other precision-medicine stories on the move by reviewing the hand picked 35 healthcare AI stocks benefiting from regulatory momentum and real world clinical adoption.
Natera’s share price has already run hard on Signatera’s momentum. The next step is to test whether the current valuation still leaves meaningful upside, or whether it already prices in most of the story.
Most Popular Narrative: 15% Overvalued
The most followed narrative now pegs Natera’s fair value at $355.93, which sits below the last close of $410.35 and frames the recent rally as pricing in a premium story that still leans heavily on MRD leadership and reimbursement support.
Fair Value has risen slightly from $344.33 to $355.93, reflecting a modest uplift in the valuation estimate for Natera.
Future P/E has risen slightly from 155.74x to 161.38x, implying a somewhat higher multiple being applied to Natera’s expected earnings profile.
See why 19 investors see Natera as 15% overvalued.
Result: Fair Value of $355.93 (OVERVALUED)
Still, the narrative around Natera could shift quickly if reimbursement policy tightens or if high R&D and commercial spending keeps profitability under pressure for a longer period.
Find out about the key risks to this Natera narrative.
Another View: Natera Through A Cash Flow Lens
Analysts using multiples see Natera as trading rich versus their $355.93 fair value marker, yet our DCF model points in a very different direction. On that framework, the shares change hands about 30% below an estimated future cash flow value of $585.80, which raises a simple question. Is the premium story already overcooked, or is the market underpricing what sustained MRD adoption could mean for long run cash generation?
For readers who want to see how that cash flow view is built from the ground up, it is worth reviewing the full SWS DCF model output for Natera, including the assumptions that drive the $585.80 estimate and how sensitive it is to changes in margins or growth: Look into how the SWS DCF model arrives at its fair value..
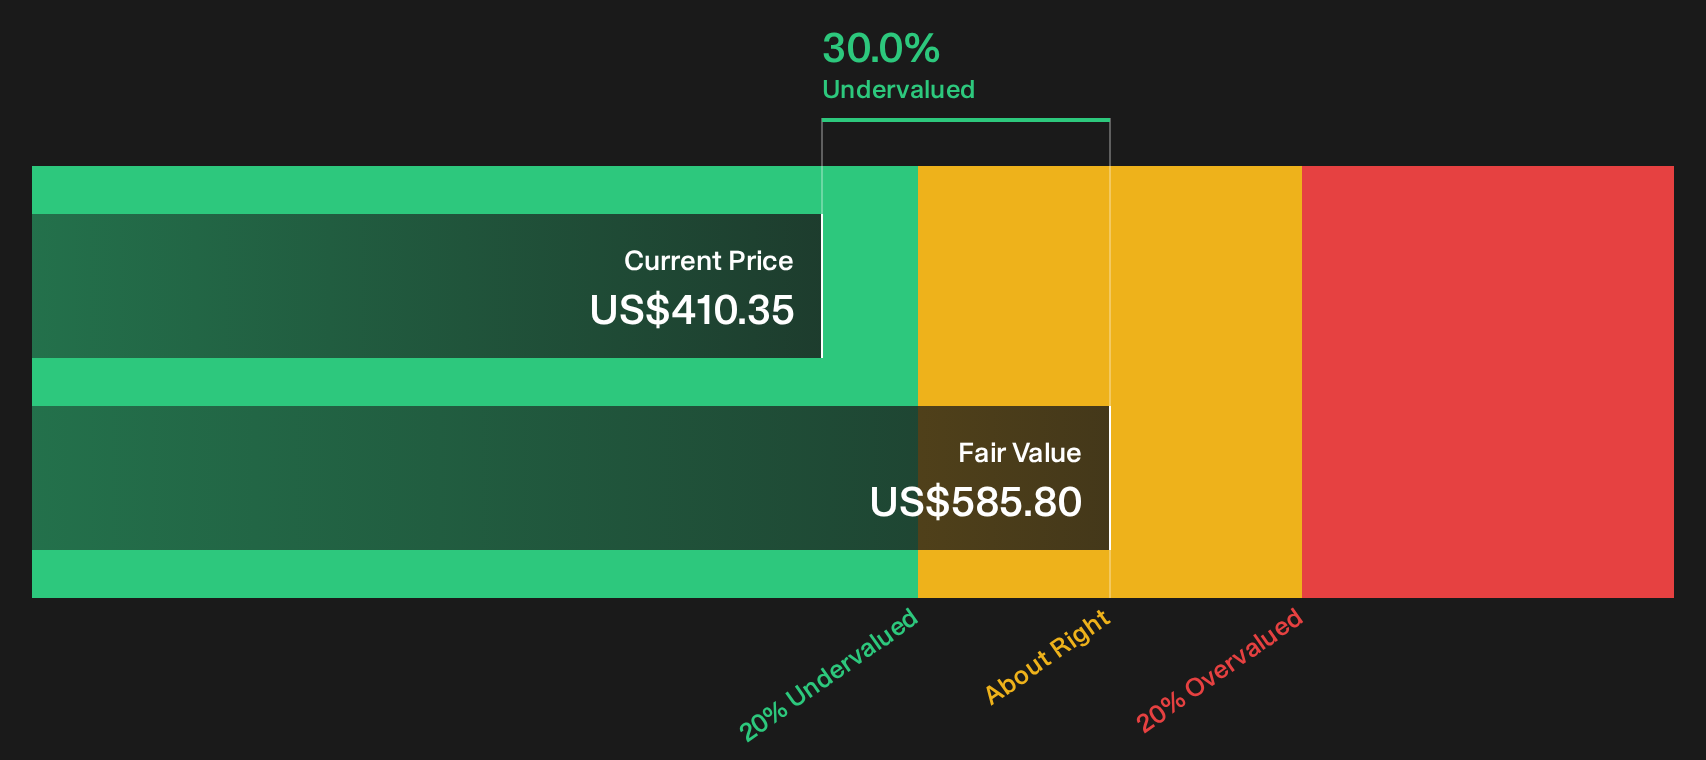
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natera for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Natera is mixed, with fair value signals and cash flow views pulling in different directions, so move quickly and stress test the story against your own expectations. To see what optimism is already reflected in the data and decide whether it matches your thesis, start by reviewing the 3 key rewards.
Looking for more investment ideas beyond Natera?
If Natera has sharpened your view on risk, reward, and timing, you can use that momentum to widen your opportunity set with targeted stock ideas built from the same data engine.
- Target potential mispricing by scanning a curated 31 high quality undervalued stocks that blends strong fundamentals with discounted expectations.
- Prioritise balance sheet strength by reviewing a list of solid balance sheet and fundamentals (25 results) that can help support resilience through different market conditions.
- Hunt for future standouts early by focusing on a 19 high quality undiscovered gems before the wider market fully catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com