
SEI Investments (SEIC) Opens In Singapore, Is The 12% Undervaluation Enough?
SEI Investments (SEIC) just planted a flag in Singapore, opening a new office and appointing Connall McGuckian as Managing Director, Head of Singapore, to lead its Asia-Pacific growth push.
SEI Investments is extending this business push into its share price story, with the stock giving up some ground recently as the 1-month share price return declined 7.21%. However, longer term momentum remains positive, with a 23.39% year-to-date share price return and a 5-year total shareholder return of 85.07%.
Scan how SEI Investments fits alongside other financial firms by applying the same lens to our hand picked list of solid balance sheet and fundamentals (25 results).
SEI Investments has cooled off after a strong multi year run, just as it leans into new growth routes like Singapore. Is the recent pullback creating fresh upside, or has most of the easy return already been taken?
Most Popular Narrative: 12% Undervalued
SEI Investments is trading at $102.43, while the most followed narrative pins fair value closer to $115.86. This frames the recent pullback as a discount to that estimate rather than a clear warning sign.
Professional services and Data Cloud offerings are being scaled across the company, with leadership roles created to expand these 30 to 40% margin services beyond Private Banking into other segments. This can lift blended operating margins and earnings over time as attach rates rise.
See why 5 investors see SEI Investments as 12% undervalued.
Result: Fair Value of $115.86 (UNDERVALUED)
Still, the SEI Investments story could be knocked off course if lower fee ETFs and separate accounts weigh on the revenue mix or if insider selling keeps undermining confidence.
Find out about the key risks to this SEI Investments narrative.
Another View on SEI Investments: Ratios Tell a Different Story
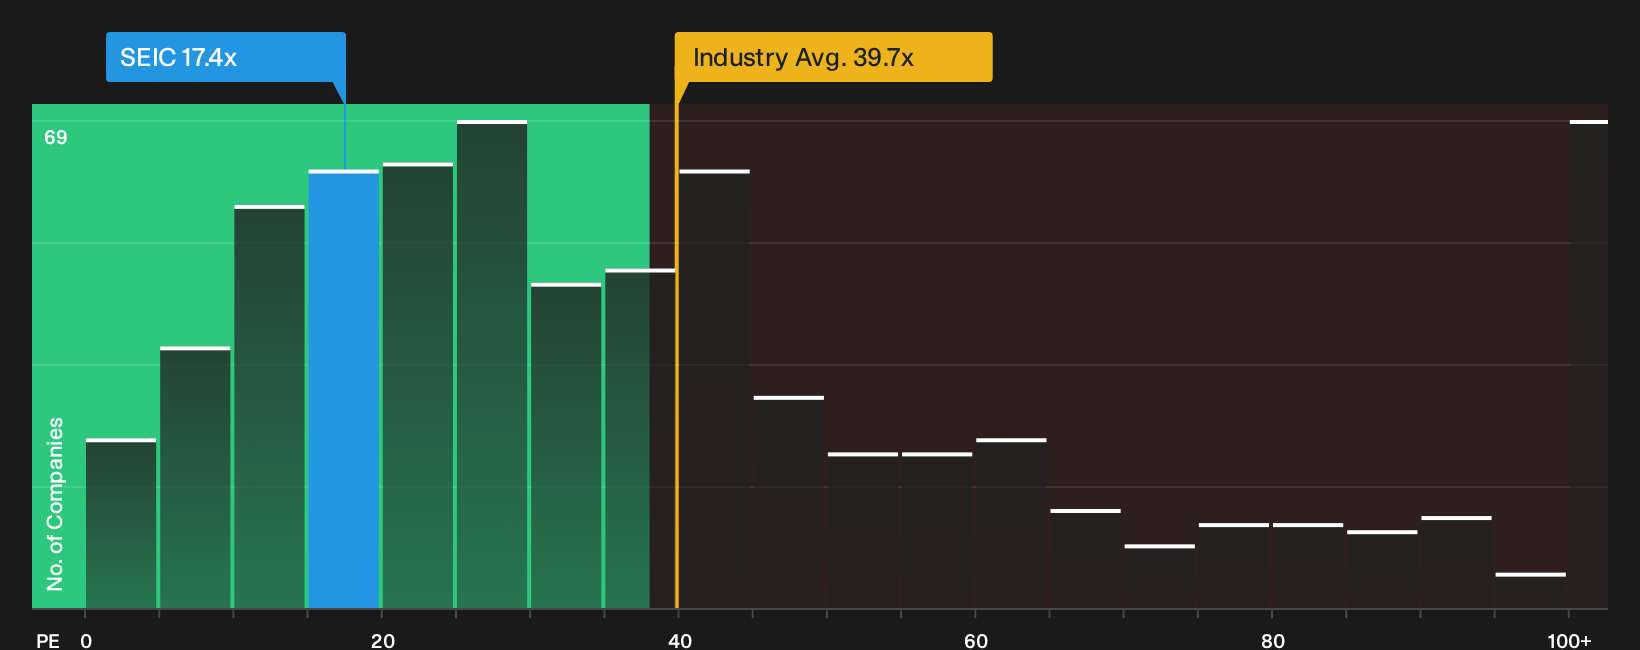
SEI Investments screens as undervalued on cash flow, yet the P/E picture is less generous. The stock trades at 17.4x earnings while the fair ratio estimate sits closer to 11.7x. That higher multiple could mean investors are already paying up and leaving less room if sentiment cools.
For a closer look at how this earnings multiple stacks up against the broader industry and peers, and what that gap might mean for risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the split tone around SEI Investments has you on the fence, consider reviewing the full mix of risks and bright spots, and weigh the 3 key rewards and 1 important warning sign.
Looking for more SEI Investments style ideas?
If SEI Investments has caught your attention, do not stop here. Broaden your watchlist with fresh ideas built from the same disciplined, data driven lens.
- Target resilient compounding potential by focusing on businesses that combine quality metrics with attractive entry points using the 31 high quality undervalued stocks.
- Prioritise sleep at night stability by filtering for companies that score well on financial strength through the 31 resilient stocks with low risk scores.
- Hunt for tomorrow's quiet winners by scanning lesser known but fundamentally strong opportunities with the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com