
Accenture And 2 Stocks That May Be Priced Below Their Estimated Value
Over the last 7 days, the United States market has remained flat, yet it is up 12% over the past year with earnings forecast to grow by 18% annually. In such an environment, identifying stocks that may be priced below their estimated value can offer potential opportunities for investors seeking to capitalize on future growth prospects.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $63.17 | $125.29 | 49.6% |
| PPG Industries (PPG) | $105.15 | $202.16 | 48% |
| OP Bancorp (OPBK) | $15.48 | $30.50 | 49.2% |
| Northeast Bank (NBN) | $126.86 | $247.60 | 48.8% |
| M&T Bank (MTB) | $219.14 | $422.17 | 48.1% |
| KeyCorp (KEY) | $20.08 | $39.84 | 49.6% |
| Inter & Co (INTR) | $5.48 | $10.72 | 48.9% |
| Insteel Industries (IIIN) | $29.56 | $56.86 | 48% |
| Fulton Financial (FULT) | $22.81 | $44.83 | 49.1% |
| Civista Bancshares (CIVB) | $26.98 | $53.30 | 49.4% |
Let's dive into some prime choices out of the screener.
Accenture (ACN)
Overview: Accenture plc offers strategy and consulting, industry X, song, and technology and operation services across the Americas, Europe, the Middle East, Africa, and the Asia Pacific with a market cap of $118.54 billion.
Operations: The company's revenue segments include Products at $22.45 billion, Resources at $9.93 billion, Financial Services at $13.96 billion, Health & Public Service at $15.17 billion, and Communications, Media & Technology at $12.67 billion.
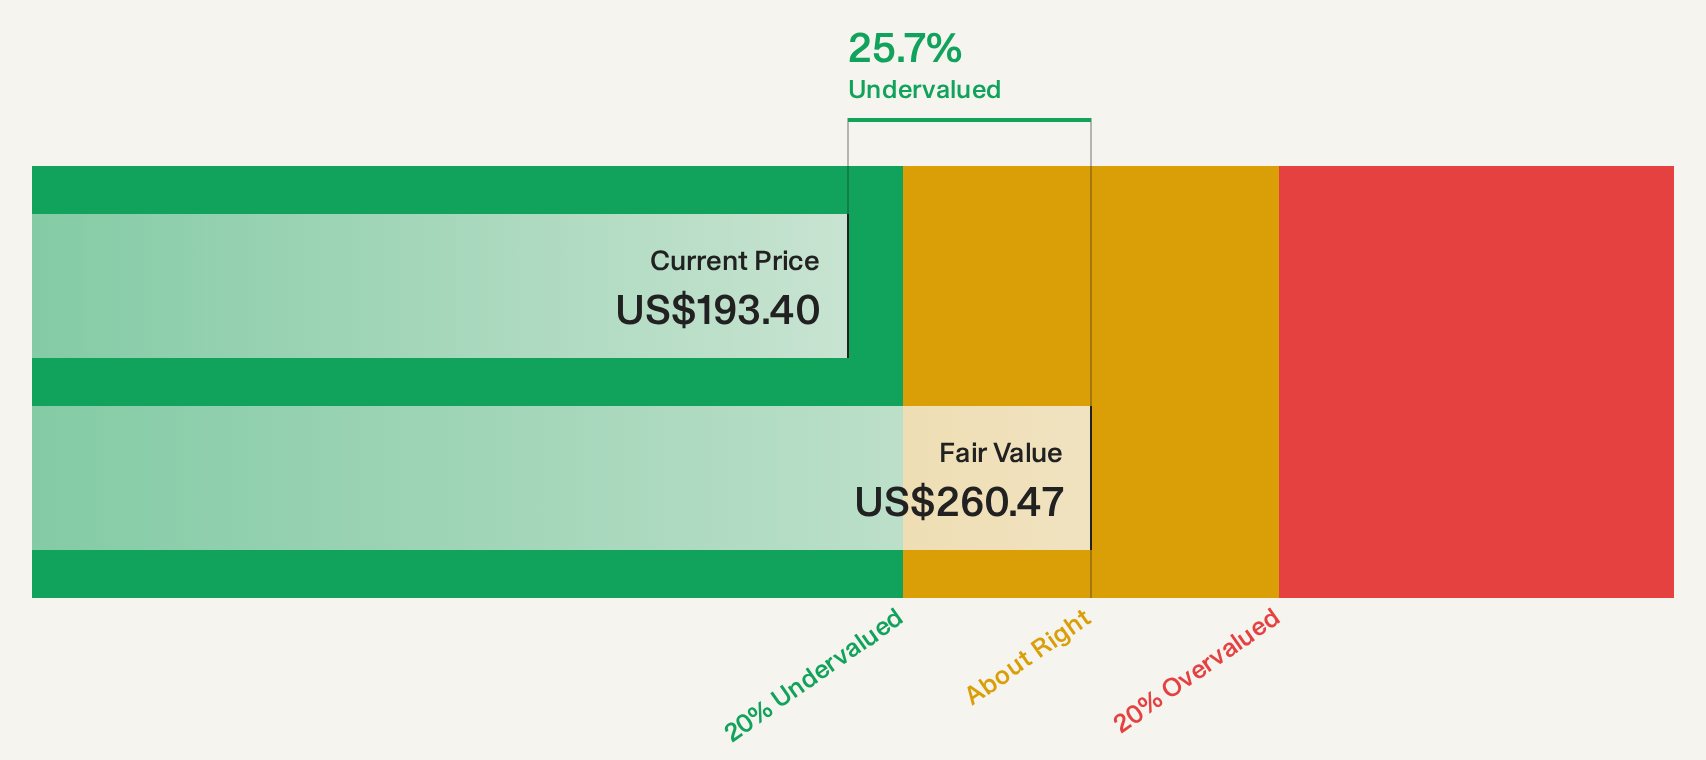
Estimated Discount To Fair Value: 25.4%
Accenture is trading at US$198.9, below its estimated future cash flow value of US$266.46, indicating potential undervaluation based on cash flows. The company reported strong earnings growth with a net income increase to US$8.37 billion for the year ended August 31, 2026, and forecasts a moderate revenue growth of 3% to 6% for fiscal year 2027. Accenture also maintains a reliable dividend yield of 3.44%.
- Our comprehensive growth report raises the possibility that Accenture is poised for substantial financial growth.
- Get an in-depth perspective on Accenture's balance sheet by reading our health report here.
Cencora (COR)
Overview: Cencora, Inc. sources and distributes pharmaceutical products both in the United States and internationally, with a market cap of $58.98 billion.
Operations: The company's revenue segments include U.S. Healthcare Solutions at $300.10 billion and International Healthcare Solutions at $32.33 billion.
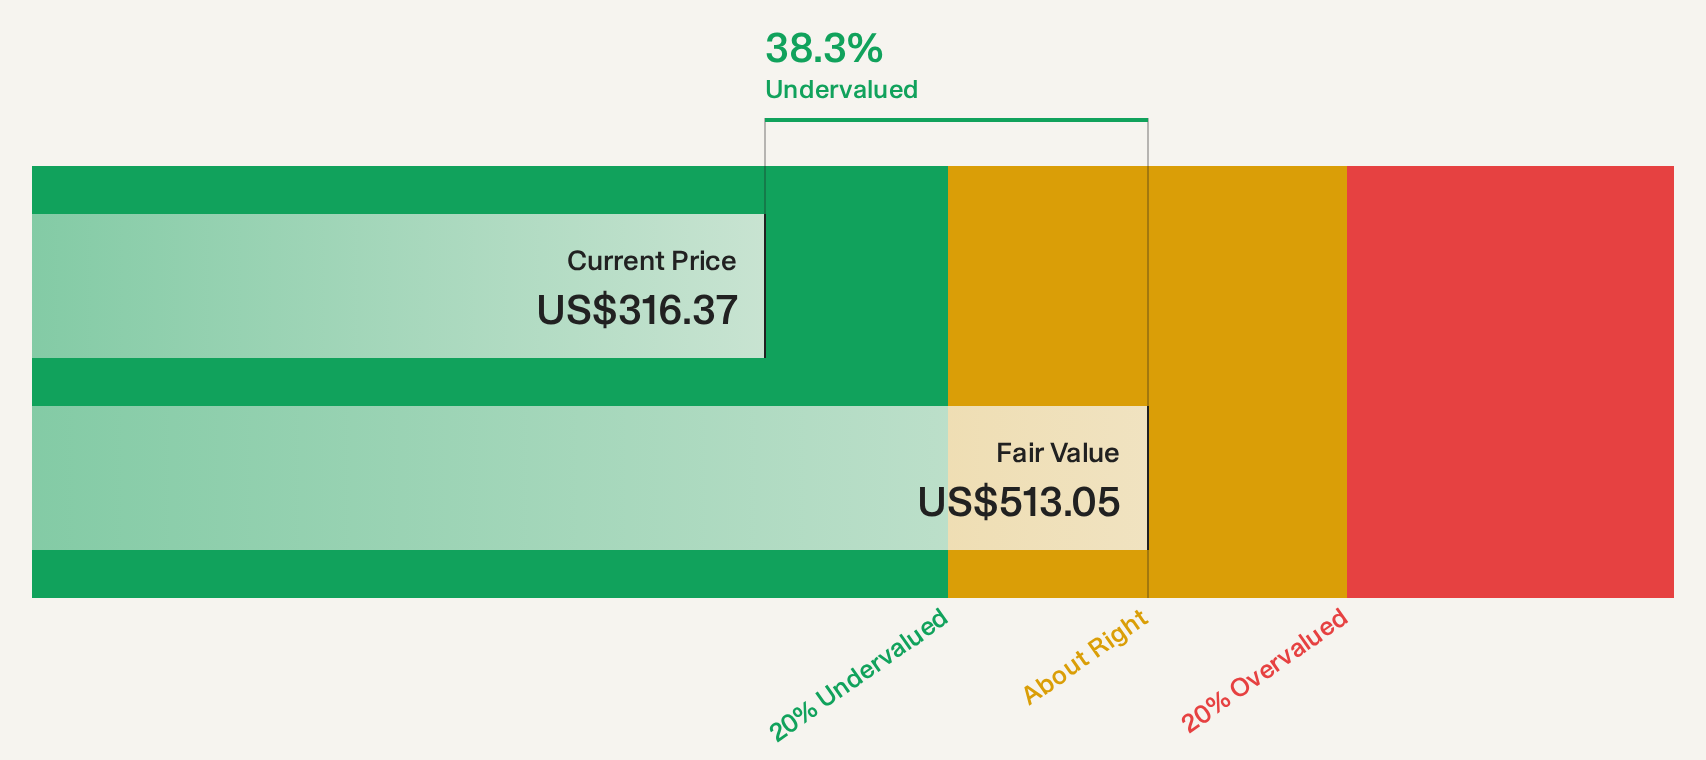
Estimated Discount To Fair Value: 39.8%
Cencora, trading at US$309.05, is valued below its estimated future cash flow value of US$513.05, suggesting it is undervalued based on cash flows. Despite high debt levels, the company demonstrates strong earnings growth with net income rising to US$2.96 billion for the nine months ended June 30, 2026. Recent strategic initiatives include expanding its cell and gene therapy services to enhance healthcare access and operational readiness for health systems.
- In light of our recent growth report, it seems possible that Cencora's financial performance will exceed current levels.
- Navigate through the intricacies of Cencora with our comprehensive financial health report here.
Oracle (ORCL)
Overview: Oracle Corporation provides products and services for building, running, and supporting enterprise information technology frameworks globally, with a market cap of $431.38 billion.
Operations: The company's revenue is primarily derived from its Cloud and software segment at $62.78 billion, followed by Services at $5.81 billion, and Hardware at $3.19 billion.
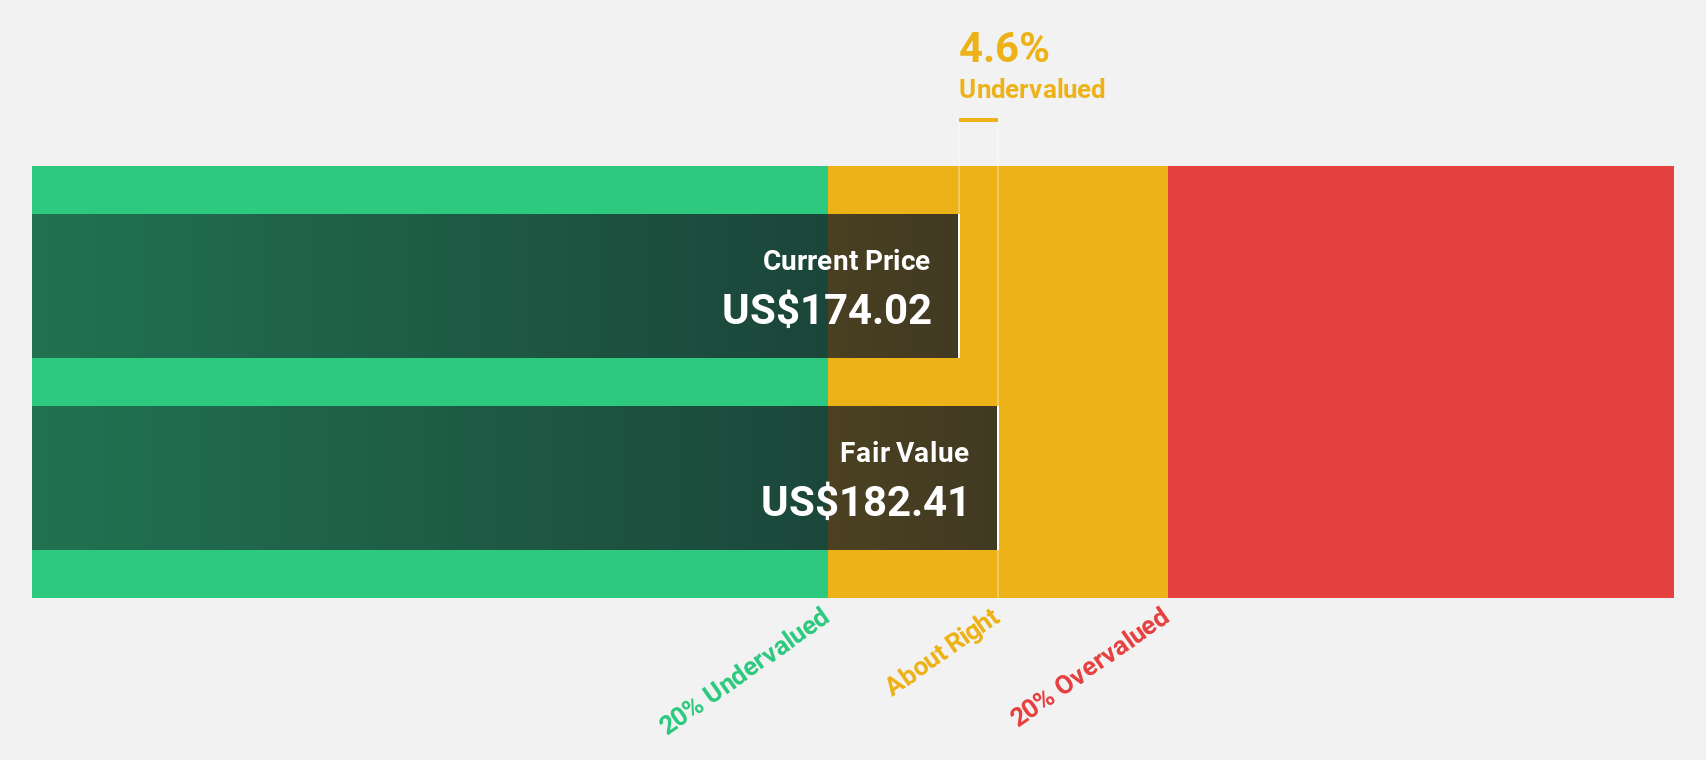
Estimated Discount To Fair Value: 26.8%
Oracle, trading at US$142.3, is undervalued based on its cash flow value of US$194.51. Despite a high debt level and a dividend not well covered by free cash flows, Oracle demonstrates strong earnings growth with net income rising to US$4.76 billion for the first quarter ended August 31, 2026. Recent developments include new AI-driven applications and strategic partnerships enhancing cloud infrastructure capabilities, positioning Oracle for significant future growth in enterprise solutions and digital asset management.
- Upon reviewing our latest growth report, Oracle's projected financial performance appears quite optimistic.
- Click here and access our complete balance sheet health report to understand the dynamics of Oracle.
Where To Now?
- Delve into our full catalog of 101 Undervalued US Stocks Based On Cash Flows here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com