
AltaGas (TSX:ALA) Could Be 12% Undervalued Following Its $750 Million Debt Move
Why AltaGas Stock Is Back In Focus After A Major Debt Move
AltaGas (TSX:ALA) has just completed a US$750 million senior unsecured notes issue at 5.75% due 2031, a financing decision that directly targets its existing debt stack and interest costs.
The new bonds are guaranteed by AltaGas and rank equally with its other senior unsecured obligations. Management is directing the proceeds toward repaying credit facility borrowings and retiring medium term notes.
AltaGas has ridden a strong run over the past year, with the share price delivering a year to date gain of 26.39% and a 1 year total shareholder return of 26.78%. The 3 year and 5 year total shareholder returns of 125.77% and 155.58% point to momentum that has been building over a longer stretch, even as the 90 day share price return has softened slightly. This sets the latest debt refinancing against a backdrop of sustained compounding for long term holders.
Scan capital-disciplined utilities like AltaGas that balance debt moves with operating scale by starting with our hand picked 8 resilient stocks with low risk scores in this part of the market.
AltaGas has tidied up its balance sheet and the share price has already rewarded that move in a big way. Does the current tag still offer enough upside for the risk you take on at CA$53.31?
Most Popular Narrative: 11.6% Undervalued
On the widely followed narrative, AltaGas screens as undervalued, with an assessed fair value of around CA$60.27 versus the CA$53.31 last close. This puts the fresh debt issue into a tighter pricing frame.
AltaGas's growing LPG export platform (RIPET, Ferndale, and REEF construction with proven commercial support and phased optimization/expansion plans) aligns with increasing Asian demand for low-carbon transitional fuels, creating diversified, higher-margin revenue streams and margin expansion opportunities.
See why 31 investors see AltaGas as 12% undervalued.
Result: Fair Value of CA$60.27 (UNDERVALUED)
Still, AltaGas faces policy risk around decarbonization efforts and high ongoing infrastructure spending, either of which could pressure future earnings and challenge today’s valuation story.
Find out about the key risks to this AltaGas narrative.
Another View On AltaGas Valuation
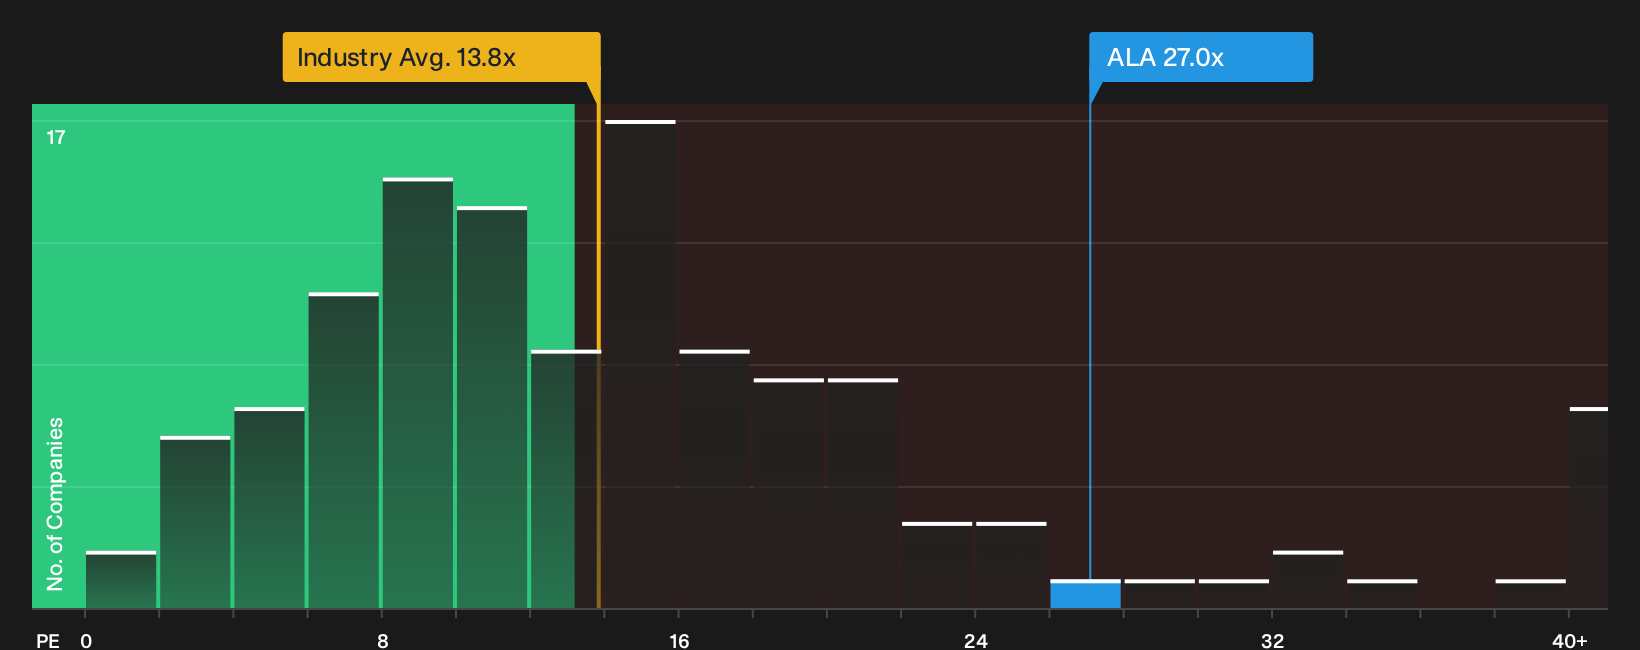
The first take on AltaGas uses a discounted cash flow style fair value. A different yardstick, the P/E ratio, tells a less comfortable story. AltaGas trades at 27x earnings, which is about double the global gas utilities average of 13.8x and still well below a fair ratio of 32.7x that the model suggests the market could move toward.
That gap means the stock appears cheaper than this fair ratio implies, yet expensive compared with the wider industry and still rich versus some peers at 44.3x. For an investor weighing fresh capital, this raises a question: is this a margin of safety or a signal that expectations leave limited room for mistakes on execution and regulation?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the AltaGas story so far. If you want to move quickly and build your own stance, start by weighing these 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond AltaGas?
If AltaGas sharpened your thinking, keep that momentum going. Fresh ideas often come from scanning outside your usual watchlist.
Use the Simply Wall Street Screener to quickly scan resilient themes, compare fundamentals, and spot opportunities you might otherwise miss.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (7 results) that pair financial strength with more durable business models.
- Hunt for mispriced quality as you sift through the 6 high quality undervalued stocks that combine solid fundamentals with more attractive valuations.
- Lock in potential income ideas by assessing the 1 dividend fortresses that focus on higher yield and sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com