
Curtiss Wright (CW) Plans CEO Handover, Is The Stock Still A Bargain?
Curtiss-Wright (CW) has scheduled its long-planned leadership transition, with Kevin M. Rayment set to become CEO and President in early 2027 as Lynn M. Bamford moves to Executive Chair.
Curtiss-Wright shares, which last closed at US$545.64, have seen short term momentum soften, with a 30 day share price return down 3.72% and a 90 day move down 28.82%. However, the 3 year total shareholder return of 173.74% and 5 year total shareholder return of 329.16% still indicate a strong longer term payoff profile as investors weigh the planned CEO handover and what it might mean for future growth and risk.
Scan how other aerospace, defense and industrial players with similar leadership or capital allocation stories stack up in our curated list of solid balance sheet and fundamentals (25 results) to see what else is moving.
After Curtiss-Wright’s sharp pullback and with the stock now trading well below the average analyst target, the real puzzle is where fair value sits within the gap between recent price action and those estimates.
Most Popular Narrative: 31% Undervalued
Curtiss-Wright’s most followed valuation view pegs fair value at about $786, comfortably above the last close at $545.64. This puts the current pullback against a backdrop of backlog driven growth assumptions and a higher discount rate of 8.03%.
Backlog and order visibility remain central to the thesis, with total orders up 12% year to date against 9% sales growth, a book to bill above 1.2x, and backlog at US$4.3b. Taken together with raised 2026 sales, margin, and EPS guidance, these factors can support the idea that current pricing undervalues the potential operating leverage into revenue and net margin over the next few years.
See why 14 investors see Curtiss-Wright as 31% undervalued.
Result: Fair Value of $786.25 (UNDERVALUED)
Still, if US$4.3b of backlog converts more slowly than expected, or if valuation concerns keep a 50.2x future P/E out of reach, the Curtiss-Wright story could look very different.
Find out about the key risks to this Curtiss-Wright narrative.
Another View: Curtiss-Wright Valuation Through The P/E Lens
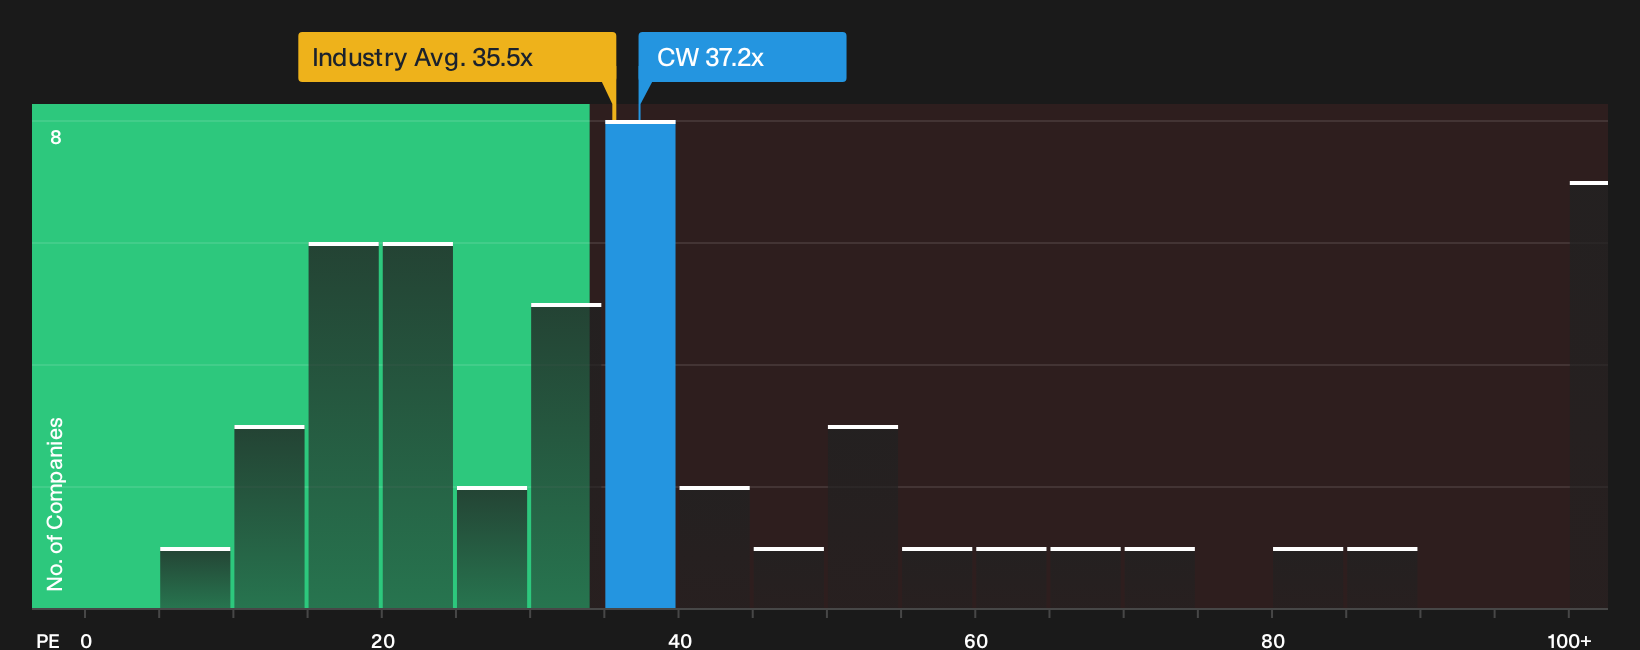
The DCF style narrative around Curtiss-Wright points to undervaluation, yet the simple P/E check tells a different story. The stock trades on 37.2x earnings versus 35.5x for the wider US Aerospace & Defense group, while the fair ratio is 23.8x. That gap suggests investors are paying a clear premium, which could either compress or persist depending on how the thesis plays out.
To see what the numbers say about this price, including how that premium compares with peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Curtiss-Wright story so far feels mixed to you, that is the point. The real edge comes from checking the evidence yourself before sentiment shifts again. To see why some investors focus on its upside potential, review the 3 key rewards.
Looking For More Ideas Beyond Curtiss-Wright?
You have seen how complex a single story like Curtiss-Wright can be, so do not stop here. Use focused stock lists to broaden your opportunity set intelligently.
- Target durable returns by scanning companies with resilient fundamentals and steady balance sheets through the 31 resilient stocks with low risk scores.
- Hunt for potential mispricings by checking companies that combine quality fundamentals with attractive pricing using the 31 high quality undervalued stocks.
- Prioritize strength and staying power by reviewing financially sound businesses that pass strict balance sheet and fundamentals filters in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com