
Millrose Properties (MRP) Stock Still Looks Undervalued Following $1 Billion Notes Offering
Millrose Properties has seen its share price slide in recent weeks, and the drop is pushing investors to ask a simple question about the stock. Is the current valuation still supported by the earnings that underpin this real estate rental and home acquisition business?
- The share price is down 29.7% over the past month, which puts sharper focus on whether the current earnings base can support even this lower level.
- Recent news that Millrose is buying large volumes of homes from Lennar and funding potential acquisitions with US$1.0b of senior notes means future earnings may need to cover higher debt costs and returns on a growing property portfolio.
- There is a second opinion on Millrose Properties worth weighing. See what analysts think Millrose Properties's shares could be worth.
The issue now is whether Millrose Properties' current price is justified by the earnings the business is generating today and is expected to produce over time.
If you want a broader watchlist while you assess Millrose Properties and its recent setbacks, consider using a focused stock screen built around 27 high quality undervalued stocks.
Is Millrose Properties Still Cheap on Earnings?
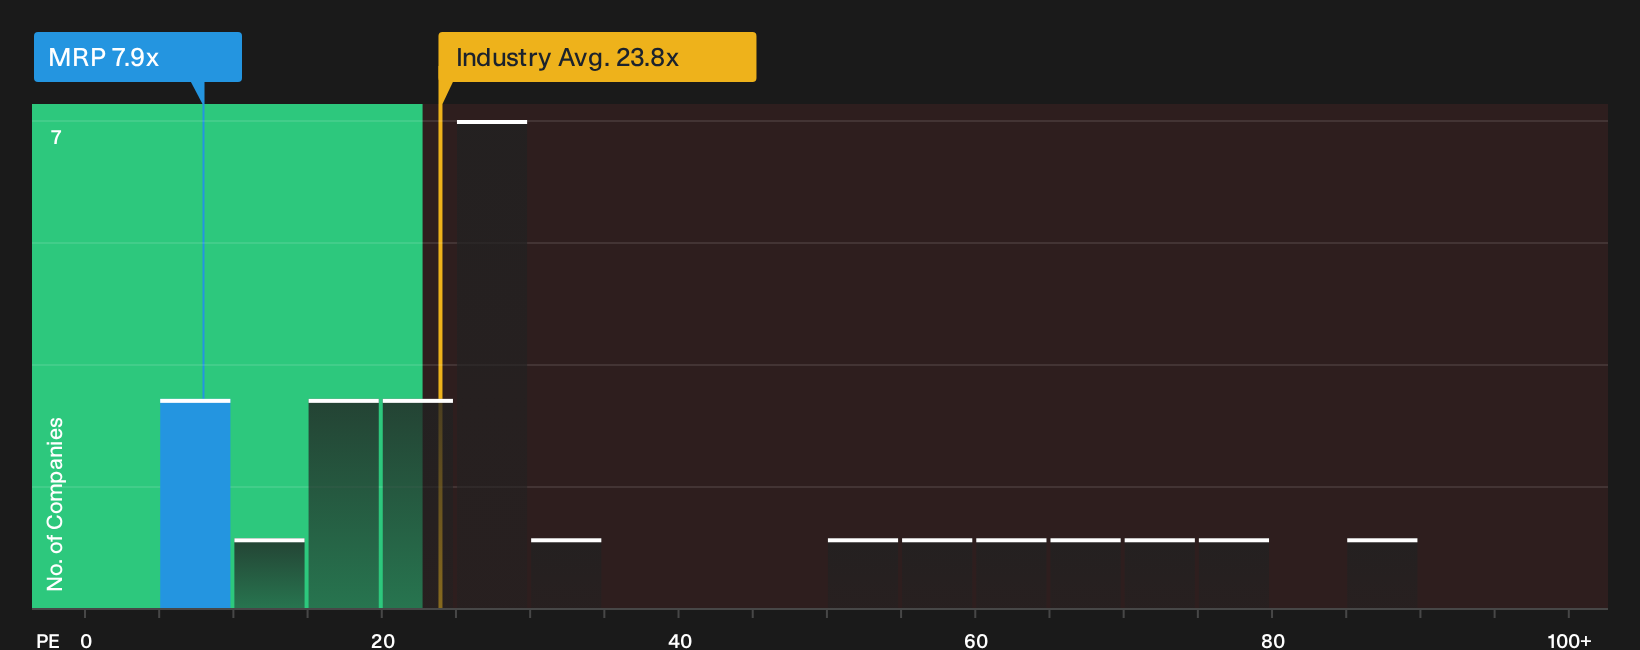
P/E fits Millrose Properties because earnings are the core lens most investors use for real estate businesses that are already generating profit. On that yardstick, Millrose trades on roughly 7.9x earnings, which is well below the Specialized REITs industry average of about 15.8x and also under the wider peer group on roughly 17.5x. The Fair Ratio, which reflects what might be expected given Millrose Properties' own risk profile and business mix, sits higher than the current market multiple, so the stock screens as undervalued on this approach.
Because the company is now issuing US$1.0b of senior notes to help fund further home purchases and corporate initiatives, the gap in P/E suggests investors are pricing in those higher financing needs very cautiously despite that expansion push. For anyone following Millrose Properties after the recent share price slide, the current discount on earnings-based metrics signals that the market is not paying a premium for its current profit stream. Explore the numbers behind Millrose Properties's P/E valuation.
The Millrose Properties Narrative: What Would Justify Today's Price?
Narratives pick up where Millrose Properties' valuation puzzle leaves off and spell out which future paths for earnings, margins and growth would need to play out for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Each scenario treats fair value as a hypothesis about Millrose Properties' business that you can watch over time, rather than a single frozen snapshot.
One of the top community narratives on Millrose Properties: 39% undervalued
"Expanding national relationships with 12 homebuilder counterparties and growing penetration of existing programs, such as the Yardly build to rent partnership…"
Discover why this Narrative puts Millrose Properties at 39% undervalued.
One more angle on Millrose Properties that could change the story
Share price moves and earnings multiples only tell part of the story for Millrose Properties, because the people setting priorities and rewarded for specific outcomes can heavily influence how those numbers evolve over time. See who runs Millrose Properties and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com