
Cochlear (ASX:COH) Shares Moved, What Is Driving Attention Today?
Cochlear (ASX:COH) is in focus after confirming a class action in the Supreme Court of Victoria over its FY26 underlying net profit forecast, a development that raises fresh questions for investors.
The legal claim lands after a volatile stretch for Cochlear, with the share price up 4.2% on the day to A$130.66 but down 8.5% over 30 days and recording a year to date share price decline of 49.9%. The 1 year total shareholder return has fallen 53.1%, pointing to pressure on sentiment rather than any clear positive momentum building yet.
Compare Cochlear's legal overhang and valuation gap with a curated set of resilient companies in similar situations by scanning the 7 resilient stocks with low risk scores before you decide where fresh capital belongs.
Cochlear now trades at a sizeable discount to some fair value estimates, yet faces a fresh legal cloud after the FY26 forecast dispute. Is the market being too harsh or simply pricing in real risk?
Most Popular Narrative: 87% Overvalued
Cochlear last closed at A$130.66, yet the most followed narrative pegs fair value closer to A$70. This frames the current legal dispute against a backdrop of pricing that already looks stretched according to Robbo.
Despite the substantial fall in the share price, the company still does not appear obviously cheap given the uncertainty that remains. The price-to-earnings ratio remains above 20 times downgraded earnings, while some discounted cash flow models suggest fair value may sit materially below current prices.
See why 15 investors see Cochlear as 87% overvalued.
Result: Fair Value of A$70 (OVERVALUED)
Still, the Cochlear story could shift quickly if surgery volumes disappoint again or if rival hearing technologies start to win share faster than expected.
Find out about the key risks to this Cochlear narrative.
Another View: DCF Points The Other Way
While Robbo sees Cochlear as heavily overvalued at around A$130.66 versus a fair value of A$70, our DCF model lands in a very different place. On those cash flow assumptions, Cochlear screens as undervalued, with the shares trading about 42.5% below an estimated value of A$227.24. Which story do you trust more: the earnings multiple or the cash flow math?
That kind of gap between price and model output deserves a closer look at the moving parts behind it, not just the headline result. Look into how the SWS DCF model arrives at its fair value.
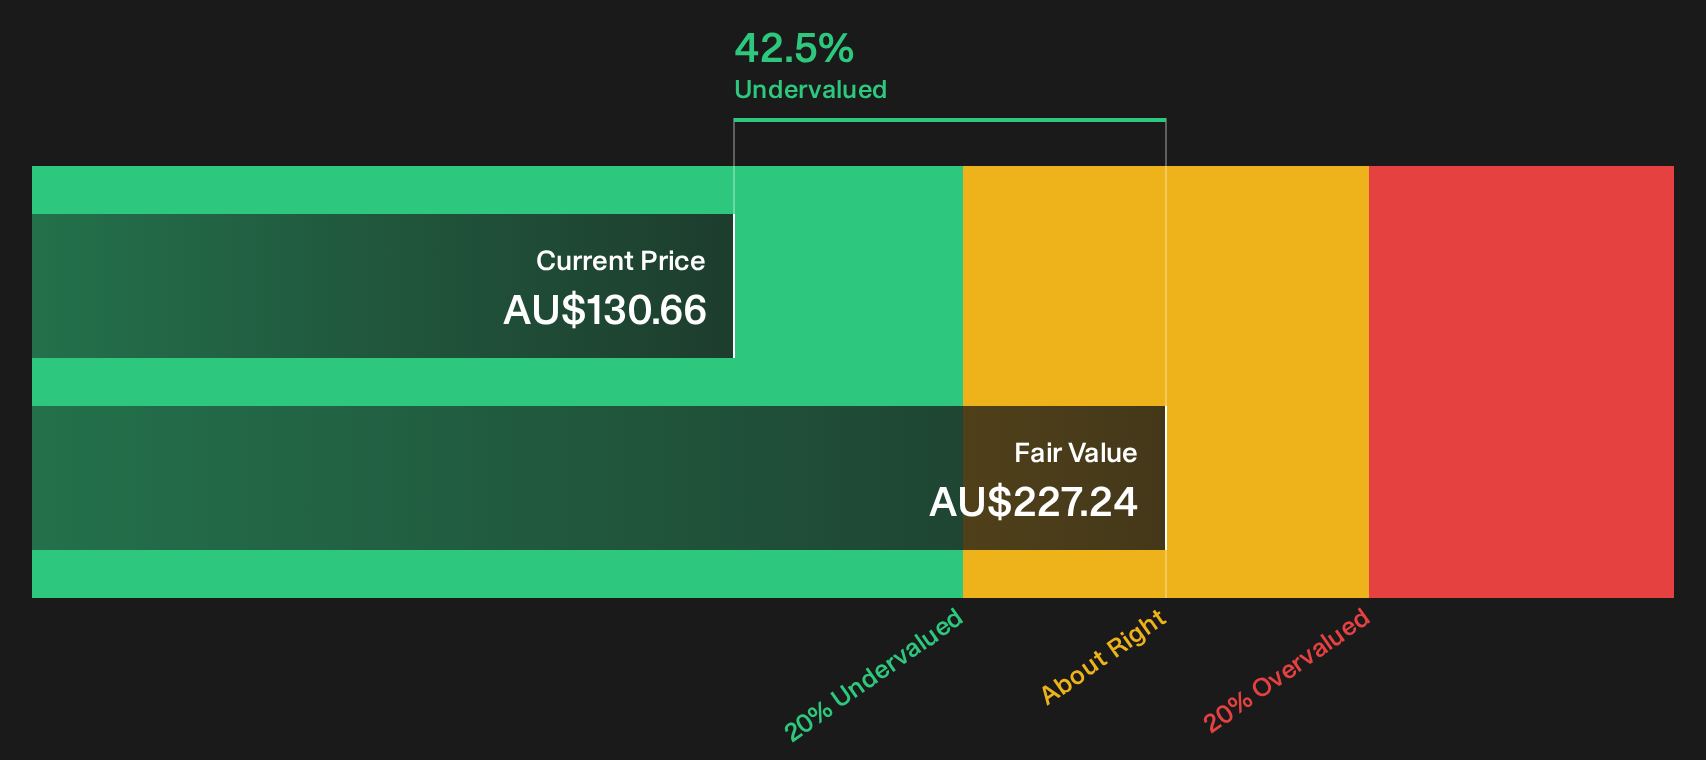
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cochlear for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed sentiment runs through Cochlear right now, with sharp price moves, legal questions and clashing valuation stories all in play. Act quickly, review the data for yourself and weigh both sides through the 2 key rewards and 2 important warning signs.
Looking for more Cochlear style investment ideas?
Do not stop with Cochlear. Use a few focused screeners to surface fresh opportunities that match your risk, income and quality preferences before the crowd notices.
- Target resilient performers by scanning a 7 resilient stocks with low risk scores that highlights businesses with steadier profiles when conditions get choppy.
- Hunt for potential mispricing by reviewing a 15 high quality undiscovered gems that filters for strong fundamentals away from the usual headlines.
- Strengthen your core holdings by leaning on a list of solid balance sheet and fundamentals (12 results) that spotlights companies with sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com