
Brazil Export Stocks Retail Investors Are Watching After Flavio Bolsonaro’s First Round Lead
Brazilian large caps tied to exports and foreign currency earnings have suddenly moved from background noise to center stage as Flávio Bolsonaro’s first round lead resets expectations for fiscal reform, interest rates, and the Brazilian real. That mix can reshape which stocks gain and which lag. This article walks through three value-focused Brazil exporters that are closely exposed to this political jolt and explains why their stories matter for your portfolio decisions now.
The exporters covered below are only a first pass, and the full screen surfaced 7 more large-cap Brazilian players with equally compelling FX and commodity stories that are not discussed here. If you want to identify and analyze the highest conviction ideas in this theme, head straight into the Brazil Large-Cap Value Exporters and FX Beneficiaries screener.
Suzano (BOVESPA:SUZB3)
Overview: Suzano is a Brazilian pulp and paper heavyweight that sells bulk cellulose and paper products to customers in Brazil and global markets.
Operations: Suzano generates about R$36.0b from pulp and R$11.8b from paper, with exports linking strongly to foreign currency demand.
Market Cap: R$54.7b
For this Brazil Large-Cap Value Exporters and FX Beneficiaries theme, Suzano gives you a classic exporter where pulp pricing, global demand and currency swings intersect with hard assets inside Brazil.
"While Chinese pulp buyers are increasing hardwood imports and tighter recycled fiber rules along with rising wood chip costs in Asia support higher local production costs, new integrated capacities and verticalization in China could still limit long term pulp price upside and keep Suzano’s pulp EBITDA margins under pressure."
What happens if a single pressure point in Suzano’s export chain tilts in its favor will matter a lot for future margins.
If that margin squeeze is only part of the picture, the full narrative for Suzano shows where currency, capacity shifts and capital allocation could be quietly reshaping Suzano’s trajectory.
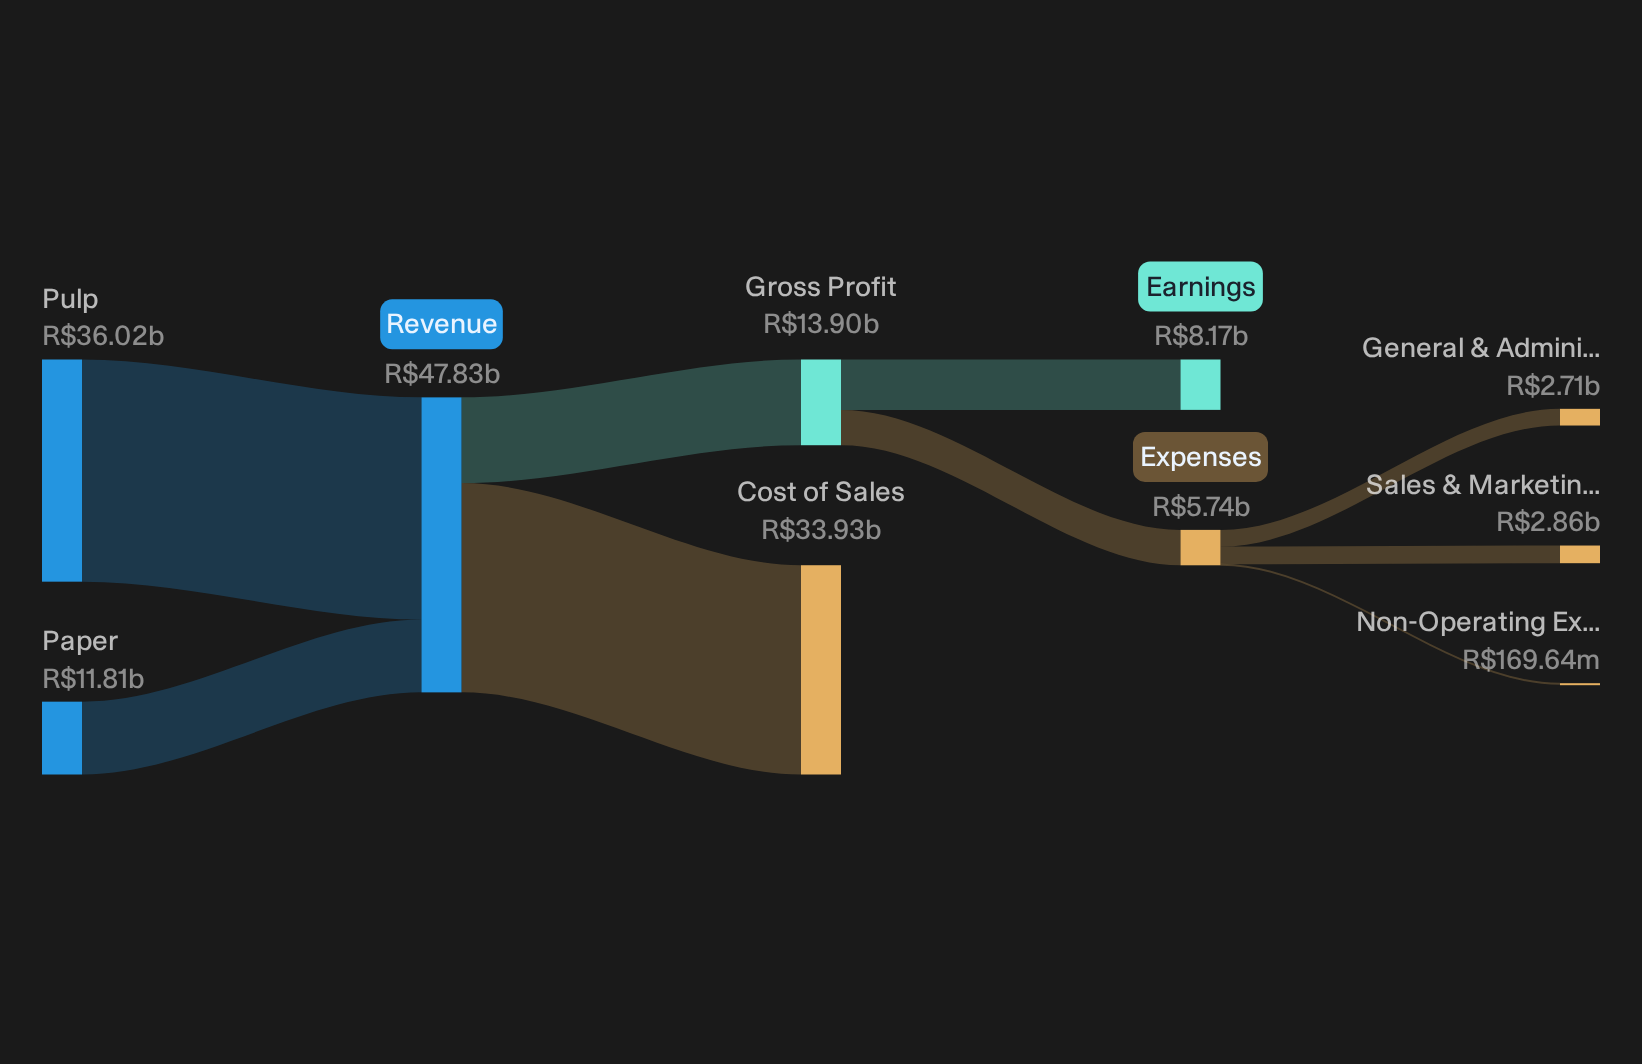
Vale (BOVESPA:VALE3)
Overview: Vale is a Brazilian mining giant that supplies iron ore, nickel and other metals to global industrial customers, earning substantial foreign currency revenue.
Operations: Vale generates about R$167.0b from Iron Ore Solutions and R$51.1b from Base Metals Valley, reflecting a heavily diversified mining portfolio.
Market Cap: R$306.8b
For a screener built around large Brazilian exporters with value credentials, Vale brings sheer scale in iron ore and base metals, plus deep exposure to global demand cycles and foreign currency cash flows as Brazil’s risk premium and funding backdrop shift.
"Although Vale is cutting all in cost guidance in copper and nickel and bringing forward the low capital intensity Bacaba copper project, any delay or underperformance across the wider Carajás copper program that targets about 700 kt per year by 2035 could leave earnings more exposed to iron ore cycles and limit the expected support to group EBITDA and net margins."
Changes in a single cost and mix lever within Vale’s metals portfolio, whether stronger or weaker than expected, could reshape margin resilience.
That earnings mix question is where things get interesting, and the full narrative for Vale shows how Vale’s copper ambitions, capital choices and FX exposure could be quietly decoupling from iron ore cycles.

BrasilAgro - Companhia Brasileira de Propriedades Agrícolas (BOVESPA:AGRO3)
Overview: BrasilAgro is an agricultural land owner and operator that grows exportable crops and raises cattle across Brazil, Paraguay, and Bolivia.
Operations: BrasilAgro generates about R$549 million from grains, R$197 million from sugarcane, R$95 million from cotton, and R$39 million from cattle, mostly in Brazil.
Market Cap: R$1.8 billion
For a screen built around Brazil large-cap exporters, BrasilAgro brings something different: direct leverage to global crop prices and embedded land optionality tied to the real.
"BrasilAgro's low leverage, strong balance sheet, and counter-cyclical capital allocation strategy position it to act aggressively on distressed asset opportunities and sector consolidation as financial stress rises among weaker peers, setting the stage for outsized long-term earnings growth as others retrench."
What happens if one key assumption about how quickly those new hectares turn into high margin production proves either too cautious or too optimistic will be crucial.
That timing question on new hectares is exactly what the full narrative for BrasilAgro - Companhia Brasileira de Propriedades Agrícolas unpacks, including where capital discipline could quietly accelerate BrasilAgro’s next leg of value creation.

Seeking Fresh Alternatives Before Others
Markets move fast. Breakout themes get spotted, momentum names start flying and under the radar stories get caught by the crowd. Scan fresh ideas while it matters and get in early.
- Target steady cash generators and stress test your downside with a curated list of solid balance sheet and fundamentals (207 results) that highlights businesses built to handle tougher conditions.
- Ride potential metal momentum by scanning a focused 36 elite gold producer stocks that zeroes in on producers with scale, reserves and leverage to bullion moves.
- Jump on early infrastructure trends with a hand picked 39 power grid technology and infrastructure stocks tuned to companies wired into long term electricity demand and grid upgrades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com