
Delta Air Lines (DAL), Why Is It Back In The Spotlight?
Delta Air Lines (DAL) has reaffirmed its shareholder payout, with the board declaring a quarterly dividend of US$0.215 per share ahead of an early November payment date.
At a share price of US$83.08, Delta Air Lines has seen a modest pullback in the past week and quarter, with the share price declining 1.2% over one day and 6.3% over three months. This comes even though the year-to-date share price return is 20.3% and the 1-year total shareholder return is 44.2%, pointing to momentum that has cooled recently after a strong longer-term run supported by dividend payments and events such as its recent investor conference appearance.
Scan beyond Delta Air Lines and see how other potential breakout candidates with resilient fundamentals stack up in the 27 high quality undervalued stocks.
After a sharp 1-year run and a recent pullback, Delta Air Lines now offers a higher trailing yield and a lower entry price. Does the current valuation still skew the risk reward toward buyers, or is the easy money gone?
Most Popular Narrative: 31% Overvalued
Compared with the last close at $83.08, the most followed narrative on Delta Air Lines pegs fair value much lower at $63.21, framing the current share price as rich and vulnerable to disappointments.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line, yet there's a snag: The legacy carrier comes from all-time high profitability. Hence, the risk distribution is skewed to the downside as long as there's no final and reliable re-opening of the Strait of Hormuz. That is why I stick to my valuation even in the face of shares trading some 38 per cent in excess of my calculations, because the latter is just that: excess. A current PE at some 14.5 and a forward PE at around 12 are simply too rich against this macro and geoeconomic backdrop. Delta would have to increase its current profit margins considerably to justify these multiples, which the author considers a very difficult task.
See why 23 investors see Delta Air Lines as 31% overvalued.
Result: Fair Value of $63.21 (OVERVALUED)
Still, Delta Air Lines faces catalysts that could reverse this overvaluation story, including any meaningful shift in travel demand or a quicker reset in investor risk appetite.
Find out about the key risks to this Delta Air Lines narrative.
Another View: SWS DCF Puts Delta Air Lines In A Different Light
The narrative fair value of $63.21 presents Delta Air Lines as 31% overvalued, yet our DCF model points in the opposite direction. Within that framework, DAL at $83.08 is described as trading at roughly a 60.5% discount to an estimated future cash flow value of $210.16, which raises a simple question: Is the market mispricing long term cash generation, or are these inputs too optimistic for such a cyclical carrier?
Look into how the SWS DCF model arrives at its fair value.
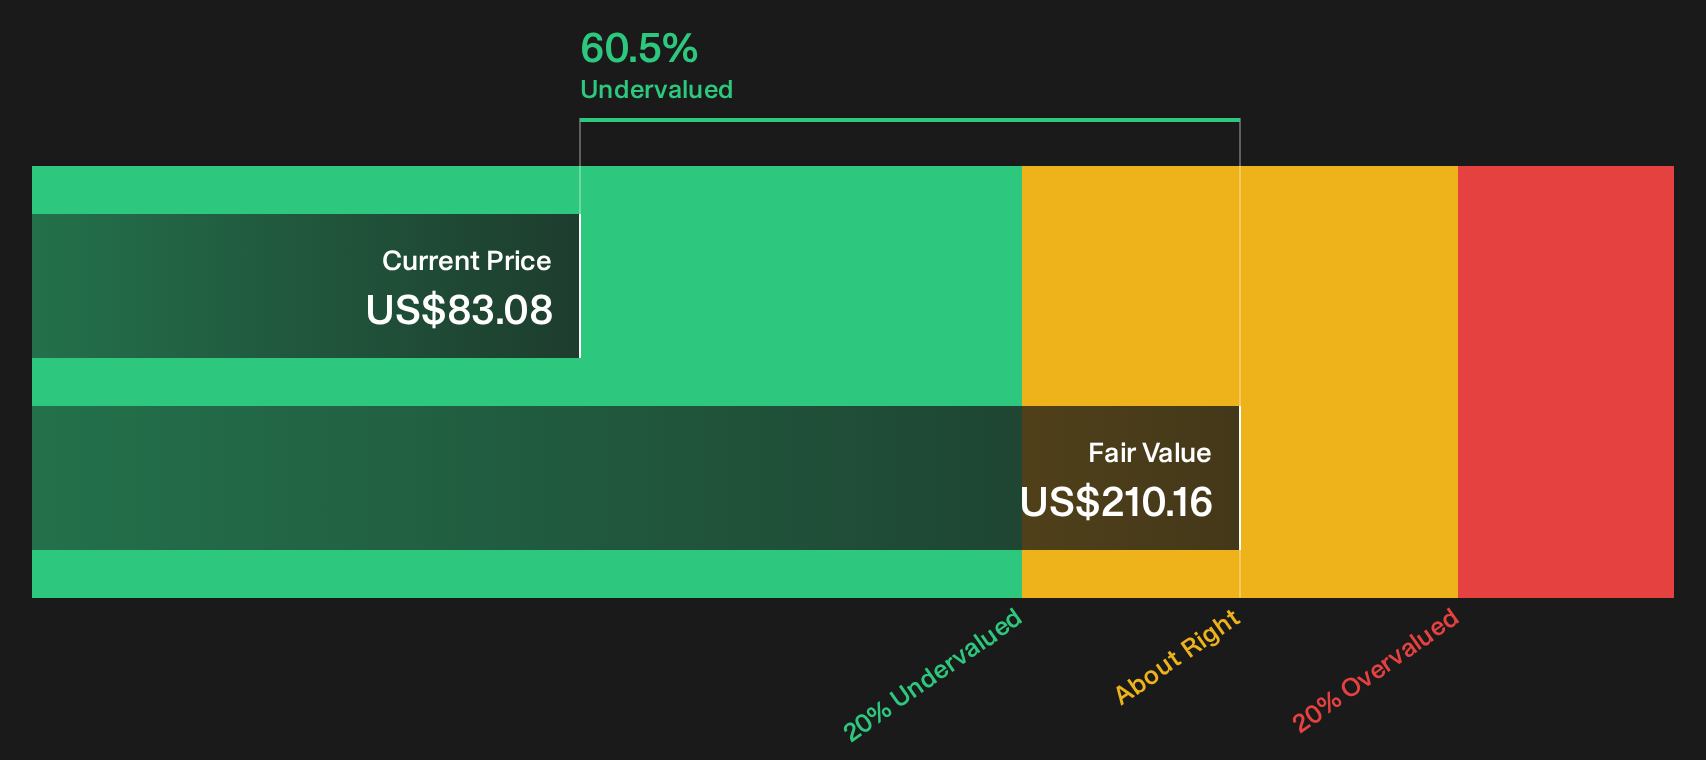
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Delta Air Lines can be confusing. Consider reviewing the underlying numbers yourself, then weigh up the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Delta Air Lines?
Do not stop with Delta Air Lines. Broaden your watchlist now and use a focused stock search to surface opportunities you might regret missing later.
- Target potential turnaround stories by scanning 9 elite penny stocks with strong financials that already show stronger balance sheets and cleaner financials than typical micro caps.
- Zero in on quality at a discount with the 19 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Prioritize resilience by reviewing a 31 resilient stocks with low risk scores that filters for sturdier financial profiles when conditions become more demanding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com