
nLIGHT (LASR) Dropped, So What Is Driving Attention Now?
nLIGHT (LASR) has drawn fresh attention after a recent share price pullback, with the stock down 1.4% over the past month and 33.1% over the past 3 months.
Recent trading has been choppy for nLIGHT, with the share price down 2.66% over the last session and declining 33.1% over the past 3 months. This comes even though the year to date share price return is positive and the 1 year and 3 year total shareholder returns of 28.33% and over 3x suggest longer term momentum has been much stronger than the latest pullback implies.
Scan beyond nLIGHT and spot other laser and advanced tech plays that have been hand-picked in our 91 AI infrastructure stocks, which is shaping the next leg of this trend.
nLIGHT now trades at about half the average analyst price target, even as intrinsic value models lean the other way. Where does a reasonable fair value range actually land once those views are stacked side by side?
Most Popular Narrative: 56% Undervalued
Against a last close of $39.50 for nLIGHT, the most followed narrative pegs fair value at about $90.71. This frames the recent pullback as only one piece of a much bigger story that leans heavily on defense lasers and future profitability.
The rapid growth and expanding pipeline in aerospace and defense, particularly around high-power laser solutions (e.g., HELSI-2 program, DE M-SHORAD, Golden Dome initiative, and increased directed energy orders internationally), positions nLIGHT to benefit from rising global defense spending and modernization, supporting multi-year revenue growth.
Increasing adoption of advanced laser technologies for automation, smart manufacturing, and additive manufacturing (especially in EV, clean energy, and microfabrication segments) supports long-term demand for nLIGHT's differentiated products and provides a runway for top-line expansion.
See why 15 investors see nLIGHT as 56% undervalued.
Result: Fair Value of $90.71 (UNDERVALUED)
Still, nLIGHT leans heavily on aerospace and defense spending. Any delays or downsizing of key laser weapon programs could quickly challenge this upbeat narrative.
Find out about the key risks to this nLIGHT narrative.
Another View: nLIGHT Looks Expensive On Sales
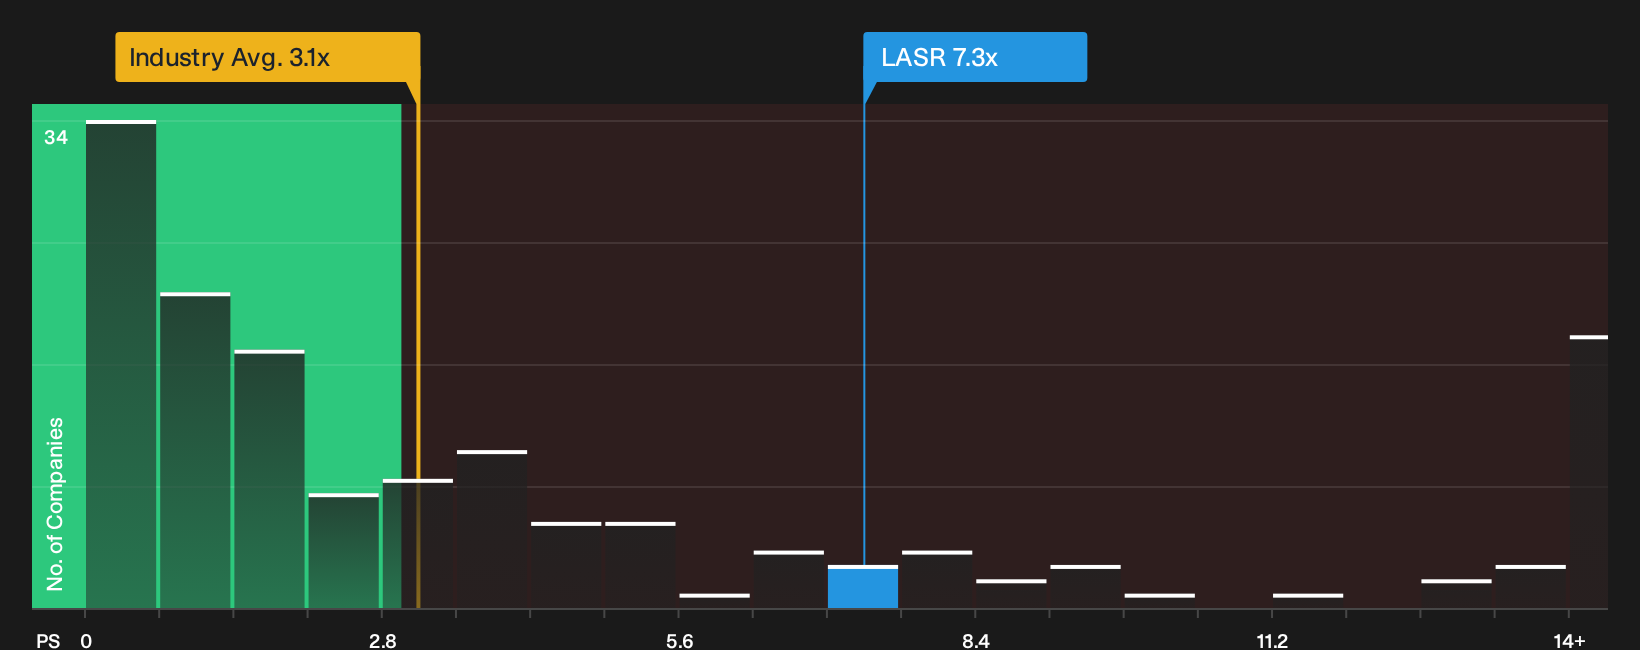
That 56% undervalued story for nLIGHT runs into a very different read once sales multiples enter the picture. The stock trades on a P/S of 7.3x, compared with a fair ratio of 1.8x, the US Electronic industry at 3.1x, and peers at 2.7x. That is a rich premium. Is this a margin of safety or a margin of error?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around nLIGHT can feel confusing, so move quickly from headline stories to hard numbers and weigh both the downside and upside using our 2 key rewards and 3 important warning signs.
Looking for more nLIGHT investment ideas?
If nLIGHT has caught your eye, do not stop here. Use the Simply Wall Street Screener to compare fresh opportunities and build a stronger watchlist today.
- Target potential mispricing by scanning a curated set of 27 high quality undervalued stocks that combine robust fundamentals with attractive valuations.
- Prioritize resilience and sleep better at night by focusing on a 31 resilient stocks with low risk scores designed to highlight businesses with steadier profiles.
- Hunt for tomorrow's stories early by checking a 19 high quality undiscovered gems that flags quality companies still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com