
Asian Growth Companies With Strong Insider Ownership October 2026
As global markets navigate a landscape marked by fluctuating oil prices and persistent inflation concerns, Asia's economic growth continues to capture investor interest. In this environment, growth companies with high insider ownership may offer unique advantages, as strong insider stakes can align management interests with those of shareholders, potentially fostering long-term value creation.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
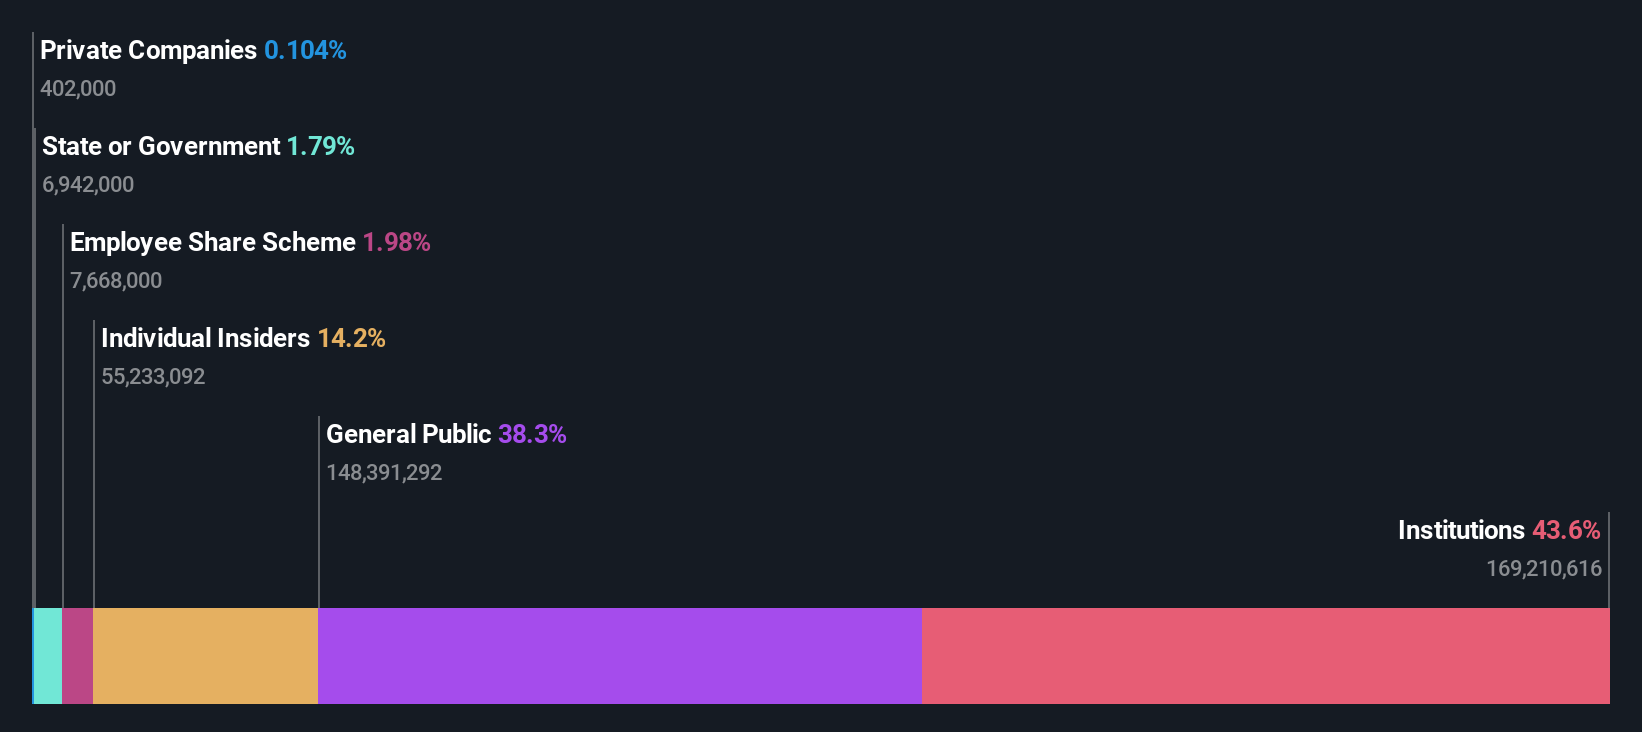
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| HUMAN MADE (TSE:456A) | 29.1% | 29.5% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
Underneath we present a selection of stocks filtered out by our screen.
Guangzhou Tinci Materials Technology (SZSE:002709)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Guangzhou Tinci Materials Technology Co., Ltd. operates in the research, development, production, and sale of fine chemical materials both in China and internationally, with a market cap of CN¥63.34 billion.
Operations: The company generates revenue of CN¥24.33 billion from its fine chemical industry segment.
Insider Ownership: 38.4%
Revenue Growth Forecast: 25.5% p.a.
Guangzhou Tinci Materials Technology is experiencing substantial growth, with revenue forecasted to increase by 25.5% annually, surpassing the CN market's growth rate. Despite trading slightly below its fair value estimate, it offers good relative value compared to peers. Earnings surged significantly last year and are expected to continue growing at over 20% annually for the next three years. Recent earnings showed robust performance with sales reaching CNY 14.71 billion and net income of CNY 2.86 billion for H1 2026.
- Navigate through the intricacies of Guangzhou Tinci Materials Technology with our comprehensive analyst estimates report here.
- Our expertly prepared valuation report Guangzhou Tinci Materials Technology implies its share price may be lower than expected.

Guangzhou Great Power Energy and Technology (SZSE:300438)
Simply Wall St Growth Rating: ★★★★★★
Overview: Guangzhou Great Power Energy and Technology Co., Ltd specializes in the research, development, production, and sale of battery products both in China and internationally, with a market cap of CN¥24.70 billion.
Operations: The company's revenue primarily comes from its electronic component manufacturing segment, which generated CN¥18.62 billion.
Insider Ownership: 33.3%
Revenue Growth Forecast: 39.6% p.a.
Guangzhou Great Power Energy and Technology is poised for significant growth, with revenue expected to rise by 39.6% annually, outpacing the CN market. The company's earnings are forecasted to grow at 45.1% per year, indicating strong potential relative to peers. Recent results highlight a turnaround with H1 2026 sales of CNY 10.98 billion and net income of CNY 816.44 million from a previous loss, while trading well below its fair value estimate suggests good investment potential.
- Dive into the specifics of Guangzhou Great Power Energy and Technology here with our thorough growth forecast report.
- Our comprehensive valuation report raises the possibility that Guangzhou Great Power Energy and Technology is priced lower than what may be justified by its financials.
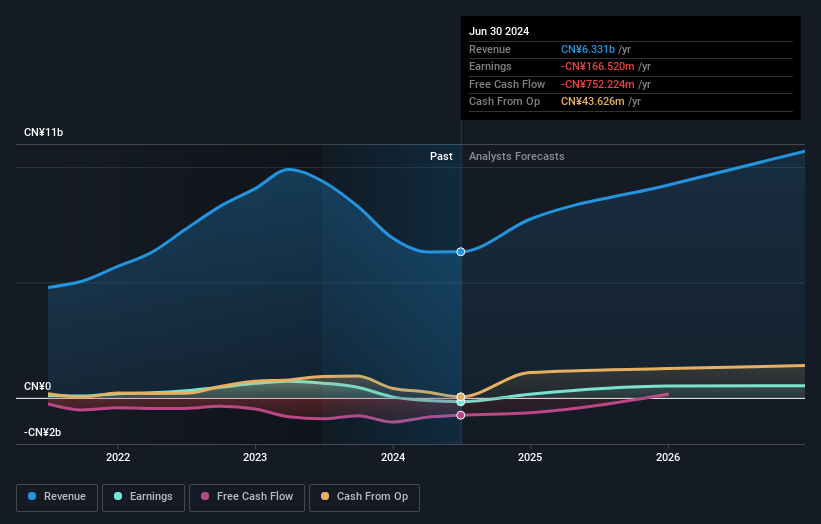
Silergy (TWSE:6415)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Silergy Corp. is involved in the design, manufacture, and sale of integrated circuit products and related technical services both in China and internationally, with a market cap of NT$171.88 billion.
Operations: Revenue from the semiconductors segment amounts to NT$21.02 billion.
Insider Ownership: 12.9%
Revenue Growth Forecast: 23% p.a.
Silergy Corp. demonstrates strong growth potential, with earnings projected to rise by 37.33% annually, surpassing the Taiwan market's average. Recent financial results show a significant increase in net income to TWD 1,571 million for Q2 2026, compared to TWD 629.99 million the previous year. Despite high share price volatility and trading at a discount to estimated fair value, the company benefits from substantial insider ownership and robust revenue growth forecasts of 23% per year.
- Click to explore a detailed breakdown of our findings in Silergy's earnings growth report.
- In light of our recent valuation report, it seems possible that Silergy is trading behind its estimated value.
Turning Ideas Into Actions
- Click here to access our complete index of 497 Fast Growing Asian Companies With High Insider Ownership.
- Seeking Other Investments? Trump's oil boom is here — pipelines are primed to profit. Discover the 81 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com