
Learn Why The Bull Case For Seagate Stock Could Change Following HDD Capacity Expansion
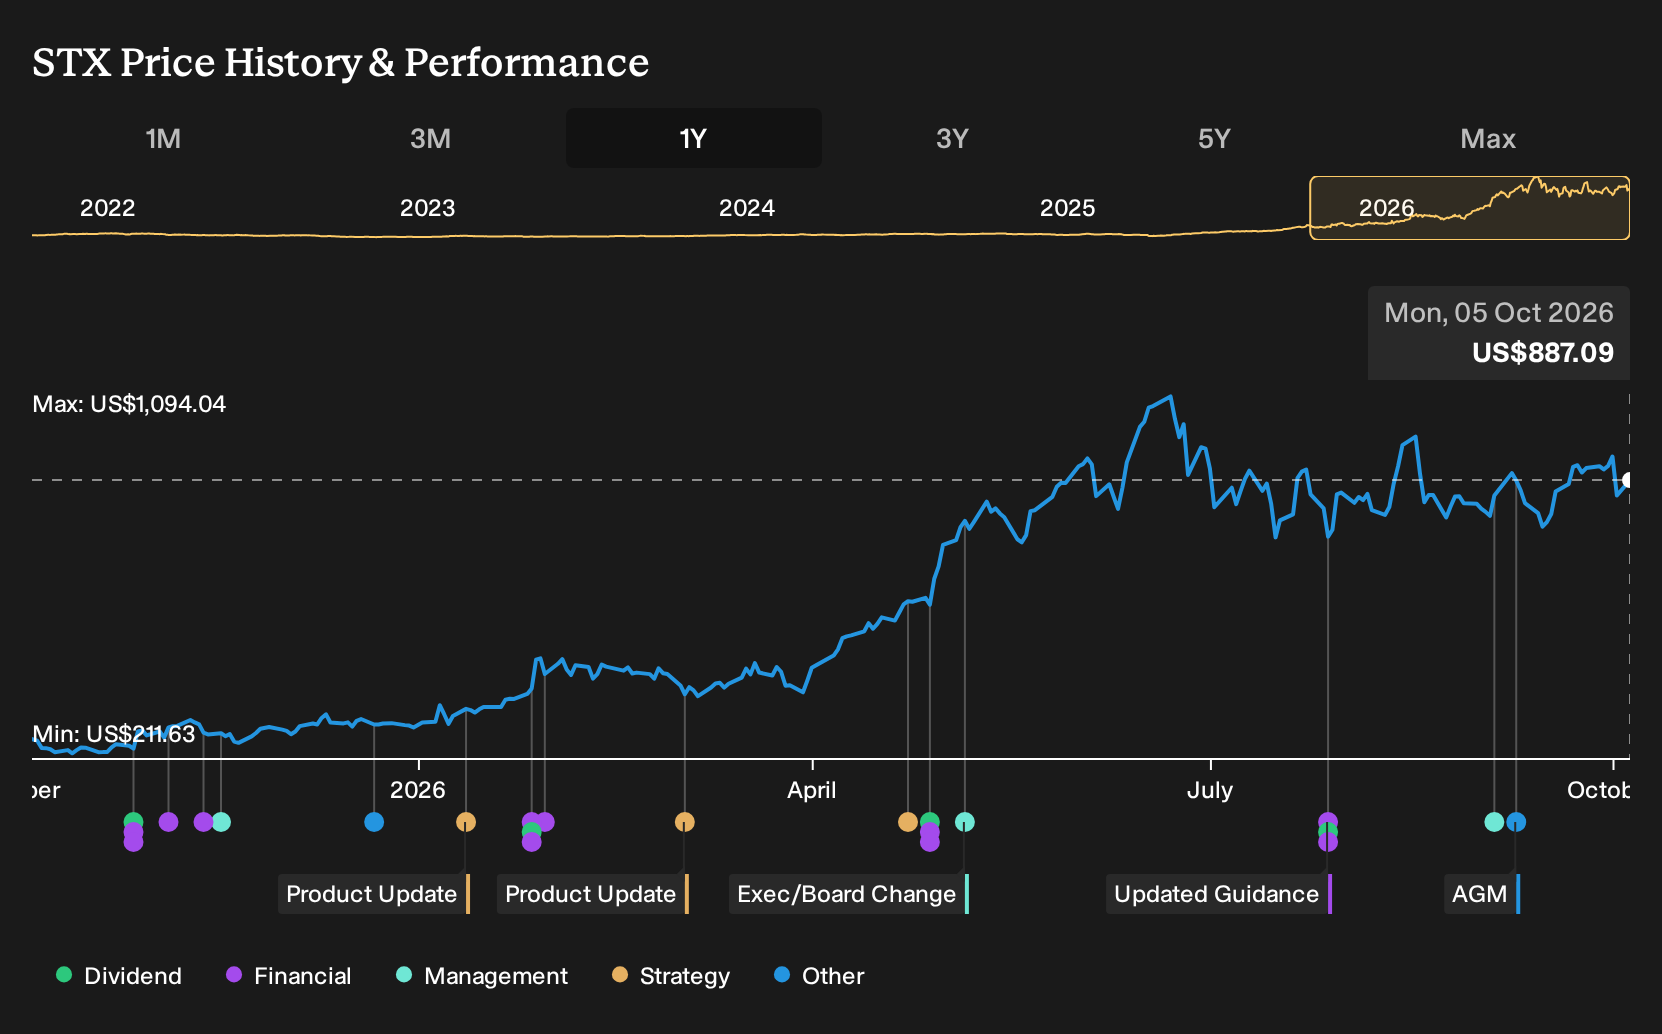
- Seagate Technology Holdings recently saw investor focus swing back after a sharp reaction to Toshiba's plan to double AI data center HDD capacity by fiscal 2027. This raised fresh questions about future pricing power in a market that had been supported by tight supply.
- The Toshiba capacity plan directly tests how resilient Seagate's HDD pricing and contract structure might be when a major rival signals a multi year supply expansion aimed at AI storage workloads.
- We will now explore how Seagate Technology Holdings' investment narrative could be affected by Toshiba's planned HDD capacity increase for AI data centers.
Scan how Seagate Technology Holdings fits into the broader AI storage build out by reviewing hand picked 91 AI infrastructure stocks moving with the data center upgrade cycle.
Seagate Technology Holdings Investment Narrative Recap
For you to stay interested in Seagate Technology Holdings, you need to believe that AI heavy data center storage remains the core engine and that HAMR based Mozaic drives and long term build to order contracts keep that engine running. Toshiba’s capacity plans challenge the tight supply story, but Seagate’s contracts through 2028 can cushion near term pricing pressure.
The key near term swing factor is how price per exabyte holds up as Mozaic penetration and AI demand evolve. The biggest risk right now is that elevated expectations collide with any wobble in data center orders or HDD pricing, especially with a volatile share price and high debt already on investor radar.
The most relevant reference point for this Toshiba headline is Seagate’s own commentary that industry supply discipline and its pricing actions were reflected in an 11% year over year increase in price per exabyte, with implied growth of around 20% in the September 2026 quarter. That backdrop helps explain why any threat to discipline sparks such a sharp share price reaction.
If you think Seagate Technology Holdings can keep those pricing gains resilient even as a rival talks about doubling capacity, then the earlier catalysts still matter. HAMR based Mozaic drives at about 40% of nearline exabyte shipments, long term allocation of most nearline capacity through 2028, and strong recent free cash flow all point you back to the same question: Does pricing power bend or break as new supply arrives?
Seagate Technology Holdings' narrative projects US$31.1b revenue and US$16.1b earnings by 2029. This projection assumes 36.6% yearly revenue growth and an earnings increase of about US$12.9b from US$3.2b today.
Uncover why Seagate Technology Holdings' fair value indicates a 27% potential upside to its current price, which could narrow quickly if sentiment resets.
Exploring Other Perspectives
One alternate angle on Seagate Technology Holdings is pure optimism that tight supply and firm pricing hold. The most bullish analysts were penciling in about US$36.5b of revenue and US$18.8b of earnings by 2029, versus US$31.1b and US$16.1b in the consensus case. Toshiba’s expansion plan may push those storylines to evolve, so you are wise to compare several viewpoints before deciding what feels realistic.
Explore 4 other Seagate Technology Holdings fair value estimates, including one that suggests there could be as much as 74% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Seagate Technology Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Seagate Technology Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seagate Technology Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Seagate Technology Holdings?
Once you have formed a view on Seagate Technology Holdings, it often helps to compare that thesis with a few completely different opportunities filtered by quality, risk, or income potential.
- If you want potential upside with strict financial filters, scan a curated set of 19 high quality undiscovered gems that pair strong fundamentals with under-the-radar profiles.
- For investors who care most about resilience, stress test your risk tolerance against a group of 31 resilient stocks with low risk scores that score well on stability metrics.
- If balance sheet strength is your starting point, build a shortlist from a list of solid balance sheet and fundamentals (25 results) and use it to cross check how each candidate stacks up before you commit fresh capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com