
Top 3 Australian Value Stocks To Watch In October 2026
Asian stocks have recently rallied as expectations for near term US rate hikes have eased, putting fresh attention on cash generating Australian businesses that might have been overlooked during the rate scare. When sentiment cools, pricing can lag behind what a company’s cash flows imply it is worth. That gap is where value hunters focus. This article walks through three Australian stocks that our cash flow screen flags as potentially mispriced.
The three stocks in this piece are just a starting sample, and the full screen surfaced 6 more Australian companies with cash flow stories that look equally compelling on Simply Wall St’s DCF work.
Head straight into the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze the highest conviction ideas that match your own value checklist.
Qualitas (ASX:QAL)
Overview: Qualitas is an Australian alternative real estate investment manager that focuses on income generating private credit and equity strategies for property.
Operations: Most revenue comes from A$15 million in funds management and direct lending activities, primarily tied to Australian real estate markets.
Market Cap: A$663 million
Qualitas fits this cash flow focused screen because its real estate private credit arm is built around secured loans that generate contractual interest streams. This structure can help anchor discounted cash flow valuations when sentiment toward property risk swings around.
Banks have continued to move away from commercial property lending since 2009, and private credit’s share of Australian real estate debt has grown from 15% in 2019 to 26% today, with forecasts of 35% by 2030.
The real question is how that growing private credit gap feeds through to Qualitas’ fee levels and margins if one unseen pressure shifts.
If that pressure is building quietly, read the full narrative for Qualitas to see how Qualitas could benefit if bank retreat and pricing power accelerate.
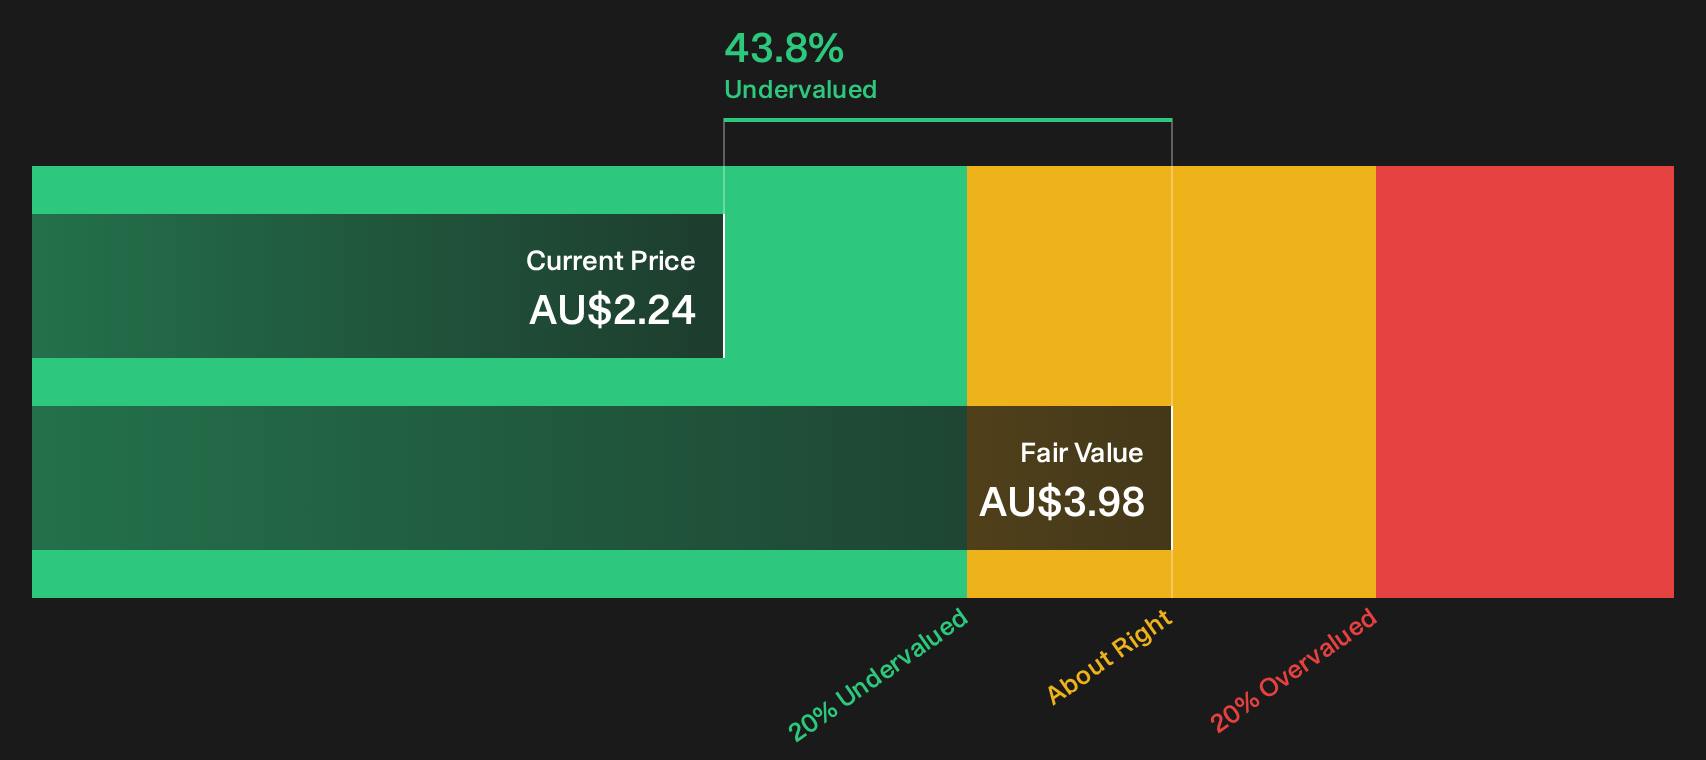
MotorCycle Holdings (ASX:MTO)
Overview: MotorCycle Holdings runs a large network of motorcycle dealerships across Australia and New Zealand, selling bikes, accessories, servicing and protection plans that create recurring after-sales cash flows.
Operations: The group generates about A$560 million from Motorcycle Retailing and A$272 million from Motorcycle and Accessories Wholesaling, almost entirely in Australia.
Market Cap: A$186 million
MotorCycle Holdings slots into this cash flow focused screen because its dealership network does not just sell motorcycles once. It keeps riders coming back for servicing, parts and protection plans that can support more visible cash flows over time.
Market share in new vehicles is now close to 20% with record half year unit sales in both new and used bikes. This positions the group to capture a larger share of category spend as demand channels through its network, supporting revenue and gross profit.
What really matters for value investors is how one less obvious shift in those after-sales economics ends up moving long term margins.
Those long term economics are where MotorCycle Holdings really gets interesting. Read the full narrative for MotorCycle Holdings to see how recurring riders’ spend could accelerate or stall.

NobleOak Life (ASX:NOL)
Overview: NobleOak Life is an Australian insurer providing life, income protection, TPD, trauma and related cover that generates recurring premium cash flows.
Operations: NobleOak Life earned about A$399 million from Strategic Partnerships, A$106 million from Direct channels and A$15 million from Genus, entirely in Australia.
Market Cap: A$121 million
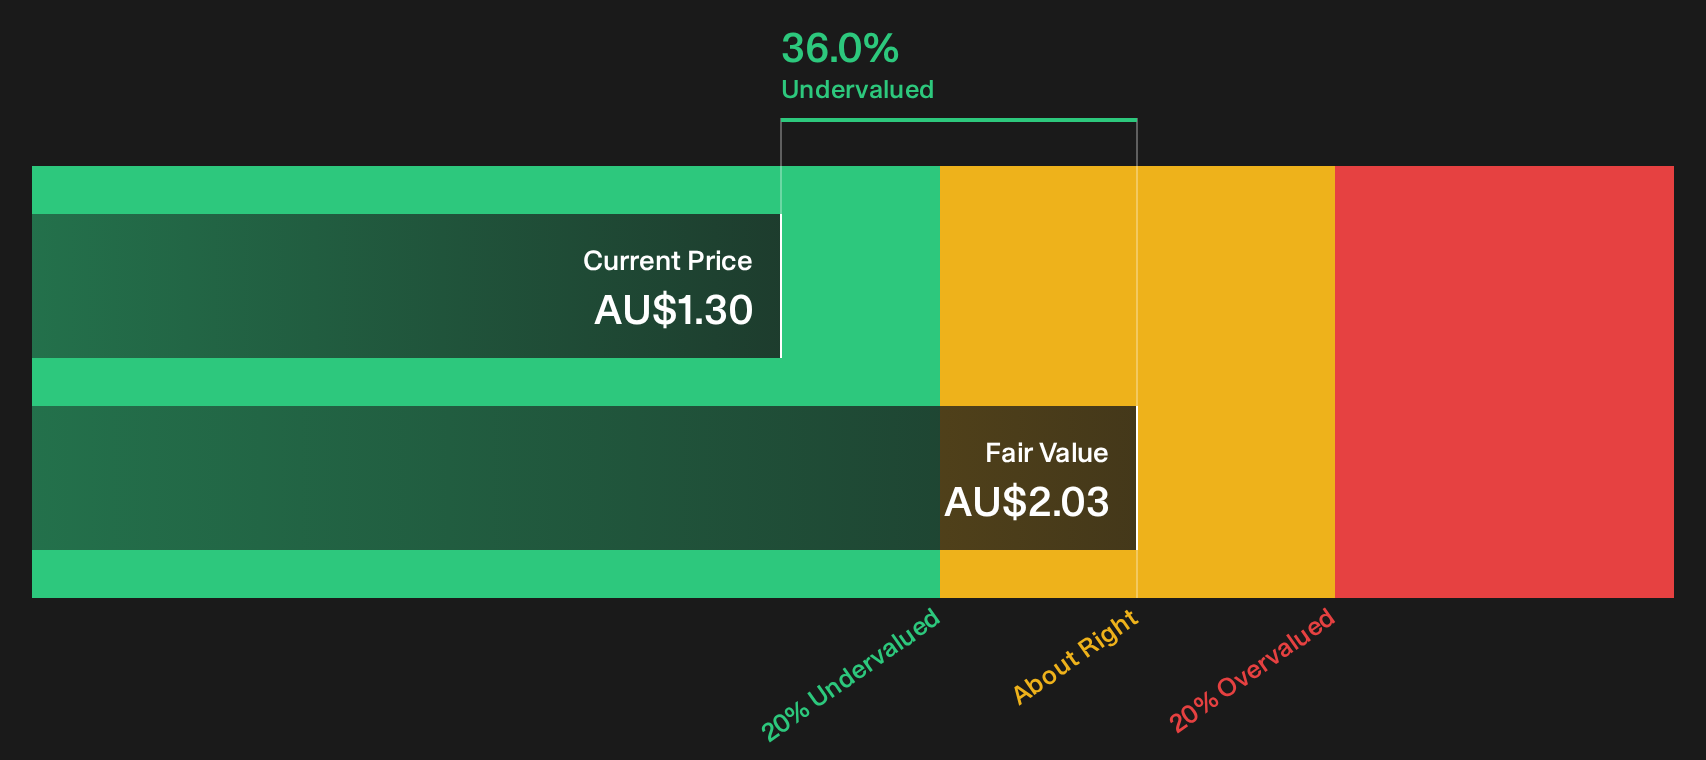
NobleOak Life links cleanly to this cash flow focused screen through life insurance policies that feed recurring underwriting and investment income. The stock trades on an 8.6x P/E and at a 36% discount to estimated fair value after reporting A$14.11 million in net income for FY 2026, which makes future margins heavily dependent on how one unseen funding pressure plays out.
That funding pressure could be the hinge for NobleOak Life, so read the analysis report for NobleOak Life to see what the current valuation might be missing.
Seeking Alternatives Before Others Catch On
Fresh ideas can start to break out while many investors stay focused on yesterday’s stories. Consider taking steps before momentum moves beyond your radar. Take time to review your options.
- Identify cash-rich businesses before they reach the mainstream by scanning the list of solid balance sheet and fundamentals (12 results), which highlights companies that have already passed tight financial health filters.
- Explore potential income opportunities by checking the 3 dividend fortresses, designed for investors who want yields supported by balance sheet strength.
- Review future-facing infrastructure themes by tracking the 39 power grid technology and infrastructure stocks, which focuses on grid upgrades, electrification trends and related capital projects.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com