
3 European Stocks That May Be Trading Below Estimated Value In October 2026
In October 2026, European equity markets have experienced volatility, influenced by elevated oil prices and rising sovereign bond yields that have tempered investor risk appetite. As stronger-than-expected inflation data adds pressure on monetary policy to remain restrictive, identifying stocks that may be trading below their estimated value becomes increasingly important for investors seeking opportunities amidst these challenging conditions.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| XTB (WSE:XTB) | PLN134.80 | PLN269.03 | 49.9% |
| Valmet Oyj (HLSE:VALMT) | €27.46 | €52.69 | 47.9% |
| Prologue (ENXTPA:ALPRG) | €0.284 | €0.56 | 49.5% |
| PORR (WBAG:POS) | €31.05 | €61.02 | 49.1% |
| Orthex Oyj (HLSE:ORTHEX) | €4.41 | €8.78 | 49.8% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €12.13 | €22.99 | 47.2% |
| Grupa Pracuj (WSE:GPP) | PLN55.80 | PLN110.49 | 49.5% |
| Gesco (XTRA:GSC1) | €13.85 | €26.16 | 47.1% |
| DWS Group GmbH KGaA (XTRA:DWS) | €68.45 | €128.15 | 46.6% |
| Apator (WSE:APT) | PLN25.65 | PLN48.69 | 47.3% |
Here's a peek at a few of the choices from the screener.
Aubay Société Anonyme (ENXTPA:AUB)
Overview: Aubay Société Anonyme offers application services across several European countries, including Belgium, Luxembourg, Spain, Portugal, Italy, France, and the United Kingdom, with a market cap of €632.26 million.
Operations: Aubay Société Anonyme generates revenue through its provision of application services across Belgium, Luxembourg, Spain, Portugal, Italy, France, and the United Kingdom.
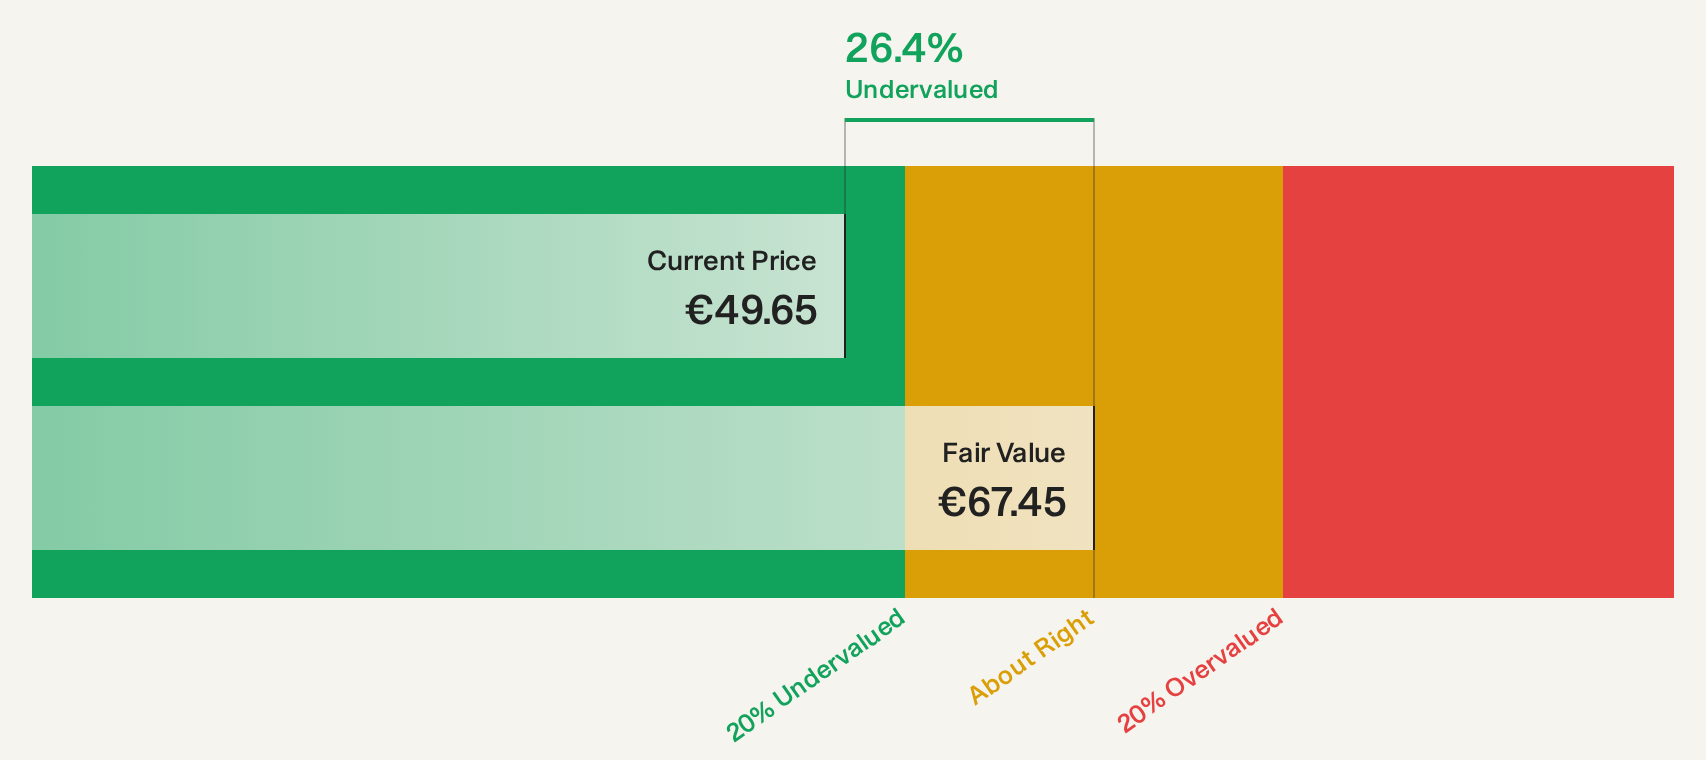
Estimated Discount To Fair Value: 27.7%
Aubay Société Anonyme is trading at €49.65, notably below its estimated future cash flow value of €68.64, suggesting it may be undervalued on this basis. Despite a forecasted earnings growth of 10.45% annually, which lags behind the French market's expected growth, recent results show a strong performance with half-year sales rising to €351.85 million from €269.01 million year-on-year and net income increasing to €17.23 million from €14.02 million previously.
- The analysis detailed in our Aubay Société Anonyme growth report hints at robust future financial performance.
- Delve into the full analysis health report here for a deeper understanding of Aubay Société Anonyme.
IDI (ENXTPA:IDIP)
Overview: IDI is a private equity firm focused on leveraged buyouts, expansion and growth capital, and acquisitions in small to medium-sized companies, with a market cap of €489.45 million.
Operations: IDI's revenue is primarily derived from leveraged buyouts, expansion and growth capital, acquisitions of significant holdings in small to medium-sized listed companies, secondary private equity portfolios, mezzanine financing, senior loans, mergers and acquisitions, development capital, discounted leveraged buyout loans in mature companies and co-investments in pre-IPO financing.
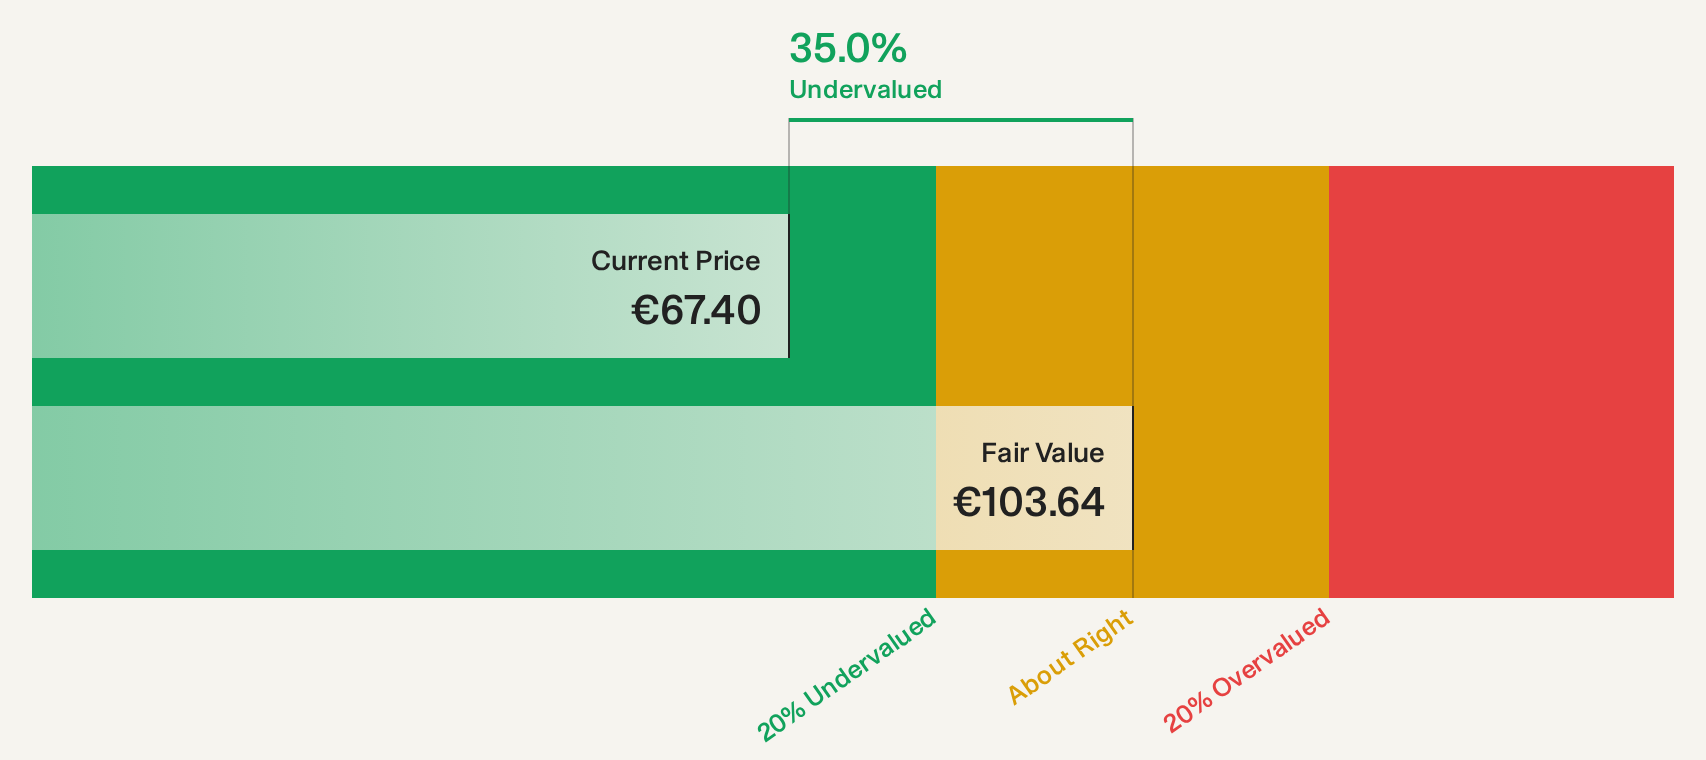
Estimated Discount To Fair Value: 34.4%
IDI is trading at €68.6, significantly below its estimated future cash flow value of €104.64, highlighting potential undervaluation. Despite a 247.9% earnings increase over the past year, revenue is expected to decline by 50.8% annually for the next three years, with earnings also forecasted to decrease by 9% per year. Recent half-year results showed net income rising to €57.1 million from €14.8 million a year ago, despite an unstable dividend track record and projected declines in revenue and earnings growth rates.
- Our comprehensive growth report raises the possibility that IDI is poised for substantial financial growth.
- Navigate through the intricacies of IDI with our comprehensive financial health report here.
PFISTERER Holding (XTRA:PFSE)
Overview: PFISTERER Holding SE specializes in manufacturing and selling cable fittings, insulators for overhead lines, and related components for energy networks and renewable energy generation, with a market cap of €1.19 billion.
Operations: The company's revenue is primarily derived from its High Voltage Cable Accessories segment at €312.89 million, followed by Overhead Lines at €137.51 million, Components at €124.60 million, and Medium Voltage Cable Accessories at €84.68 million.
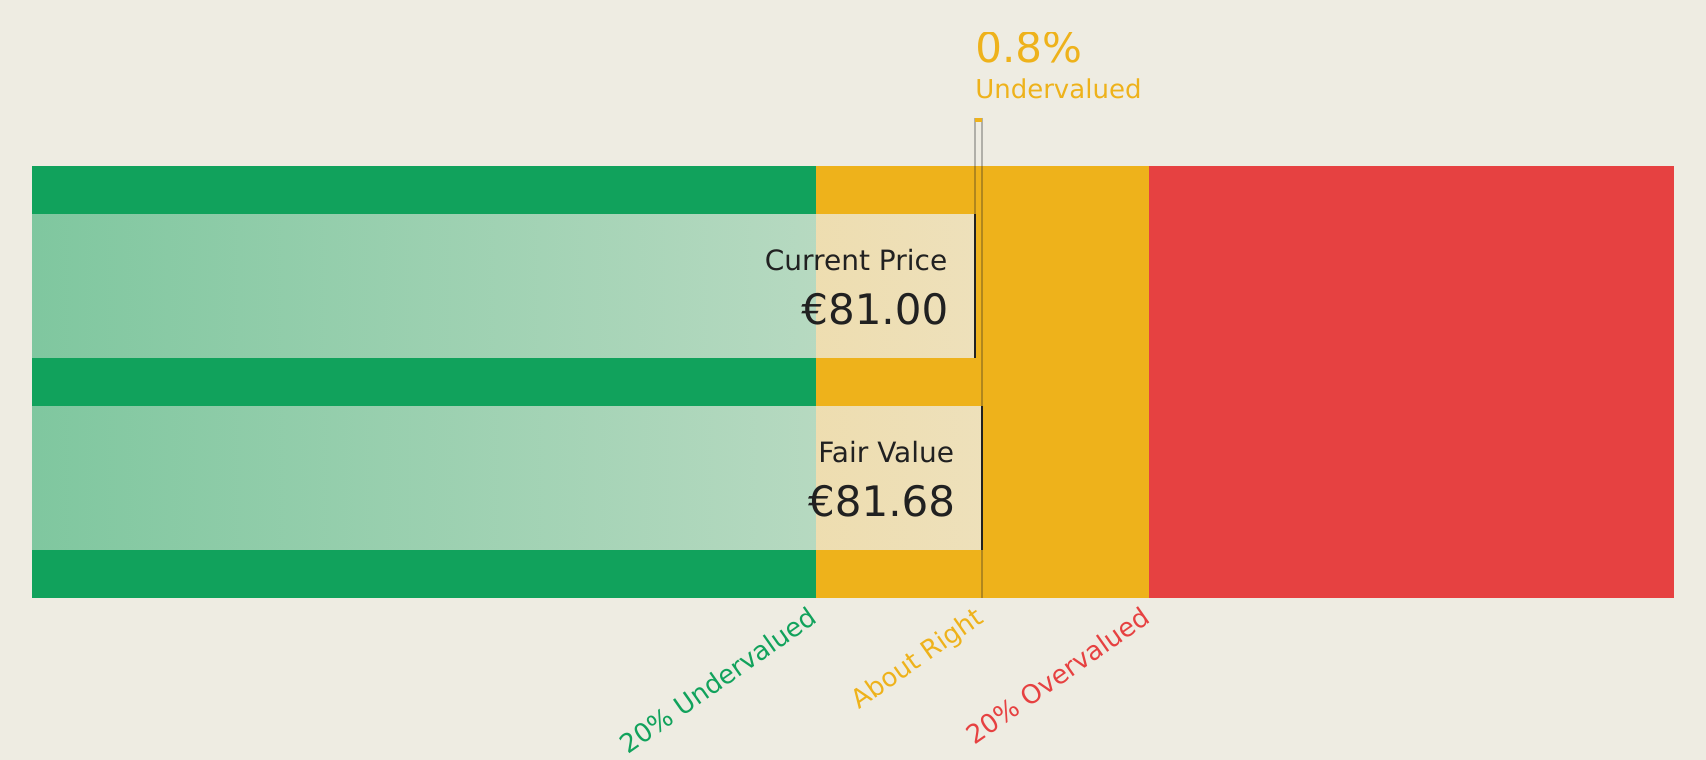
Estimated Discount To Fair Value: 28.6%
PFISTERER Holding SE, trading at €65.25, is undervalued relative to its future cash flow value of €91.34. Recent earnings reports show a rise in net income to €37.94 million from €21.43 million the previous year, with revenue growing faster than the German market at 11.1% annually. The company's strategic expansion in the U.S., investing $2.7 million to boost production capacity, underscores its commitment to capturing high-growth markets and enhancing operational resilience globally.
- In light of our recent growth report, it seems possible that PFISTERER Holding's financial performance will exceed current levels.
- Click to explore a detailed breakdown of our findings in PFISTERER Holding's balance sheet health report.
Summing It All Up
- Unlock our comprehensive list of 56 Undervalued European Stocks Based On Cash Flows by clicking here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com