
Vistra (VST) Urges Regulators To Reject PJM Plan It Calls Discriminatory
- Vistra (NYSE:VST) has urged federal regulators to reject PJM Interconnection's proposed Interim Resource Adequacy Service, arguing it is discriminatory.
- The power producer told regulators the IRAS design would distort capacity market outcomes and unfairly affect certain generators serving PJM.
- Vistra highlighted potential consequences for large data center power contracts, warning the proposal could reshape how long term supply deals are structured.
- Vistra's challenge to PJM's IRAS plan is important, but investors should weigh it alongside the rest of the Vistra story. We have also flagged 2 other big wins for Vistra.
For readers looking to broaden their watchlist with grid-focused operators and related plays, the next stop is 39 power grid technology and infrastructure stocks.
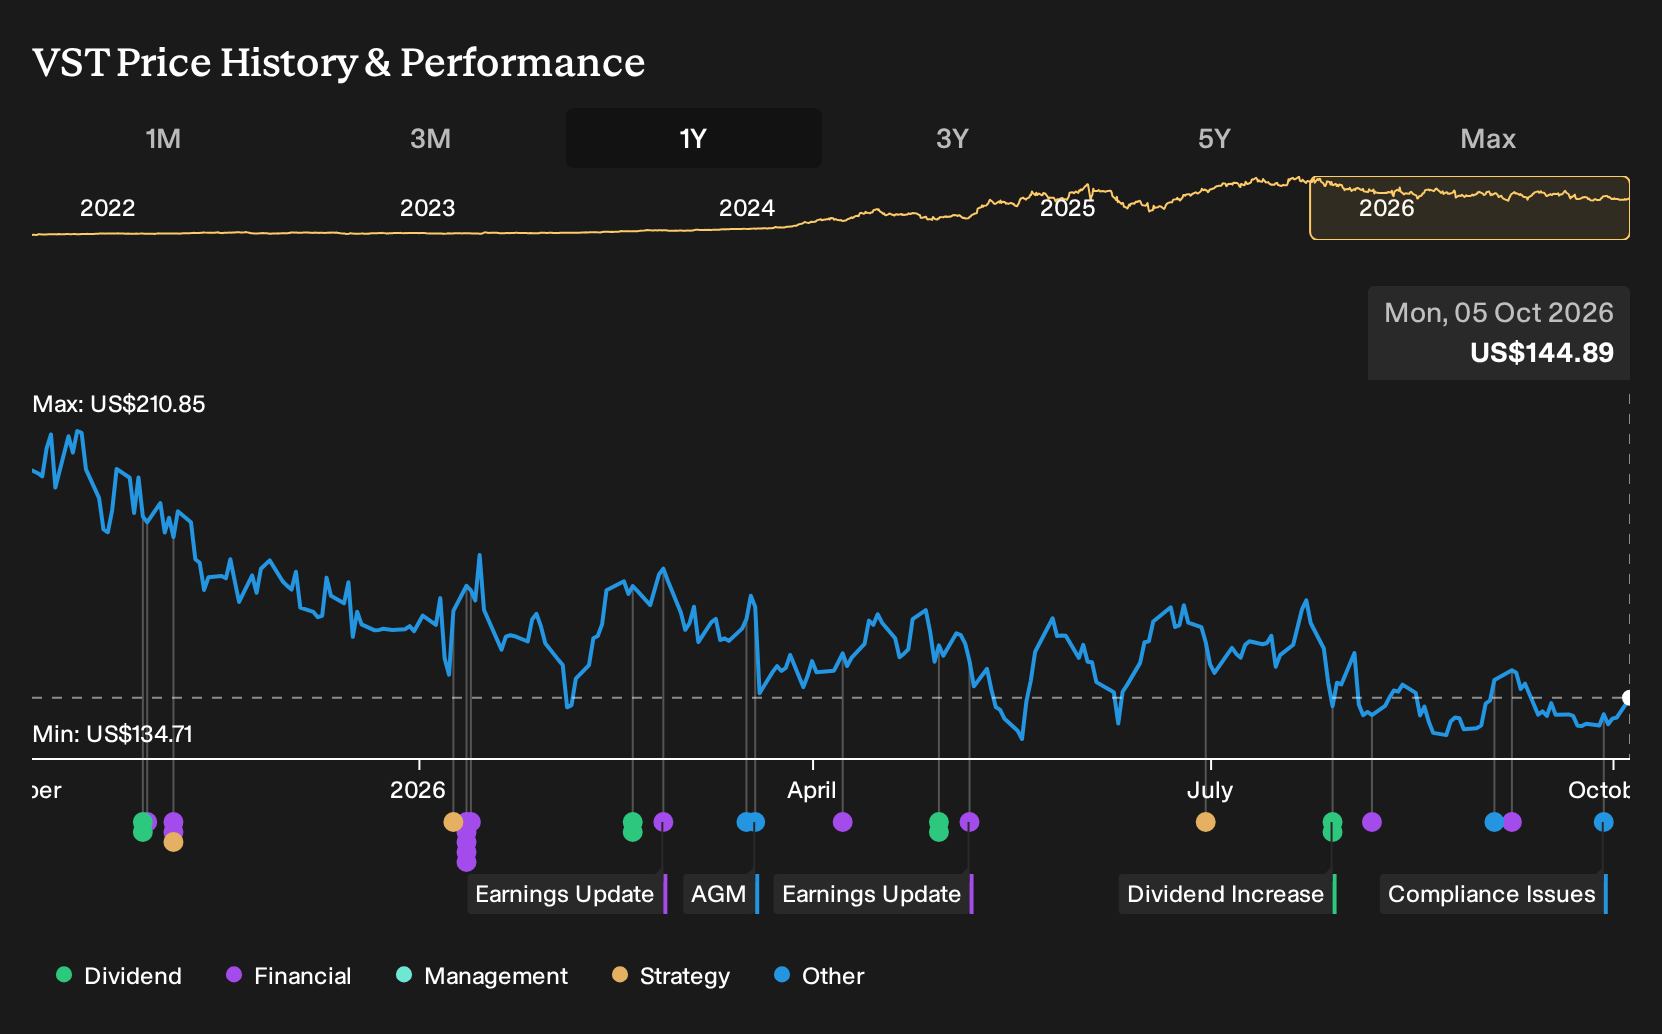
Vistra runs a large integrated retail electricity and power generation platform in the US, which means any shift in PJM's market design can influence how this $47.0b renewable energy player plans and contracts its fleet over time.
See how Vistra's balance sheet measures up.
Why Vistra is fighting PJM on IRAS and what the market might be missing
The Vistra story rests on turning AI driven load in PJM and ERCOT into long dated, contracted cash flows, so any rule change that touches capacity pricing or data center treatment directly matters to that Narrative.
For that to play out, Vistra needs AI and data center driven load growth to translate into contracted volumes and returns on projects like Helix Digital Infrastructure, Cogentrix, nuclear uprates and new gas and solar buildouts...
See how the full story points towards a $213 fair value for Vistra.
The IRAS challenge is really about keeping that pathway intact. Vistra is arguing that PJM’s proposal would separate actual data center demand from core capacity pricing signals and penalize large new loads. That cuts across the Narrative’s reliance on multi decade nuclear PPAs with Meta and Amazon tied to PJM rules that are predictable and even handed.
There is also a timing and risk angle. A drawn out FERC process could influence when new PJM projects, including DOE backed nuclear upgrades, slot into the earnings mix, while an outright approval of IRAS could affect how future contracts are written versus rivals like Constellation or NextEra. Analysts have already flagged regulatory shifts and high leverage as key risks, so this filing is management trying to shape the rulebook rather than just absorb it.
For a holder, this kind of regulatory fight is a reminder that an investment in Vistra is ultimately a judgment on the whole Narrative, not just the latest filing or headline.
The quiet Vistra signal most holders never run the numbers on
There is a separate lens on Vistra that rarely gets airtime, a view built purely from the cash coming in and going out and how that stacks up against today’s share price. Find out exactly what Vistra is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com