
Align Technology (ALGN) Stock Looks Reasonable Despite Its 78% Five Year Fall
Align Technology has had a bruising five year stretch, with the share price now reflecting a long reset in expectations. The live question is whether today's valuation is supported by its earnings power. With the stock trading around US$140.65, investors are weighing what the current price really implies about the business behind Invisalign and its broader digital dentistry platform.
- Over the past 5 years the share price has fallen 77.7%, which puts the spotlight squarely on whether the current earnings base can carry the valuation from here.
- Recent coverage of the wider dental equipment market points to growing demand for digital tools such as scanners and 3D printing, which can support expectations for Align Technology's future profitability if the company converts that demand into earnings.
- Your read on Align Technology is one view; the desks covering it have another. See what analysts think Align Technology's shares could be worth.
For investors, the debate is whether Align Technology's current share price is adequately explained by what the company earns today and what those earnings reasonably point to over time.
If you are weighing Align Technology against other dental and medical equipment opportunities, it can help to compare it directly with 33 healthcare AI stocks.
Does Align Technology Look Undervalued on Earnings?
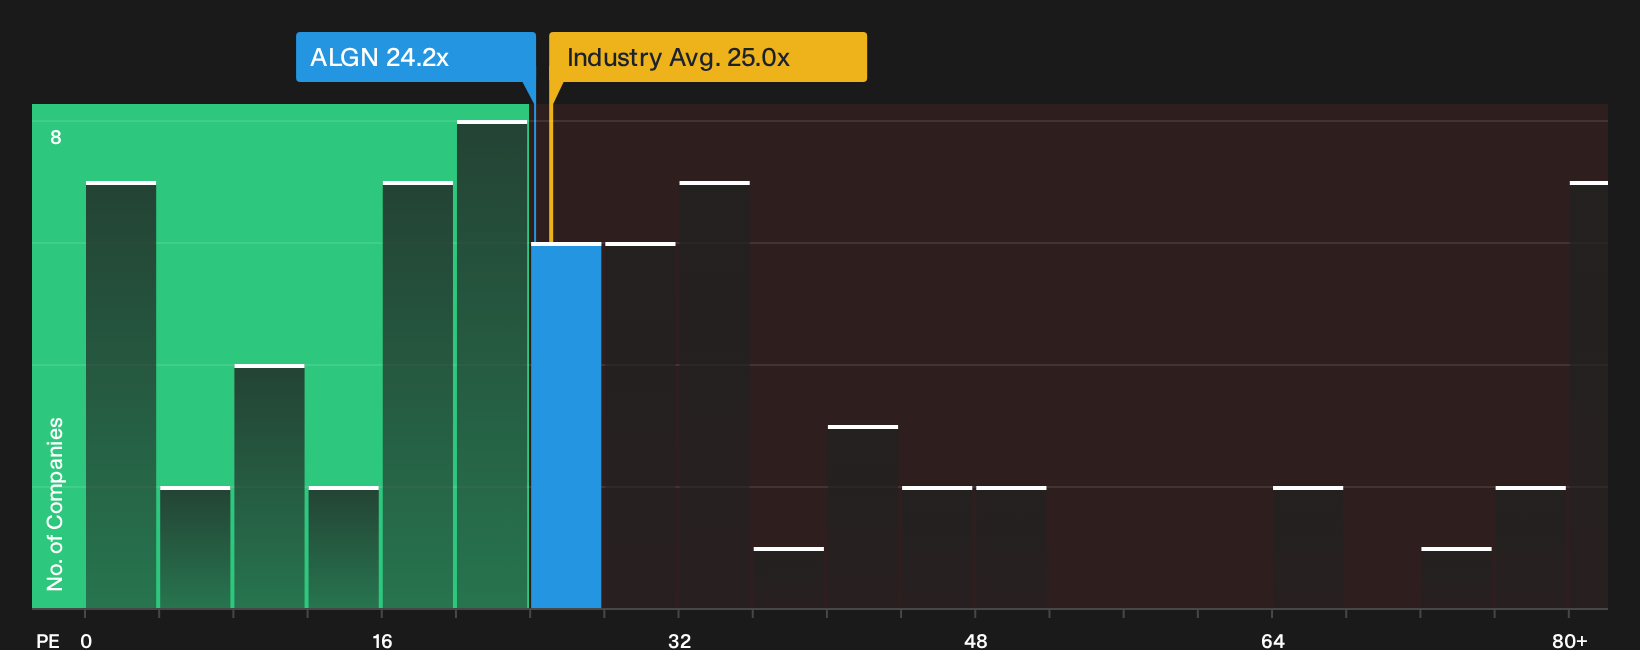
The P/E ratio fits Align Technology because earnings are a key focus for most investors in established medical equipment businesses. Align Technology currently trades on a P/E of about 24.2x, which is slightly below the medical equipment industry average of roughly 25.0x and also below the peer group average of about 25.6x.
Because recent research highlights growing interest in digital dental equipment, this modest discount suggests the stock is not priced for especially strong or especially weak prospects compared with sector peers. The current P/E also sits below the level implied by a more tailored fair multiple that factors in Align Technology's profitability profile, size and risk, so the market price appears to ask for a lower earnings multiple than that framework would indicate. Despite the upbeat backdrop for digital tools in dentistry, the shares trade at a P/E that points to a mild discount on this earnings lens. Explore the numbers behind Align Technology's P/E valuation.
The Align Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Align Technology leaves off by spelling out which expectations for future growth, profitability and earnings would need to hold for the stock to be worth materially more or materially less than it is today on the market. Each narrative ties a specific fair value to a particular storyline about Align Technology's potential catalysts and key risks, so you can track over time which version of events seems to be unfolding on the Community page.
One of the top community narratives on Align Technology: 32% undervalued
"Demand for Invisalign across APAC, EMEA and Latin America continues to be a key driver, with double digit Clear Aligner volume growth…"
Discover why this Narrative puts Align Technology at 32% undervalued.
An unanswered piece of the Align Technology puzzle
Valuation only tells part of the story for Align Technology, because the judgment calls made by the leaders in charge and how they are rewarded can pull the business in very different directions. See who runs Align Technology and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com