
TSMC Is Set Up for a Big October 15. After Record Monthly Sales, 2nm and Margins Will Drive Future Price Action.
Taiwan Semiconductor Manufacturing (TSM) reports third-quarter earnings on October 15, with its stock trading near its 52-week high. During its last earnings call, management guided for third-quarter revenue of $44.6 billion to $45.8 billion, about 37% higher than a year earlier at the midpoint. Its revenue is more predictable than most companies, though. TSMC reports sales every month, and July and August already add up to about two-thirds of the quarter’s guided total. Its August revenue increased 53% from a year earlier, setting a monthly record. Even if September sales fall about 10% from August's record, the company would still land in the middle of its guided range. That’s based on TSMC’s own exchange-rate assumption.
In July, TSMC also raised its full-year growth outlook to slightly above 40% and lifted capital spending plans to between $60 billion and $64 billion.
Margins Are the Number to Watch
Since revenue holds fewer surprises than usual, the bigger question becomes profitability. TSMC is quickly ramping up its new 2-nanometer chips, and new technology is expensive to produce at first. Management said that ramp would cut gross margin by about 3 to 4 percentage points in the second half. That’s why it guided third-quarter gross margin to between 65% and 67%, down from 67.7% in the second quarter.
With strong revenue expected, I believe the stock’s reaction will depend on margins instead. A gross margin near the top of the guided range would show TSMC is absorbing those 2-nanometer costs better than planned. A soft margin outlook for the fourth quarter, on the other hand, could weigh on the stock even with record sales. The question for investors is whether the stock prices in that margin risk, so valuation is what I would look at.
TSMC trades above its usual valuation, primarily due to its growth outlook. The forward GAAP P/E of 26.91x sits about 23% above its five-year average of 21.94x. The forward price-to-sales ratio carries an even steeper premium. At 11.96x, it sits 49% above its five-year average of 8.01x. That wider gap on sales shows investors are paying for how much profit TSMC keeps from each dollar of sales. This is another reason why margins matter so much in this report.
The EPS trajectory explains the premium. Analysts expect earnings to grow 59% this year, then over 29% in each of the next two years. On 2027 earnings, the P/E would drop to roughly 21x, slightly below its five-year average. TSMC also holds about $77 billion more cash than debt, enough to cover this year's $60 billion-plus spending plan without relying on borrowing. So I think the valuation overall holds up as long as margins do.
About TSM Stock
Taiwan Semiconductor Manufacturing is the world’s largest semiconductor foundry. Together with its subsidiaries, the company manufactures, packages, tests, and sells integrated circuits and other semiconductor devices. TSMC provides various wafer fabrication processes, such as manufacturing complementary metal-oxide-semiconductor logic, mixed-signal, radio frequency, embedded memory, and others. The company is also involved in providing customer and engineering support services. Founded in 1987, the company is headquartered in Hsinchu City, Taiwan.
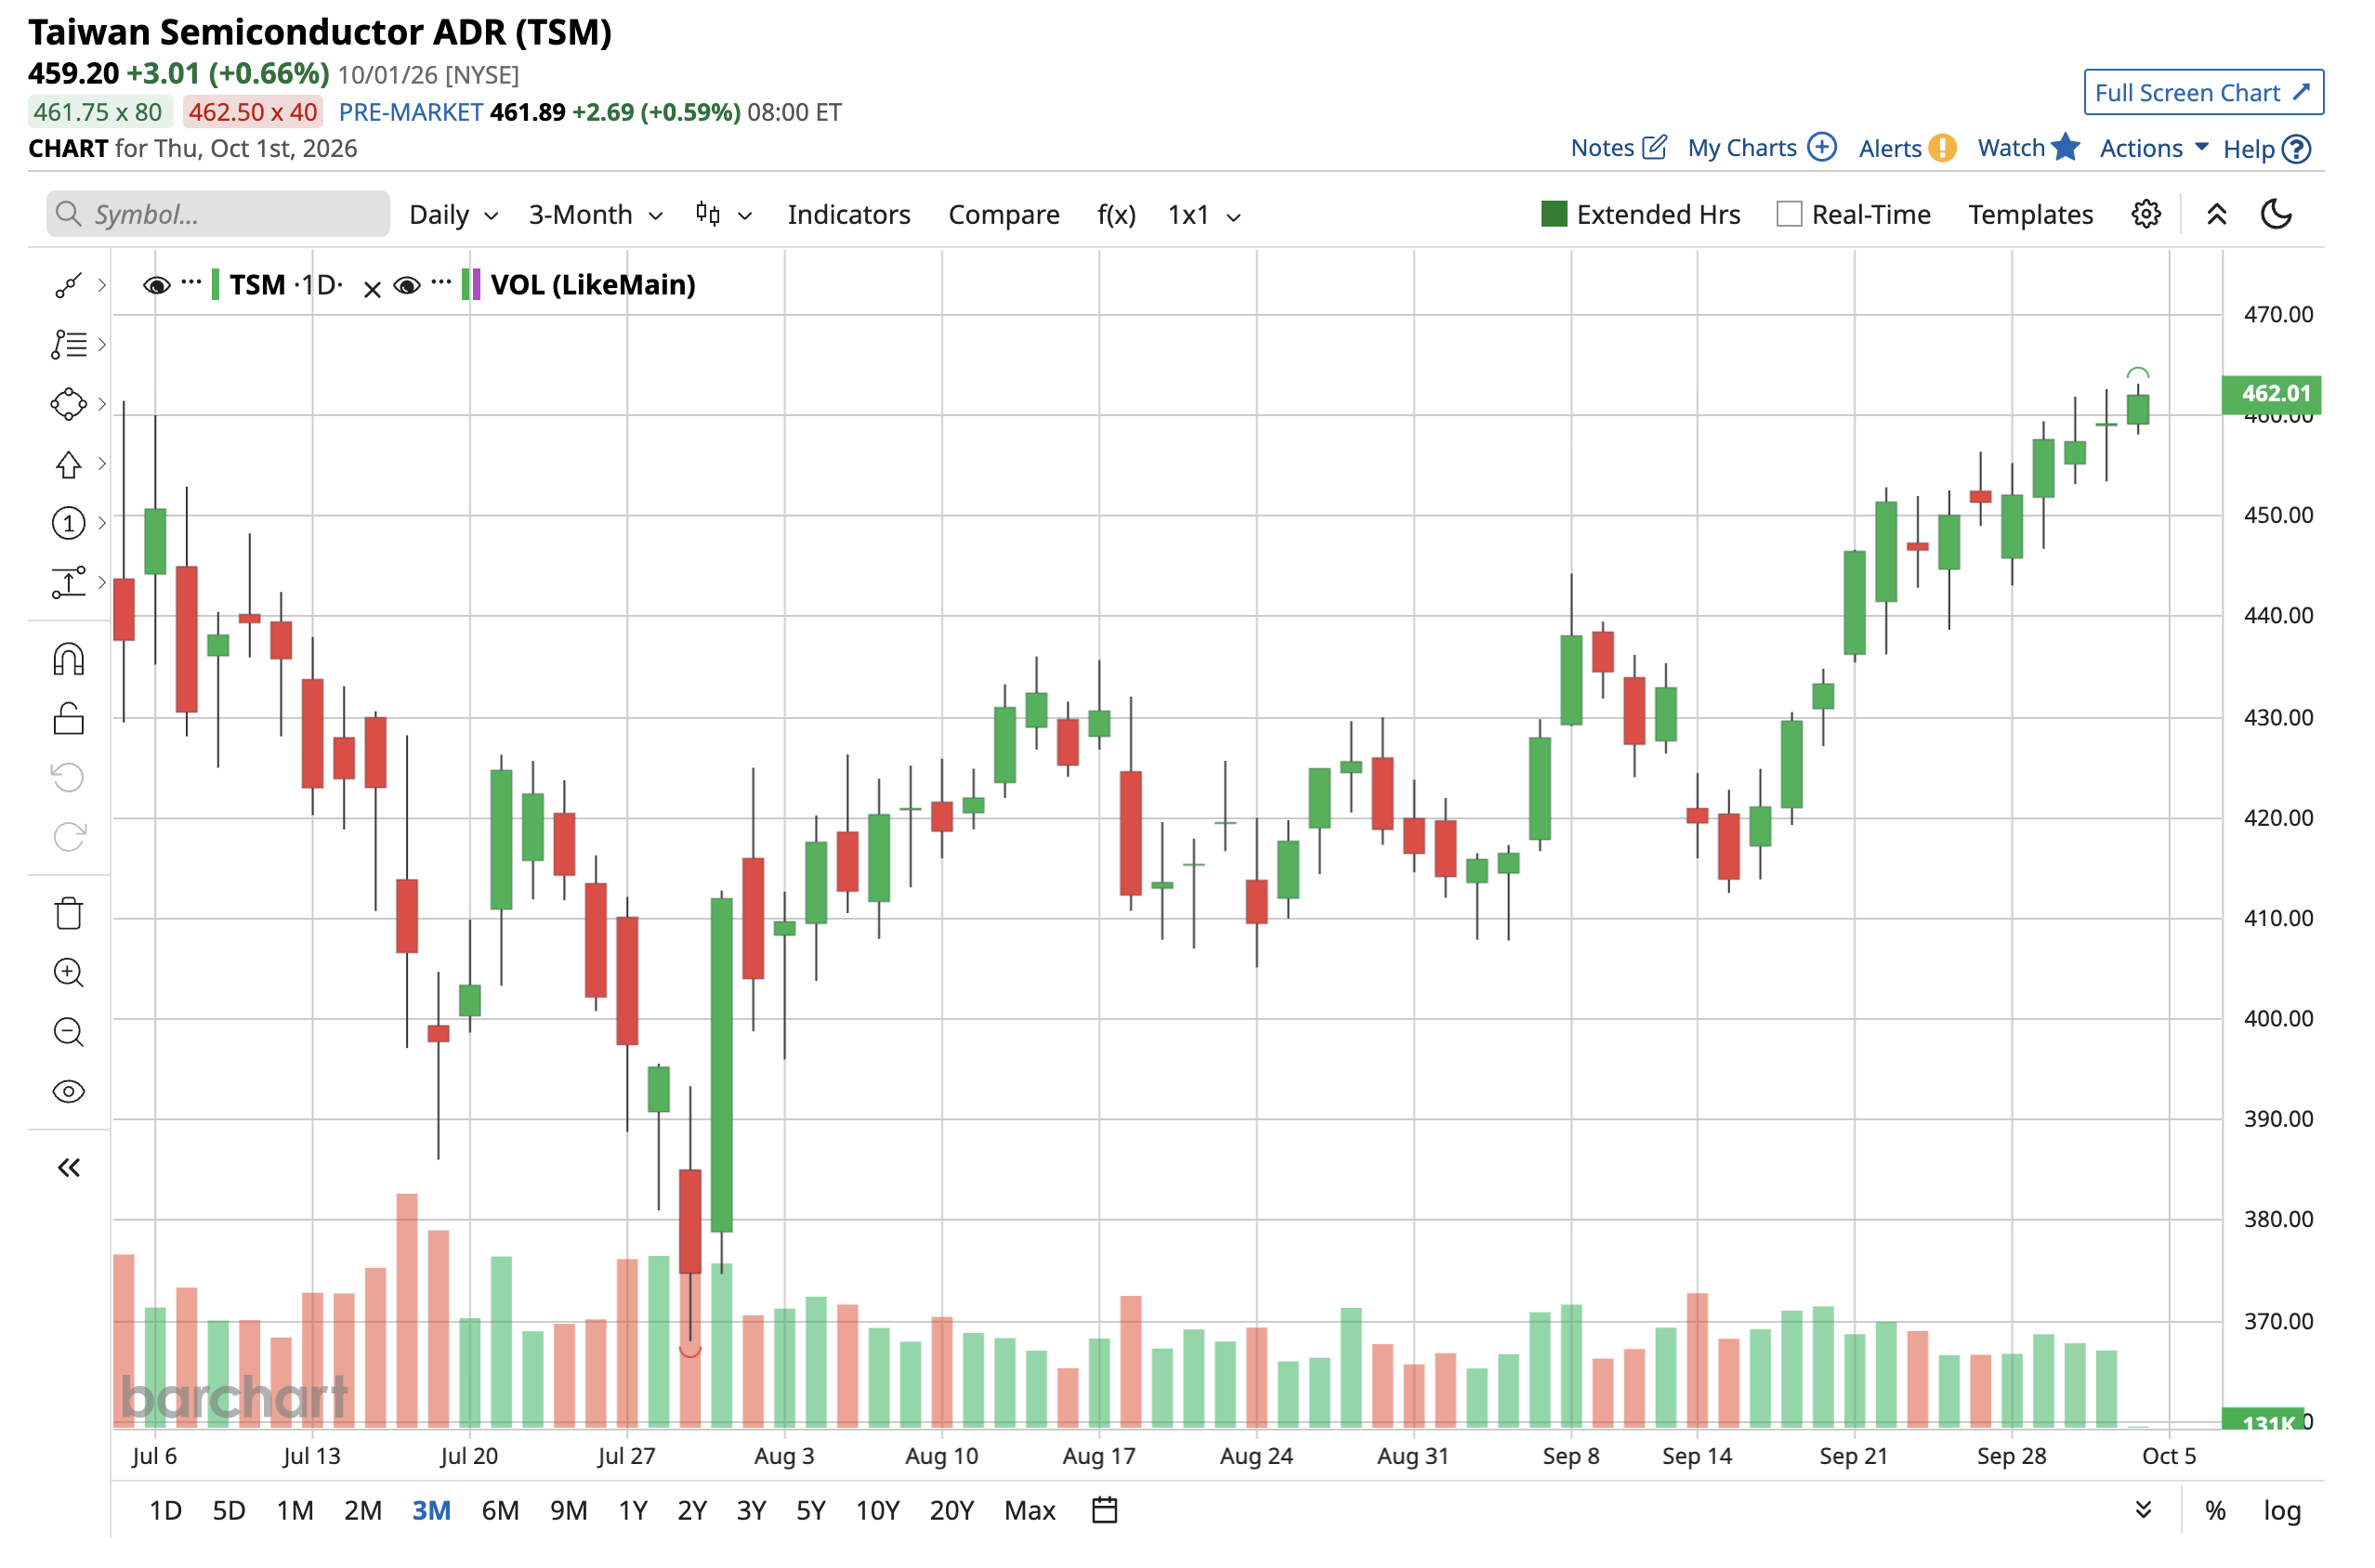
TSM stock has delivered gains of around 60%, while the iShares Semiconductor ETF (SOXX) returned about 104% over the same period. This shows that despite strong performance, TSMC slightly underperformed the broader semiconductor sector. TSMC started gaining traction following its first-quarter earnings and reached a 52-week high of $479 by the end of June. The trend has continued this year as well, with the stock rising approximately 44% while the index has generated twice the returns compared to the stock.
What Do Analysts Expect for TSM Stock?
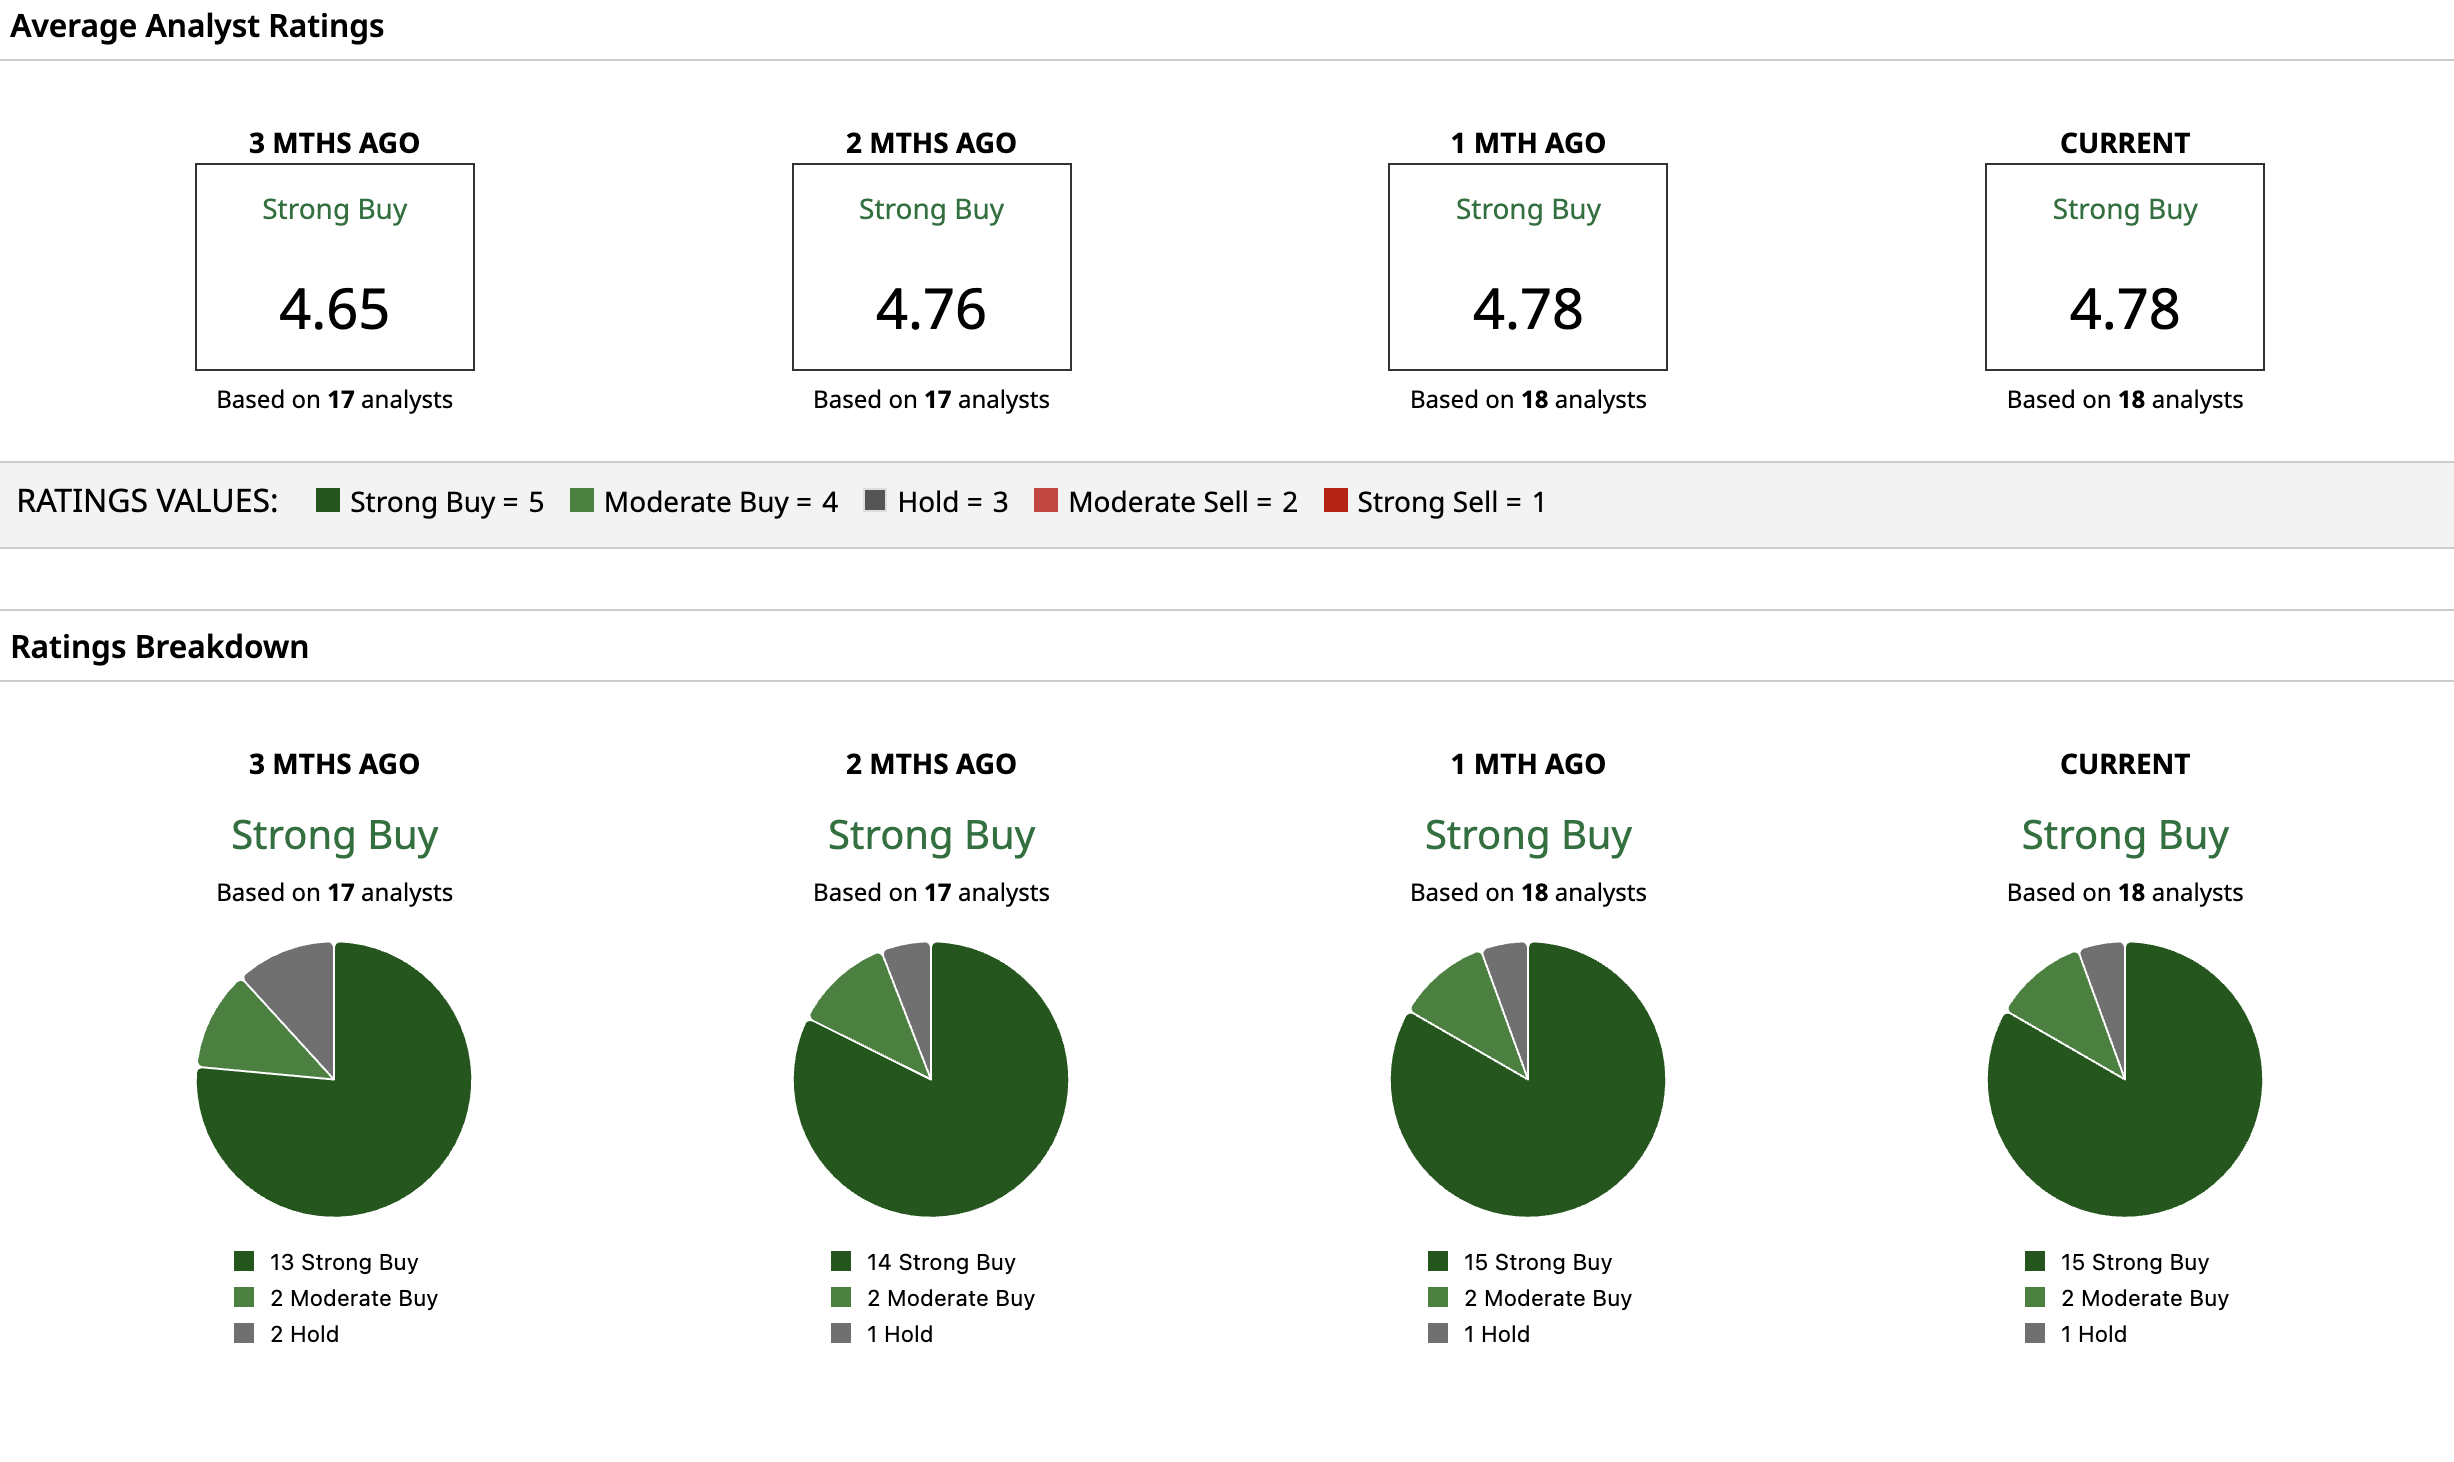
Susquehanna analyst Mehdi Hosseini reiterated a Buy rating on TSM and assigned a price target of $600. Similarly, TSM also received a Buy rating from Stifel Nicolaus and a price target of $515. Based on 18 Wall Street analysts, TSM holds a consensus “Strong Buy” rating. Out of those, 15 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and one has a “Hold” rating. The stock’s mean price target of $517 reflects a modest upside of 13% from the current share price. The high price target of $650 implies 42% upside from the current levels.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.