
October 2026's Leading Growth Stocks With Insider Backing
The United States market has shown a robust performance, climbing 1.6% in the past week and achieving a 13% increase over the last year, with earnings projected to grow by 18% annually in the coming years. In such an optimistic environment, growth companies with substantial insider ownership can be particularly appealing as they often indicate strong confidence from those who know the business best.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Sable Offshore (SOC) | 11.6% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 14.4% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.2% |
| Dave (DAVE) | 16.7% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
Let's take a closer look at a couple of our picks from the screened companies.
monday.com (MNDY)
Simply Wall St Growth Rating: ★★★★☆☆
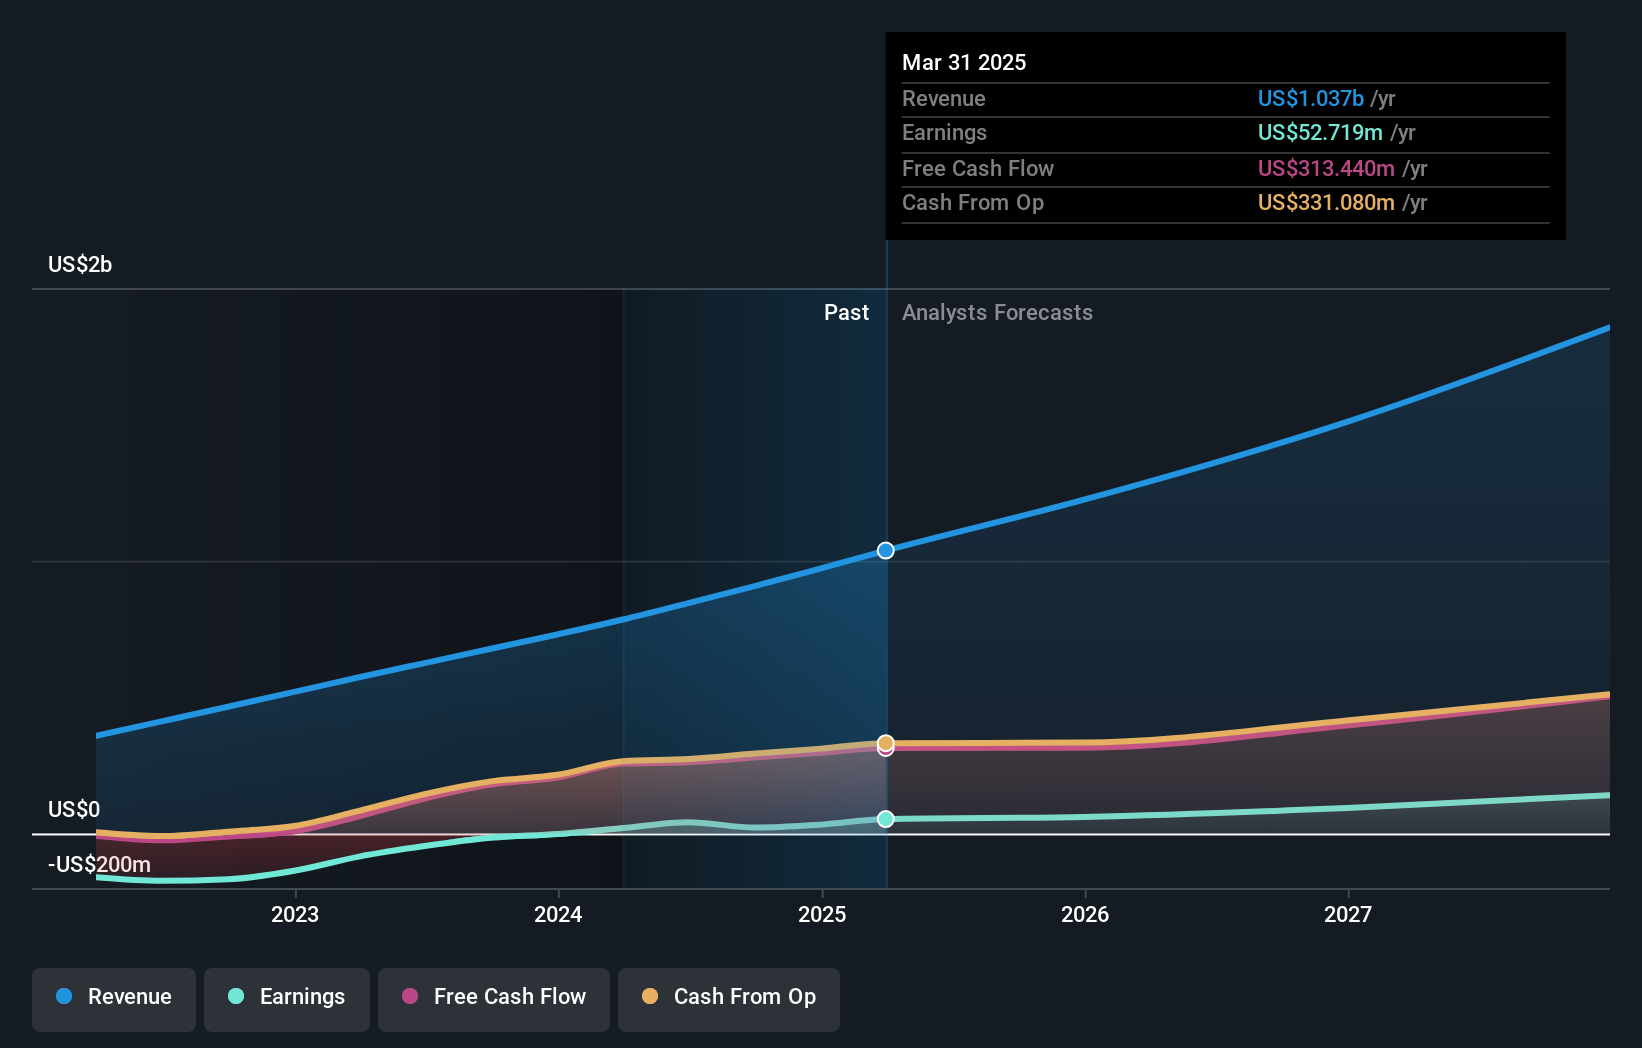
Overview: monday.com Ltd., along with its subsidiaries, develops software applications globally and has a market cap of $3.33 billion.
Operations: The company's revenue is generated entirely from its Internet Software & Services segment, amounting to $1.37 billion.
Insider Ownership: 16.8%
monday.com is experiencing significant earnings growth, forecasted at over 20% annually, surpassing the US market average. Despite slower revenue growth projections of 12.6% per year compared to the market, it trades below its estimated fair value and shows good relative value against peers. Recent restructuring aligns with a strategic focus on AI, involving a workforce reduction but continued investment in key areas. The company has completed substantial share buybacks worth $870 million.
- Click to explore a detailed breakdown of our findings in monday.com's earnings growth report.
- The valuation report we've compiled suggests that monday.com's current price could be quite moderate.
Zscaler (ZS)
Simply Wall St Growth Rating: ★★★★☆☆
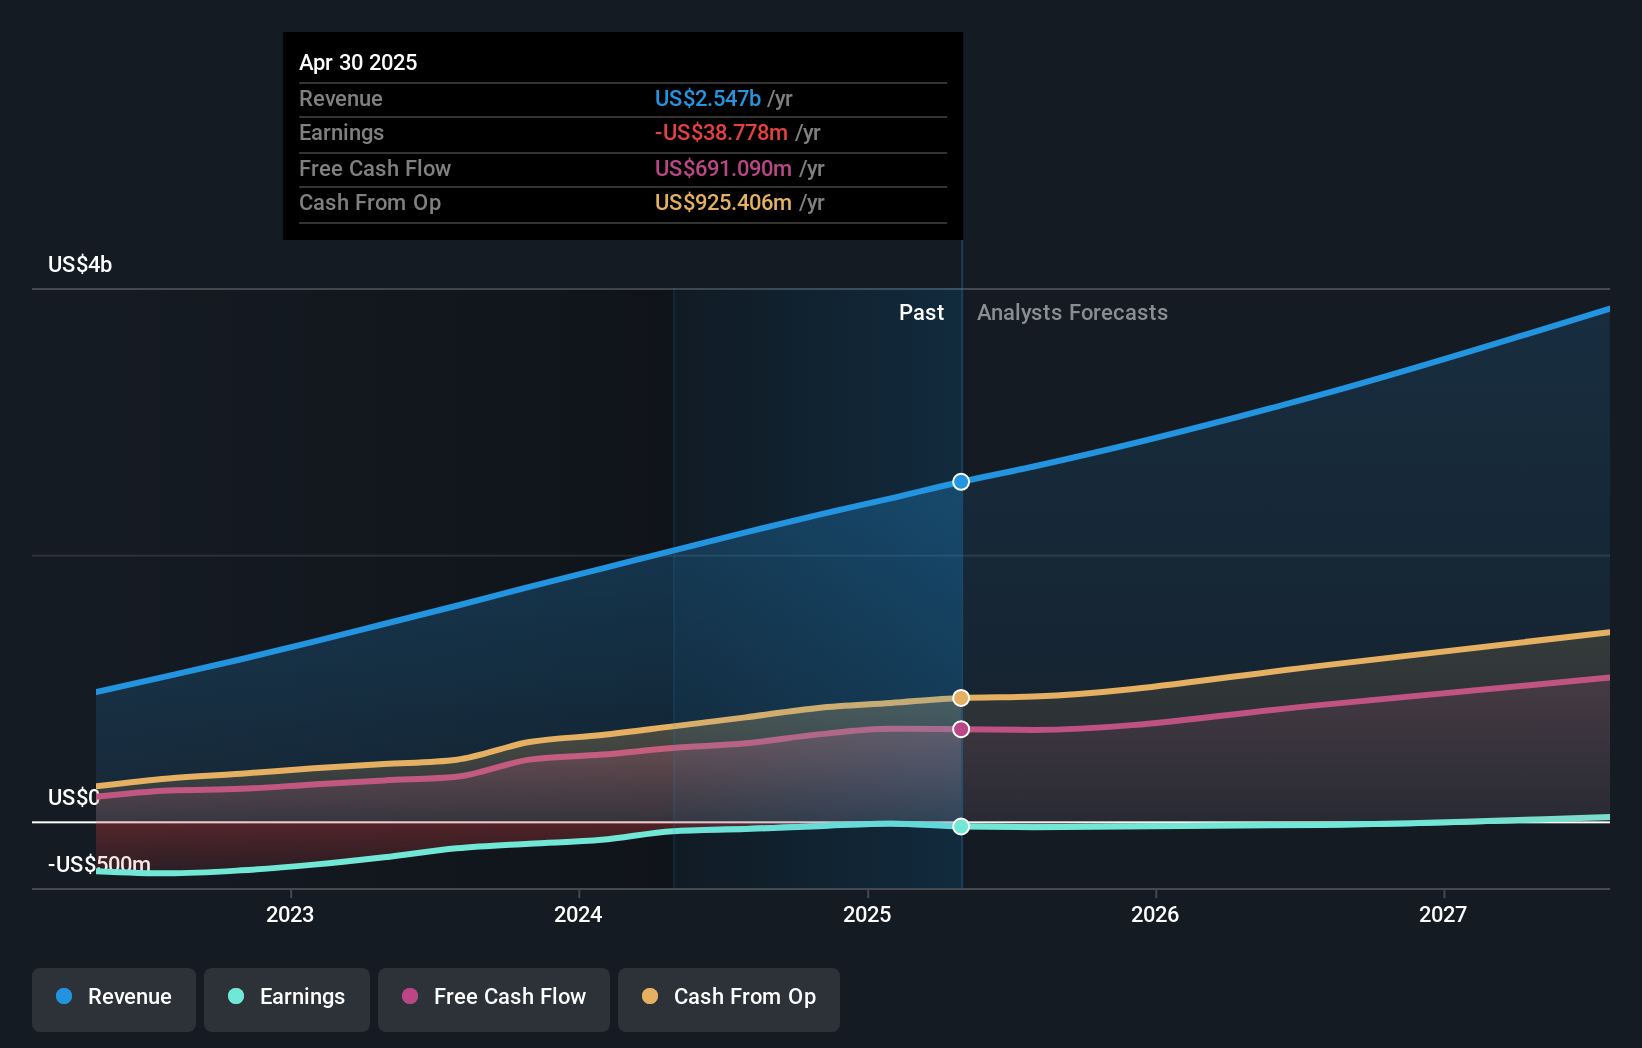
Overview: Zscaler, Inc. is a global cloud security company with a market capitalization of approximately $32.06 billion.
Operations: The company generates revenue primarily through sales of subscription services to its cloud platform and related support services, amounting to $3.35 billion.
Insider Ownership: 34.7%
Zscaler is poised for profitability within three years, with earnings expected to grow at 42.37% annually, outpacing market averages. Despite a slower revenue growth forecast of 13.2% annually compared to the broader U.S. market, it trades below its estimated fair value. Recent executive changes and strategic collaborations with IBM and Red Hat enhance its cybersecurity offerings, yet significant insider selling has been observed over the past quarter without substantial insider buying activity.
- Click here to discover the nuances of Zscaler with our detailed analytical future growth report.
- In light of our recent valuation report, it seems possible that Zscaler is trading behind its estimated value.
Shift4 Payments (FOUR)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Shift4 Payments, Inc. provides software and payment processing solutions both in the United States and internationally, with a market cap of approximately $2.86 billion.
Operations: The company's revenue primarily comes from data processing, generating $4.78 billion.
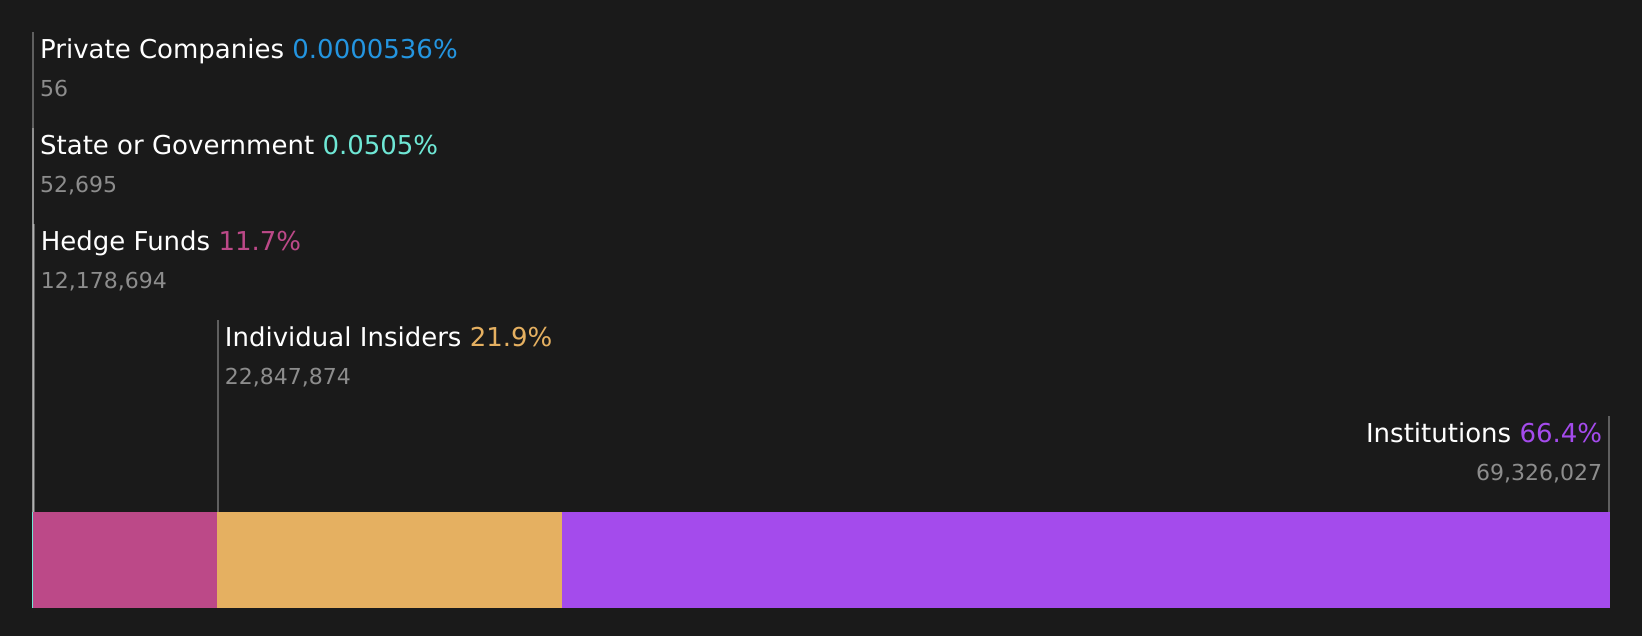
Insider Ownership: 24.9%
Shift4 Payments is set for robust growth, with earnings projected to increase significantly at 56.8% annually, surpassing the U.S. market average. Despite a volatile share price and lower profit margins compared to last year, it trades slightly below its estimated fair value. Recent initiatives include the launch of Shift4 One in Europe and a substantial share buyback program worth US$624.96 million, enhancing shareholder value despite limited insider trading activity recently reported.
- Dive into the specifics of Shift4 Payments here with our thorough growth forecast report.
- Our comprehensive valuation report raises the possibility that Shift4 Payments is priced higher than what may be justified by its financials.
Taking Advantage
- Gain an insight into the universe of 183 Fast Growing US Companies With High Insider Ownership by clicking here.
- Ready For A Different Approach? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com