
Earnings Beat Altering The Investment Case For Oracle Japan Stock (TSE:4716)?
- Oracle Corporation Japan reported first quarter 2026 results for the period ended August 31, 2026, with sales of JPY 74,861 million, net income of JPY 18,245 million, and basic and diluted EPS from continuing operations of JPY 142.37.
- The company’s first quarter performance showed higher sales, net income, and earnings per share than the same period a year earlier, indicating stronger operational execution in its core business.
- This article will explore how Oracle Corporation Japan's investment narrative could be affected by this first quarter earnings performance.
Oracle Corporation Japan Investment Narrative Recap
To own Oracle Corporation Japan, you need to believe its mix of cloud, software, and services can keep pulling in reliable demand from large domestic clients. The latest quarter showed sales of ¥74,861 million and net income of ¥18,245 million, with higher earnings per share than a year earlier. That keeps the near term narrative anchored in execution rather than repair mode.
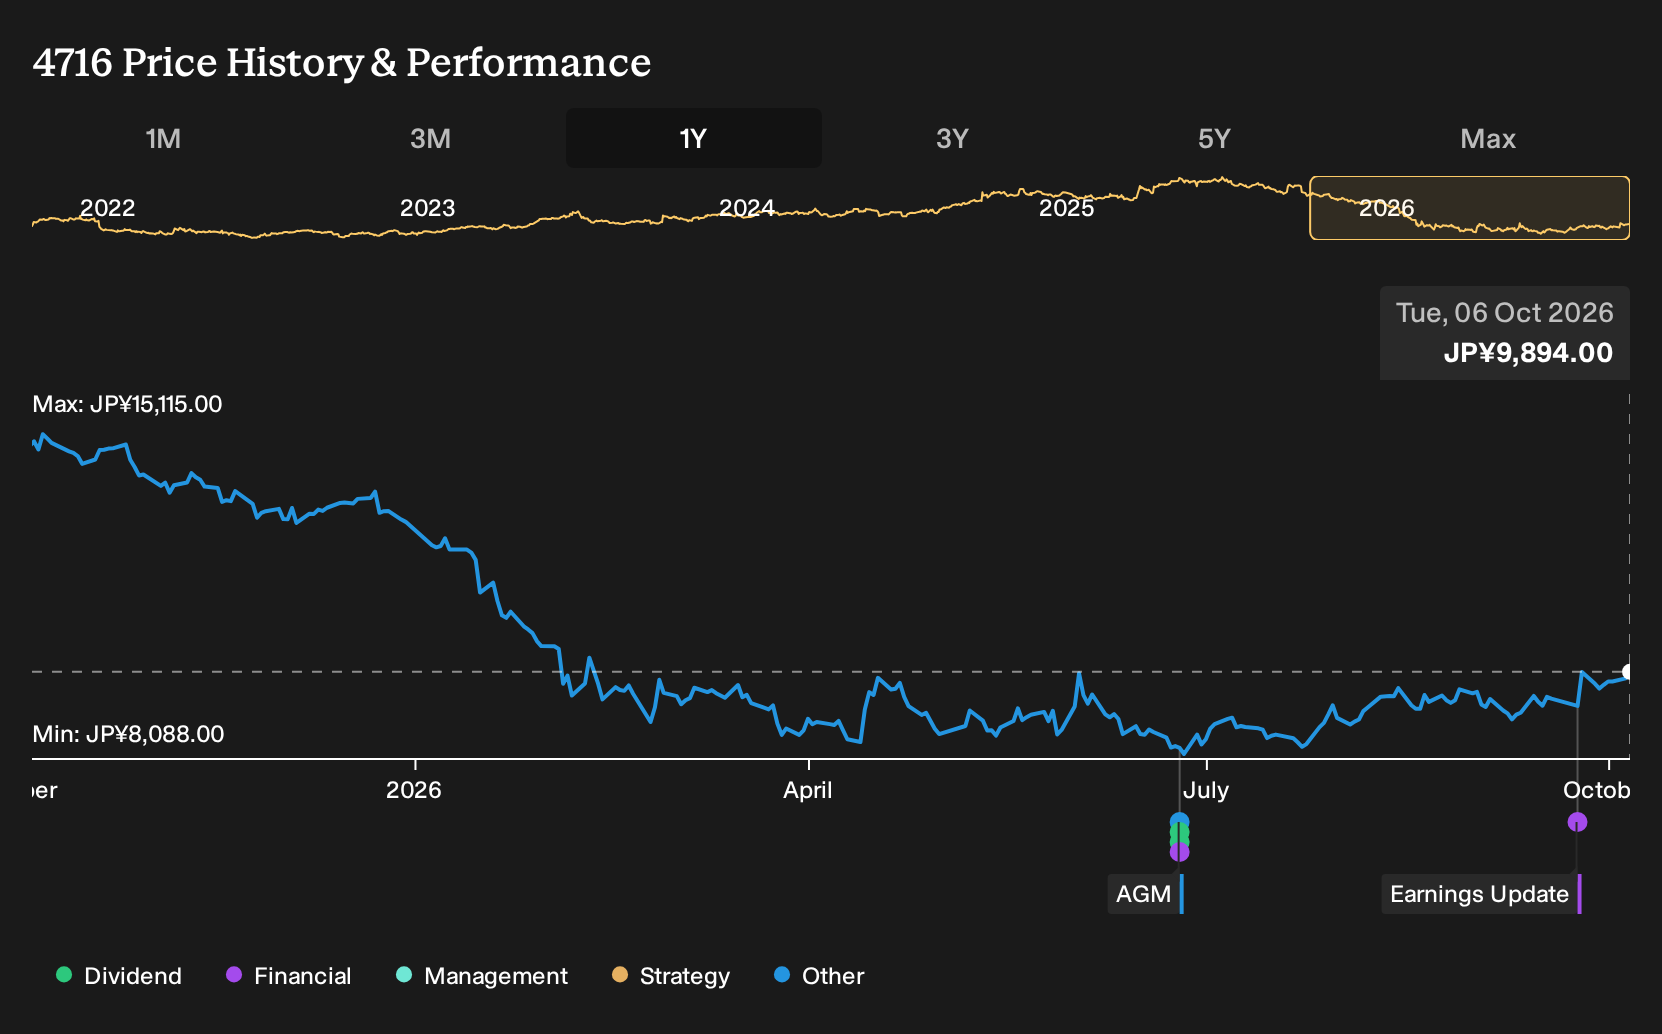
The key short term catalyst is continued adoption of Oracle cloud by big enterprises and smooth delivery on existing contracts. The main risk sits in execution slippage or competitive pressure that slows this cloud and services momentum, especially given an unstable dividend track record and recent share price underperformance versus the wider Japanese market.
Among recent information, the most relevant piece alongside this earnings release is the picture of Oracle Corporation Japan as a business that has grown earnings by 5.7% per year over the past 5 years, with current profit margins of 22.8%. The latest quarter’s higher earnings per share versus last year fits into that longer trend of gradual earnings expansion.
That matters for the catalyst story. Analysts expect revenue and earnings to grow around 8% per year, with high forecast return on equity and high quality earnings. The first quarter numbers align with that profile rather than contradict it. For you, the question is whether consistent execution in cloud partnerships and migrations can continue while you accept the risks around dividends, governance, and recent share price underperformance.
Oracle Corporation Japan’s current analyst story points to forecast revenue of ¥361.5b and projected earnings of ¥82.3b by 2029, based on an assumed 8.2% yearly top line growth and an earnings increase of about ¥18.8b from the ¥63.5b recorded today.
Uncover how Oracle Corporation Japan's fair value indicates a 22% potential upside to its current price, which could narrow quickly if Oracle Corporation Japan keeps executing like this.
Exploring Other Perspectives
One optimistic twist on Oracle Corporation Japan focuses on AI driven cloud demand. The most bullish analysts were already pencilling in revenue of ¥383.6b and earnings of ¥88.0b by 2029 before this quarter. You can read this strong first quarter as a possible early proof point or treat it as noise, which is why opinions differ so widely.
Explore another Oracle Corporation Japan fair value estimate, including one that suggests as much as 22% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Oracle Corporation Japan research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Oracle Corporation Japan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oracle Corporation Japan's overall financial health at a glance.
Looking for more Oracle Corporation Japan investment ideas?
Once you have a view on Oracle Corporation Japan, it can help to compare it against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If you want resilient balance sheets and steadier fundamentals, scan a list of solid balance sheet and fundamentals (23 results) that can help you compare Oracle Corporation Japan with financially robust peers.
- For investors who care most about potential mispricing, review a 75 high quality undiscovered gems that may sit alongside Oracle Corporation Japan on your watchlist as possible misjudged opportunities.
- Income focused investors can zero in on steady cash yields through a 21 dividend fortresses that highlights companies offering higher payouts than Oracle Corporation Japan today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com