
How Investors Are Reacting To Aon (AON) Power Project Insurance Launch
- Aon launched its Power Lifecycle Program, an integrated insurance solution that links construction, testing, commissioning and early operations cover for conventional gas power projects, with capacity of up to US$2.5b per phase and additional third party liability protection.
- The program targets large scale power assets that support data centers and AI related digital infrastructure. It uses a single lifecycle policy structure designed to reduce cover gaps, coordinate risk advisory services and bring London market capacity together for global developers and investors.
- We will look at how Aon’s broader investment narrative is influenced by this lifecycle power solution aimed at digital infrastructure risks.
Aon Investment Narrative Recap
To own Aon, you need to believe its risk, reinsurance and human capital platform can keep turning complex corporate exposures into fee and commission revenue, even as growth in the wider insurance sector stays moderate. The Power Lifecycle Program fits that view, but it does not materially change the near term picture on its own.
The key short term swing factor still sits with USI integration and how investors react to higher debt, EPS dilution in 2027 and muted buybacks. PLP speaks to product depth in infrastructure risk, yet the biggest immediate vulnerability remains execution on the enlarged US middle market platform.
The recent US$4.0b delayed draw term loan and new US$3.0b revolving credit facility are the most relevant backdrop to PLP. Together they show Aon locking in funding flexibility around the USI deal at the same time it introduces new power and data center risk offerings aimed at large capital projects.
For you as a shareholder, the link is operational rather than cosmetic. Management is committing to a bigger balance sheet while expanding tools like PLP that rely on analytics and risk advisory depth. The catalyst is whether that combined model translates into steady revenue, stable interest coverage and comfort on leverage.
Aon's current analyst narrative points to revenues of US$22.9b and earnings of US$4.0b by 2029. That profile assumes revenue expands at 9.2% a year and earnings rise by about US$0.1b from US$3.9b today to reach the consensus 2029 estimate.
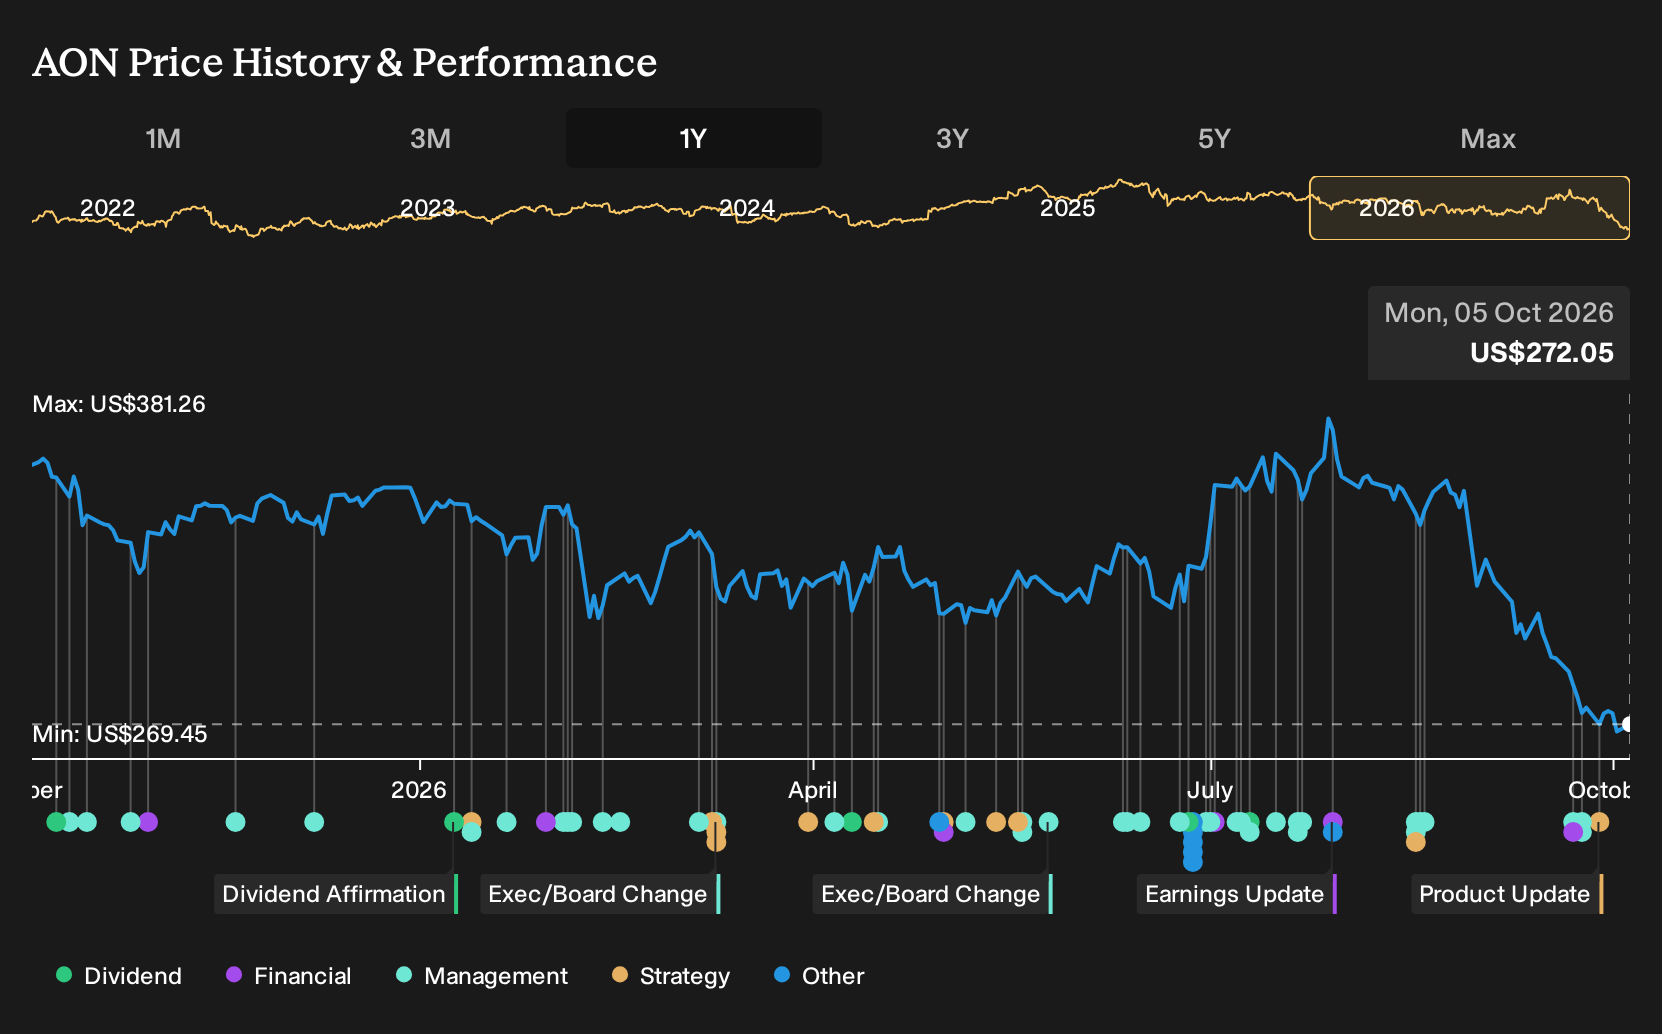
Uncover why Aon's fair value indicates a 39% potential upside to its current price, which could narrow quickly if sentiment improves.
Exploring Other Perspectives
One alternate angle focuses less on PLP itself and more on what AI linked products could mean for the upbeat revenue story around Aon. The most optimistic analysts were already penciling in US$25.3b of revenue and US$4.1b of earnings by 2029. It is possible to see how a program like this might influence those estimates, or cause them to be revisited. This is why it helps to compare several viewpoints before deciding what you think Aon is worth.
Explore another Aon fair value estimate, including one that suggests there could be as much as 50% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Aon research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aon's overall financial health at a glance.
Looking for more Aon sized ideas?
If Aon has sharpened your focus on quality and risk, it can help to widen the lens and scan other listed businesses that might fit your style and return profile.
- For investors who want income with staying power, check out a curated set of 7 dividend fortresses that aim to combine yield with resilience across different sectors.
- If capital preservation comes first for you, narrow in on 31 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Prefer to hunt for lesser known opportunities with solid fundamentals? Use the 19 high quality undiscovered gems to spot companies that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com