
Should Primary Listing Move Require Action From CECO Environmental (CECO) Investors?
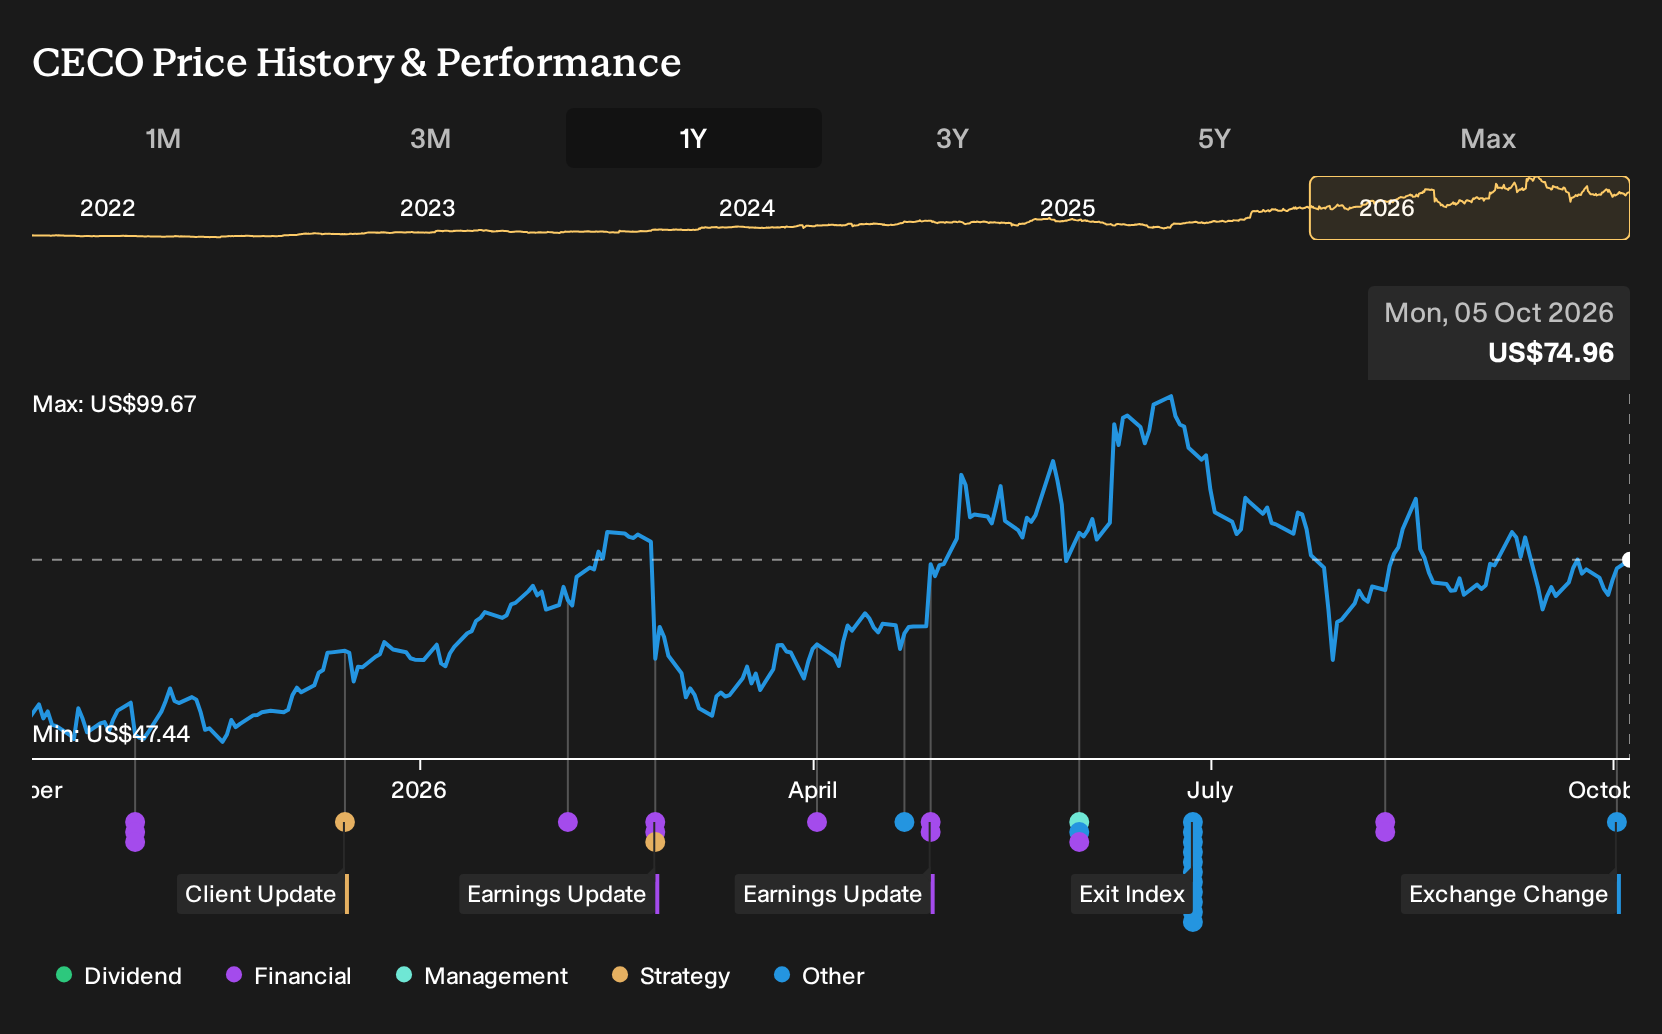
- CECO Environmental has already transferred its primary stock listing from Nasdaq to the Texas Stock Exchange, with its common stock ceasing Nasdaq trading on October 16, 2026. This makes it the first company to hold a primary listing on the new TXSE venue.
- Becoming the inaugural primary listing on TXSE gives CECO Environmental visibility as the exchange’s reference industrial issuer. This may matter for future liquidity, index inclusion decisions, and how management thinks about capital access for its environmental solutions portfolio.
- We will now assess how CECO Environmental's move to become the first primary listing on the Texas Stock Exchange could reshape its investment narrative.
Scan beyond CECO Environmental and size up other industrial and infrastructure players that may react to this shift by reviewing our curated list of 39 power grid technology and infrastructure stocks.
CECO Environmental Investment Narrative Recap
To own CECO Environmental, you need to be comfortable with a growth-first play in industrial air quality and water treatment where the business is still unprofitable. The key belief is that a record backlog and expansion into sectors like power and industrial water eventually convert into steadier earnings and better margins as projects move from order book to revenue.
The main near term swing factor is execution on that order book while carrying higher operating expense, leverage, and past shareholder dilution. The Texas Stock Exchange move is mostly a venue change; it does not alter the immediate operating catalyst or the key risk around growth slowing while costs stay elevated.
The listing transfer to the Texas Stock Exchange is the announcement that matters most right now. Trading on TXSE does not change CECO Environmental’s contracts, backlog, or exposure to environmental regulation. It could influence how different pools of capital view the stock over time, but the day to day story still sits in orders, project delivery, and cash generation.
For you as a shareholder, the focus still sits on whether CECO Environmental can convert forecast revenue growth of 31.3% per year into sustainable profitability while managing a higher P/S than the US Machinery peer group and servicing debt without relying on further material dilution. The TXSE move remains in the background of that execution test rather than replacing it.
CECO Environmental's current analyst narrative points to revenues of US$2.3b and earnings of US$260.7m by 2029, based on forecast yearly top line growth of 42.4% and an earnings increase of about 19x from US$13.7m today.
Uncover why CECO Environmental's fair value indicates a 44% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
You get a very different angle when you focus on execution risk. The lowest analysts worry that CECO Environmental’s large power and gas projects, including a US$135 million Texas facility, could slow how quickly the US$2.1b revenue and US$231.3m earnings they were modelling for 2029 actually materialize. Those views were set before the TXSE move. You may want to compare them with your own expectations and consider how this new listing could shift the story.
Explore 3 other CECO Environmental fair value estimates, including one that suggests it could be worth just $108.20!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CECO Environmental research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CECO Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CECO Environmental's overall financial health at a glance.
Looking For More Investment Ideas Beyond CECO Environmental?
Once you have formed a view on CECO Environmental, it can help to compare it with other opportunities that match your risk tolerance and return goals. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that fits how you like to invest.
- If you are hunting for mispriced quality, start with a focused group of 27 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- If capital preservation is higher on your priority list, a curated set of 31 resilient stocks with low risk scores can help you zero in on companies with more resilient profiles.
- If balance sheet strength matters most to you, use the list of solid balance sheet and fundamentals (25 results) to concentrate on businesses with cleaner debt levels and sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com