
Does Profit Growth Change The Bull Case For MillerKnoll (MLKN)?
- MillerKnoll reported first quarter 2026 results with sales of US$923.4 million compared with US$955.7 million a year earlier, while net income reached US$26.6 million and diluted EPS from continuing operations was US$0.38 compared with US$0.29.
- Alongside these figures, MillerKnoll completed a long running buyback program that has retired 25,268,286 shares for US$687.69 million. This reshapes per share metrics and the ownership base after reducing the share count by 38.12% over time.
- Next, the focus shifts to how MillerKnoll's higher earnings per share, despite softer sales, may influence the broader investment narrative around the business.
Scan how MillerKnoll's buyback story compares with other companies pursuing shareholder friendly capital returns by lining up opportunities from the 7 dividend fortresses
What Is MillerKnoll's Investment Narrative?
To own MillerKnoll, you need to buy into a pretty simple idea. A design led furnishings group with seasoned leadership keeps squeezing more profit out of a mature, capital intensive set of contract and retail operations. The latest quarter fits that story. Sales were US$923.4 million while net income reached US$26.6 million and earnings per share moved to US$0.38. That mix points to execution around pricing, product mix and cost discipline rather than a demand surge.
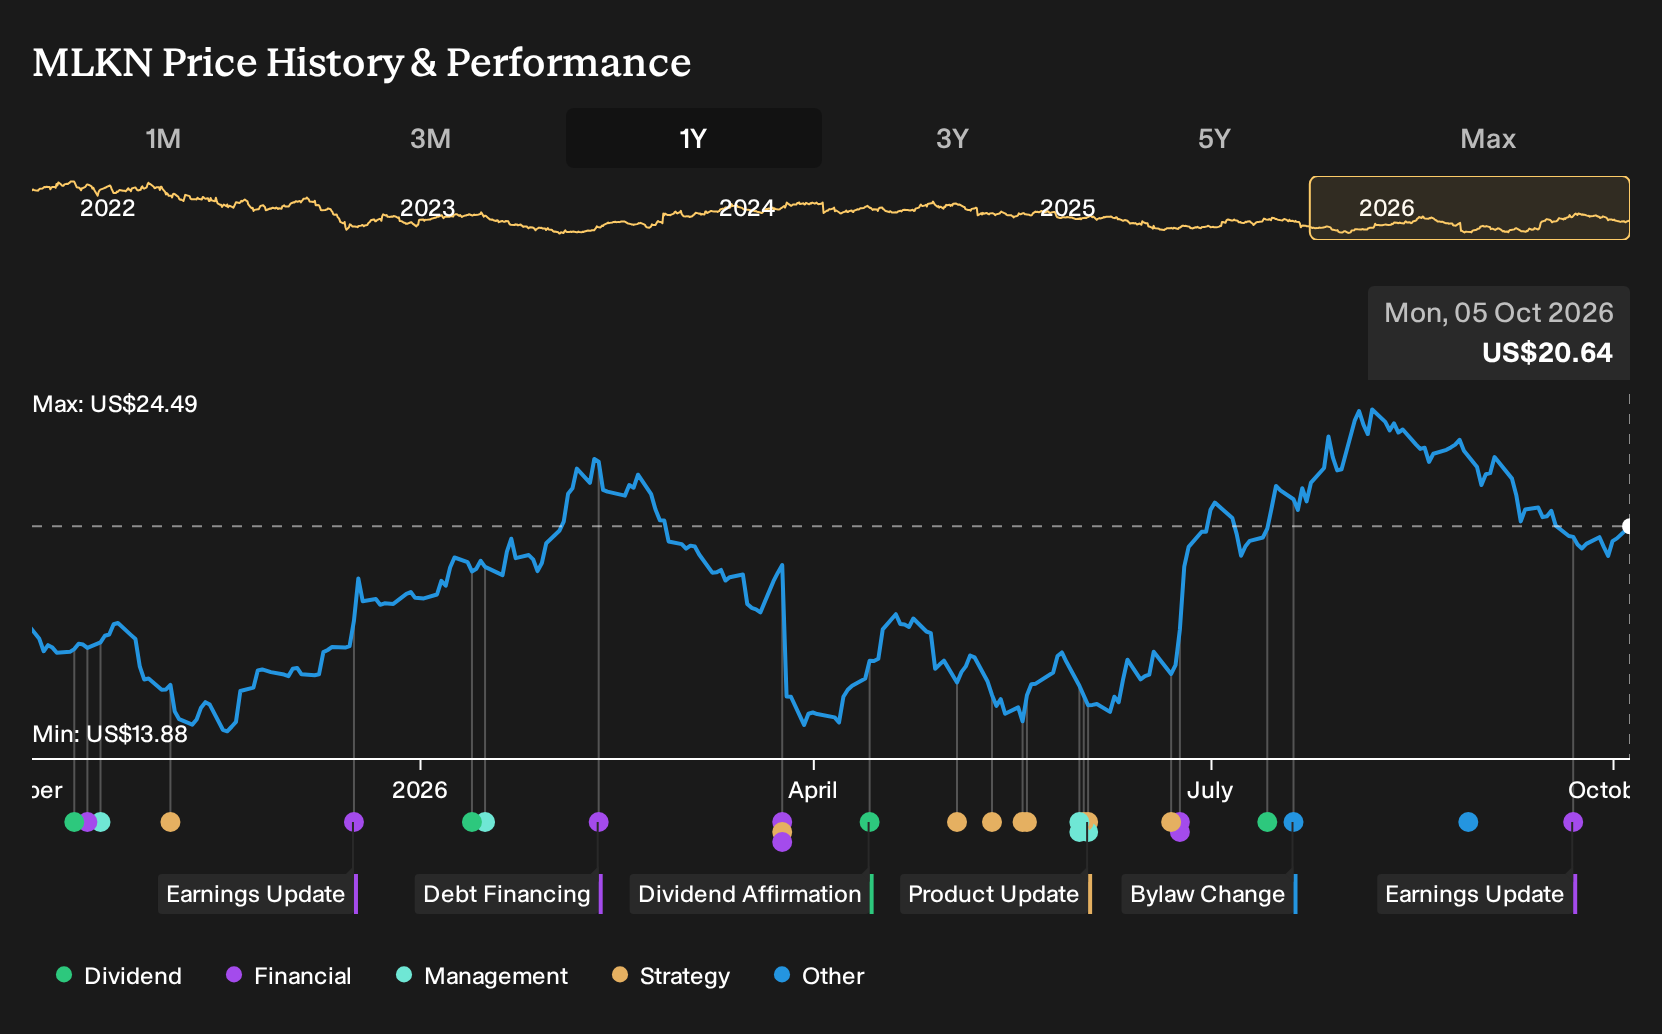
The completed buyback is the other big piece. Retiring 25.3 million shares for US$687.69 million, including 453,975 shares in the latest tranche, concentrates each remaining share in the future cash flows of the business. In the short term, the key swing factors still sit with office, institutional and retail furnishings demand, the capital needed to refresh showrooms and product, and how comfortably cash generation covers debt and ongoing shareholder returns. Recent price moves, with the stock up over 1 year but down around 10% over the past month, suggest the buyback alone does not erase those near term questions around balance sheet flexibility.
Even so, there is a tension in the MillerKnoll story once you line up that aggressive repurchase history against ...
There's only one way to know the right time to buy, sell or hold MillerKnoll. Head to Simply Wall St's company report for the latest analysis of MillerKnoll's Fair Value.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between US$27.28 and US$33 per share, which illustrates how widely private investors can differ even in a small sample. Since these views predate the completed MillerKnoll buyback and the latest quarter, treat them as a starting point and explore other opinions.
Explore another MillerKnoll fair value estimate, including one that suggests it could be worth just $27.28!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MillerKnoll research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MillerKnoll. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MillerKnoll's overall financial health at a glance.
Looking For More Investment Ideas Beyond MillerKnoll?
If MillerKnoll has sharpened your focus on capital allocation and earnings quality, it can be useful to compare it with other businesses that meet clear, fundamentals based criteria. The Simply Wall St Screener helps you filter opportunities quickly so you can spend more time judging the stories that interest you.
- For investors who care most about resilient balance sheets and steady fundamentals, scan a list of solid balance sheet and fundamentals (25 results) that match those financial guardrails.
- If you prefer potential mispricings where quality and valuation intersect, review a curated set of 27 high quality undervalued stocks that might warrant a closer look.
- For income focused portfolios that lean on shareholder returns, compare MillerKnoll's approach with a group of 7 dividend fortresses that emphasize robust payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com