
3 Stocks Including GigaCloud Technology That May Be Trading Below Fair Value
Over the last 7 days, the United States market has risen by 1.6%, contributing to a 13% increase over the past year, with earnings forecasted to grow by 18% annually. In this environment of rising markets and positive earnings expectations, identifying stocks that may be trading below their fair value can offer potential opportunities for investors seeking to capitalize on undervaluation.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $63.28 | $125.16 | 49.4% |
| Textron (TXT) | $75.75 | $146.79 | 48.4% |
| Provident Financial Services (PFS) | $22.38 | $43.18 | 48.2% |
| PPG Industries (PPG) | $105.27 | $202.16 | 47.9% |
| Northeast Bank (NBN) | $125.83 | $247.61 | 49.2% |
| M&T Bank (MTB) | $218.26 | $422.24 | 48.3% |
| KeyCorp (KEY) | $20.18 | $39.88 | 49.4% |
| Fulton Financial (FULT) | $22.69 | $44.83 | 49.4% |
| Civista Bancshares (CIVB) | $26.82 | $53.30 | 49.7% |
| Chagee Holdings (CHA) | $11.19 | $22.20 | 49.6% |
Let's uncover some gems from our specialized screener.
GigaCloud Technology (GCT)
Overview: GigaCloud Technology Inc. offers comprehensive B2B ecommerce solutions for large parcel merchandise both in the United States and internationally, with a market cap of approximately $1.95 billion.
Operations: The company's revenue primarily comes from its Wholesale - Miscellaneous segment, which generated $1.47 billion.
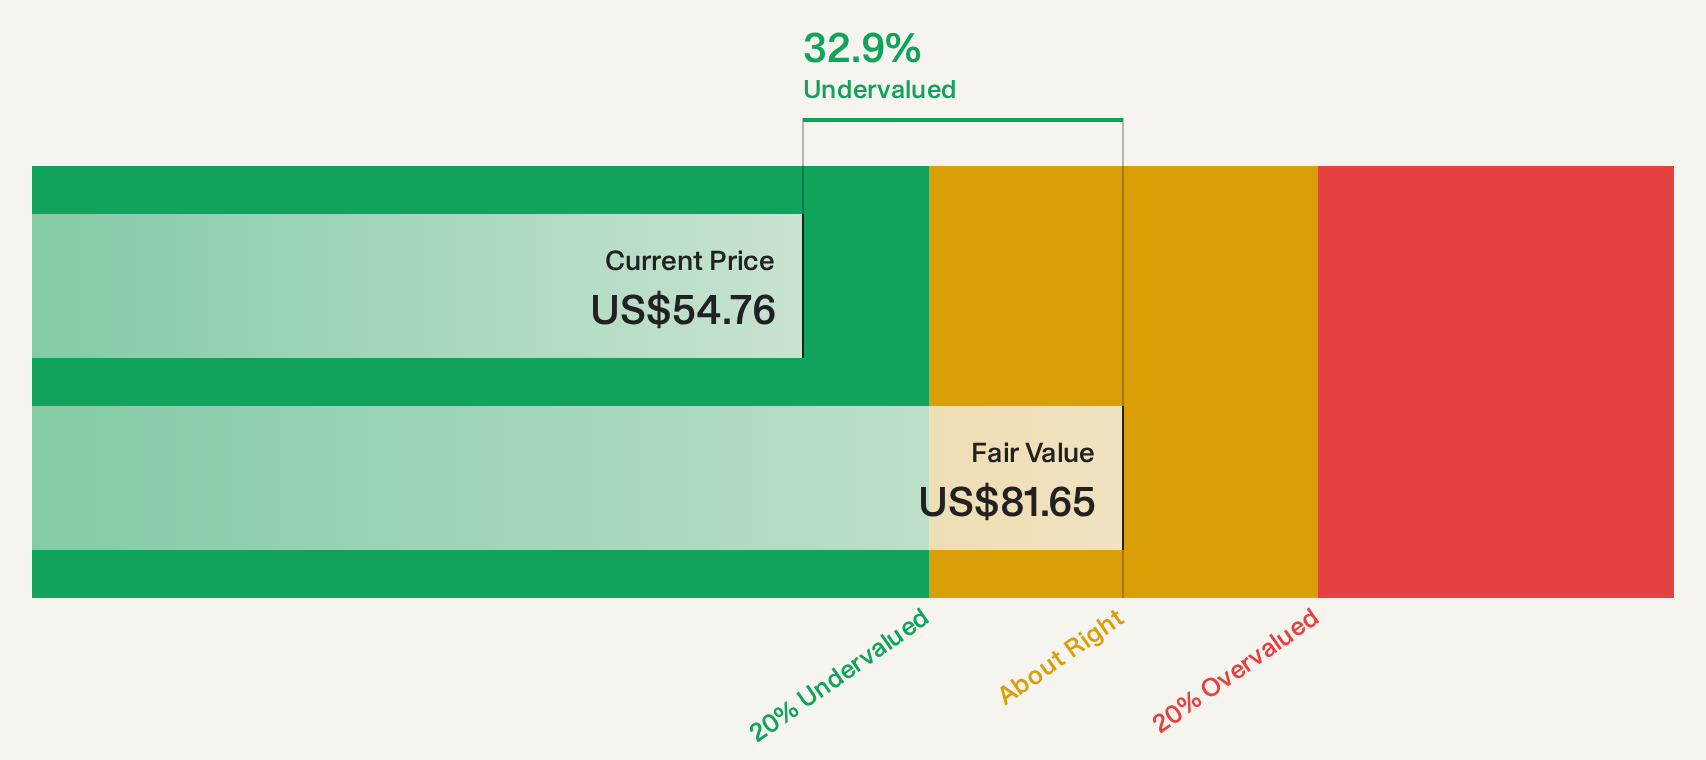
Estimated Discount To Fair Value: 33.8%
GigaCloud Technology is trading at $54.66, significantly below its estimated future cash flow value of $82.53, suggesting it may be undervalued based on cash flows. Despite earnings growth forecasted at 11.72% annually, this is slower than the US market's average. Recent insider selling could be a concern, yet the company has announced a $120 million share repurchase program to capitalize on its current valuation and enhance shareholder value.
- In light of our recent growth report, it seems possible that GigaCloud Technology's financial performance will exceed current levels.
- Unlock comprehensive insights into our analysis of GigaCloud Technology stock in this financial health report.
Paychex (PAYX)
Overview: Paychex, Inc. offers human capital management solutions including human resources, payroll processing, employee benefits, and insurance services for small to medium-sized businesses across the United States, Europe, Canada, India, and Israel with a market cap of approximately $35.22 billion.
Operations: The company's revenue primarily comes from its staffing and outsourcing services, generating $6.60 billion.
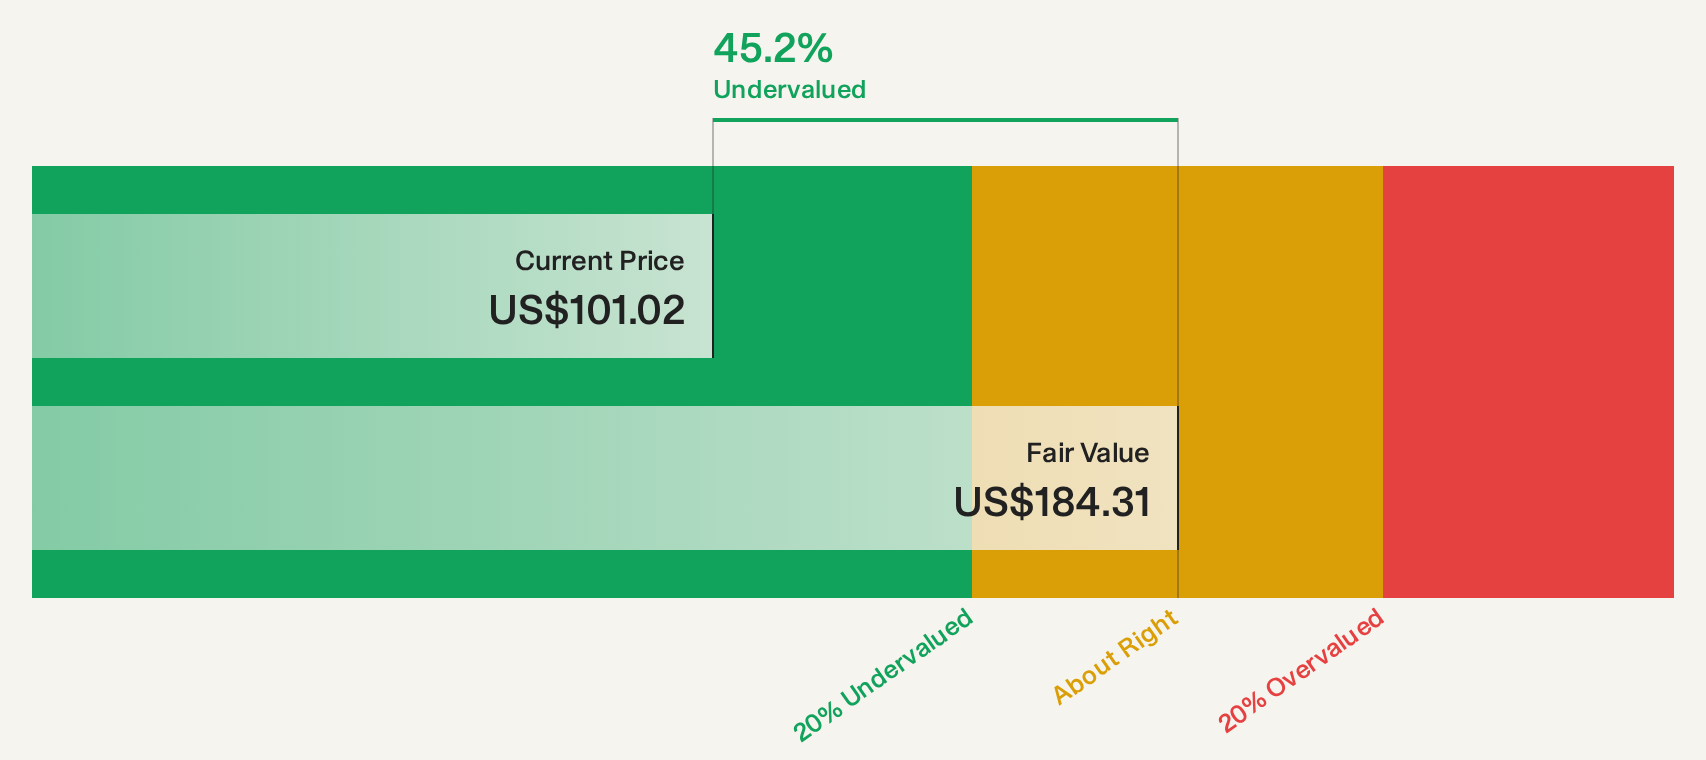
Estimated Discount To Fair Value: 46.7%
Paychex, trading at US$99.78, is undervalued with an estimated future cash flow value of US$187.26. Despite earnings growth forecasted at 8.4% annually—slower than the US market—its strong cash flow position and high dividend yield of 4.77% provide appeal for investors seeking income and value opportunities. Recent updates include new AI-driven products like WISE Hire, enhancing operational efficiency and potentially boosting future revenue streams amidst moderate expected growth rates.
- According our earnings growth report, there's an indication that Paychex might be ready to expand.
- Delve into the full analysis health report here for a deeper understanding of Paychex.
Wintrust Financial (WTFC)
Overview: Wintrust Financial Corporation is a financial holding company offering community-oriented personal and commercial banking services in the United States, with a market cap of approximately $9.80 billion.
Operations: The company's revenue is primarily derived from Community Banking ($2.06 billion), followed by Specialty Finance ($537.90 million) and Wealth Management ($214.12 million).
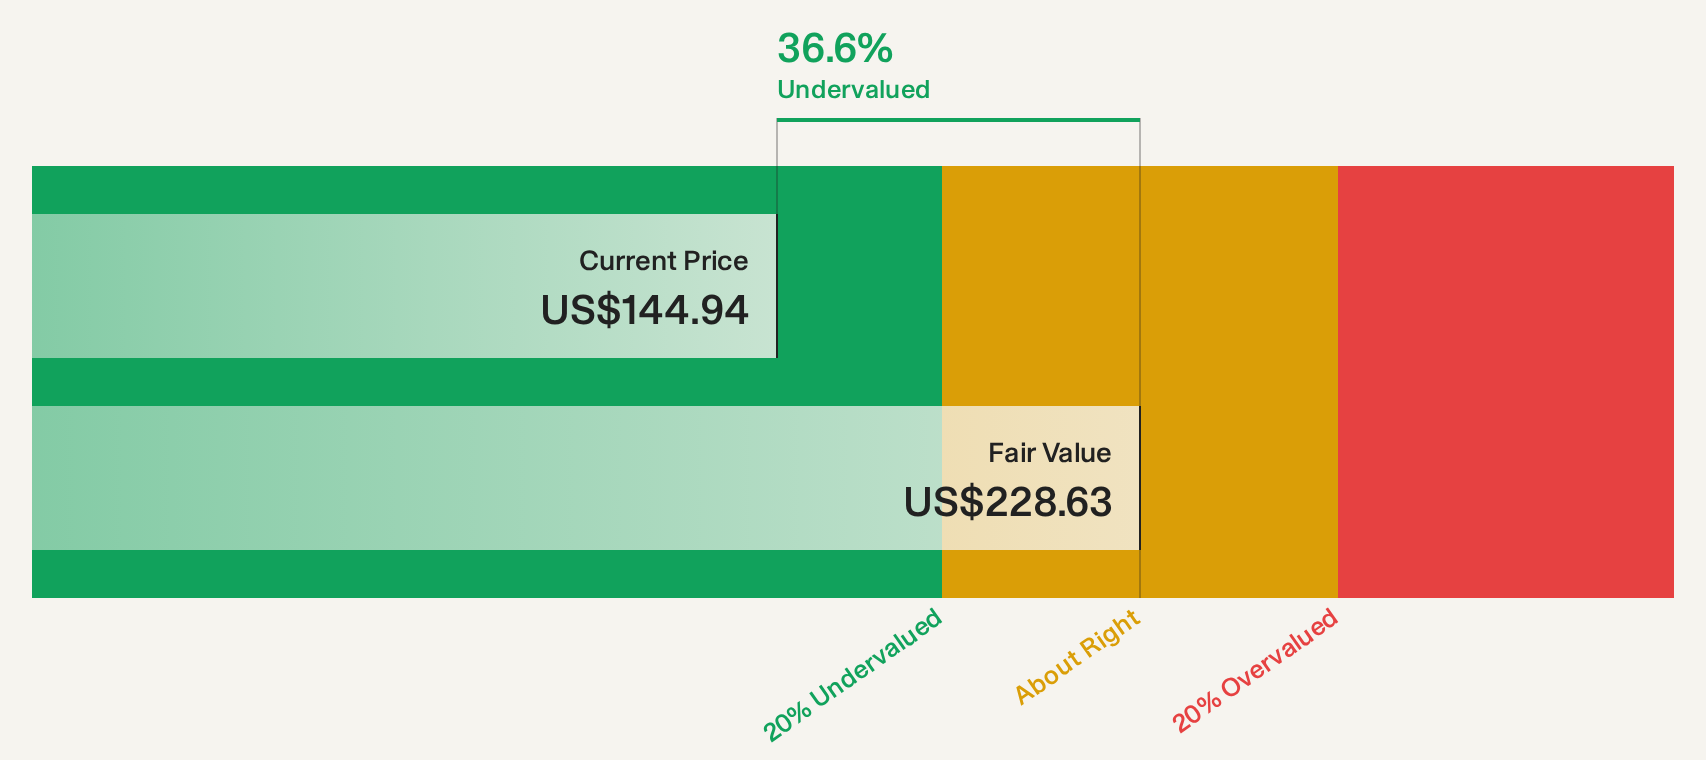
Estimated Discount To Fair Value: 38.2%
Wintrust Financial, trading at $145.20, is undervalued with a future cash flow value estimated at $235.08. Despite forecasts of slower revenue and earnings growth compared to the US market, its net interest income increased to $597.37 million in Q2 2026 from a year ago, and net income rose to $233.69 million. The company maintains dividends on common and preferred stock but faces challenges with significant insider selling recently observed over the past three months.
- Our comprehensive growth report raises the possibility that Wintrust Financial is poised for substantial financial growth.
- Dive into the specifics of Wintrust Financial here with our thorough financial health report.
Key Takeaways
- Investigate our full lineup of 104 Undervalued US Stocks Based On Cash Flows right here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com