
What WiseTech Global (WTC) Holders Had To Stomach, And Where That Question Is Live Now
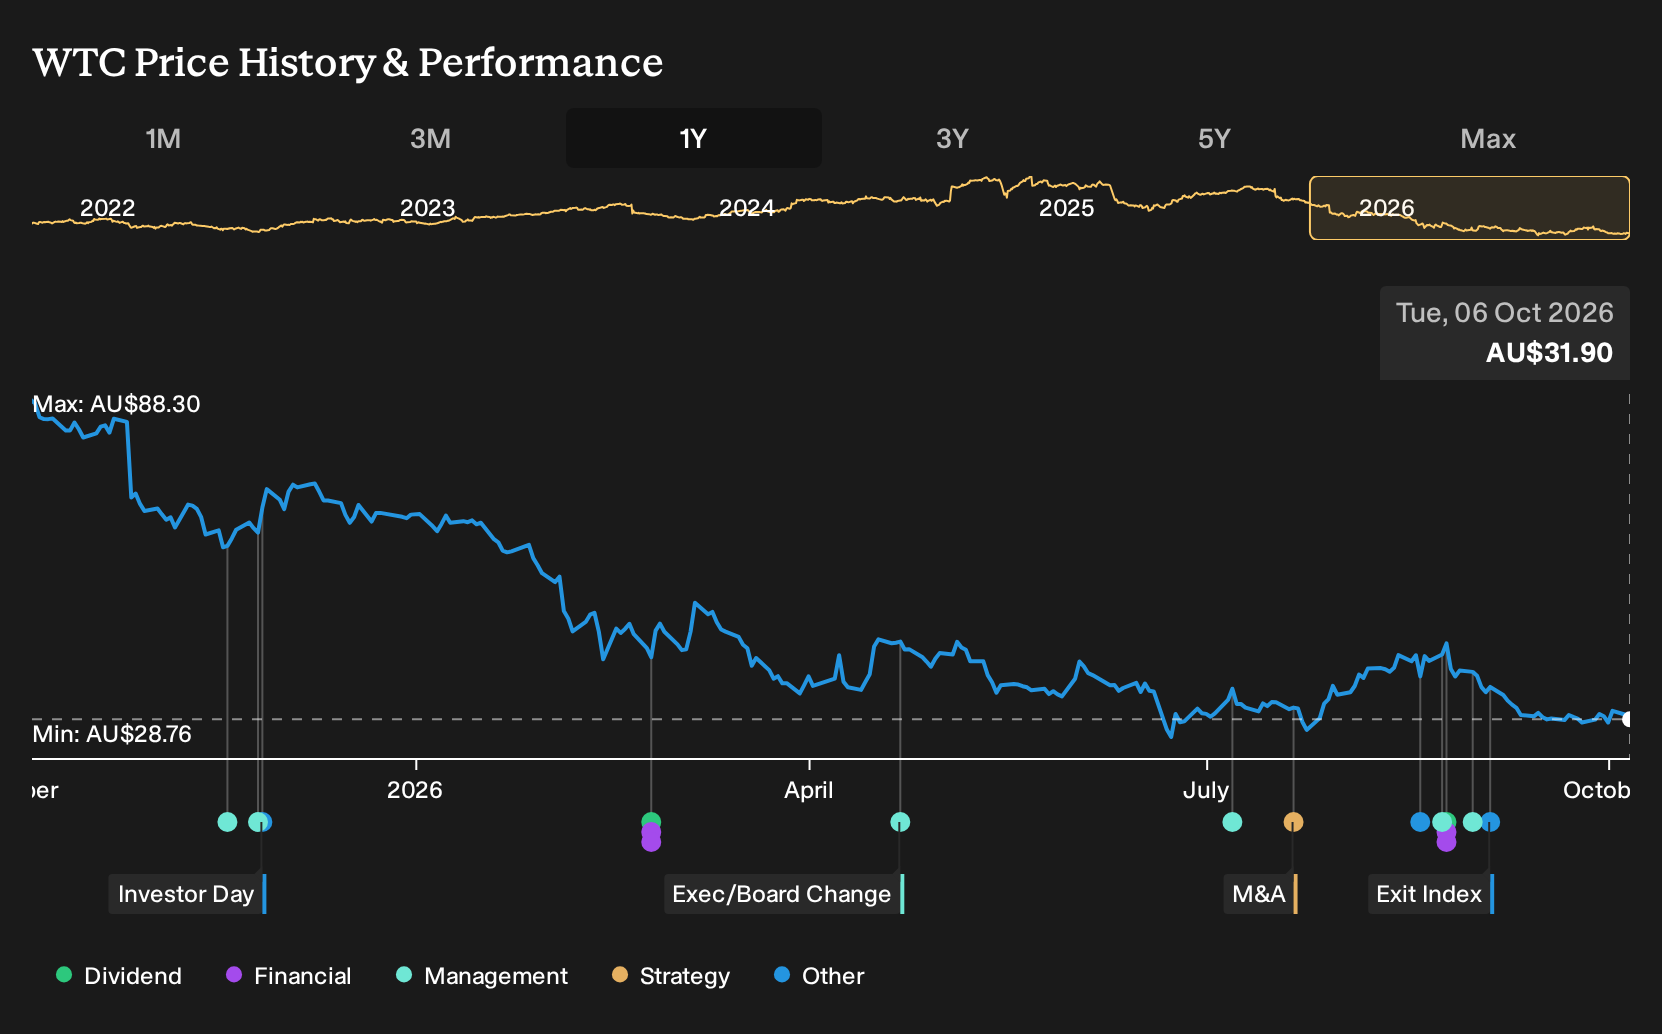
If you had looked at WiseTech Global in early October 2025 and decided to wait for clearer signals before acting, the past year just put a hard number on that choice. Investors who held WiseTech Global over the past year are down 62.6%, including dividends. With fresh headlines about governance, regulatory probes and AI restructuring now in focus, which assumptions about growth, pricing power and leadership could you have tested back at the starting line?
WiseTech Global is not the only name tied to this theme. Zero in on 16 top copper producer stocks and compare how each one is priced.
The Two WiseTech Global Stories Investors Had To Weigh
The shares cost A$88.3 at the start of the period, and anyone looking at WiseTech Global then had to choose which story felt more realistic.
The bullish narrative pointed to a Fair Value of A$125, the price those assumptions implied, based on revenue rising 35.8% a year and profit margins holding near 25.0% as the unified CargoWise model and E2open integration expanded the addressable market.
The bearish view anchored on a Fair Value of A$82.08, with revenue growth assumptions trimmed to 33.9% and margins easing to 22.6% as rising regulation, customer concentration and acquisition risks weighed on the outlook.
What The Evidence Did To The WiseTech Global Argument
The clearest test of the WiseTech Global thesis came from its 2026 numbers. Revenue moved from US$397.7m in H2 2025 to US$723.9m in H2 2026 and net income rose from US$94.3m to US$110.6m, which backed the growth side of the bullish story. Net margin slipping from 23.7% to 15.3% challenged the assumption of resilient profitability. Overall, the evidence cut both ways.
The takeaway is simple. When a growth pitch leans on rising margins as well as fast revenue, you need to track all three lines: sales, profit and net margin, every results season.
What WiseTech Global’s Lower Price Now Assumes
WiseTech Global trades at A$31.9 today, after a fall of 62.6% over the past year. The selected Narrative’s Fair Value sits above the current price and leans on a recovery story built around AI-led products, the new CargoWise model and the E2open acquisition.
Your question now is simple. For this drop to hint at opportunity rather than pure warning, a buyer must believe the new transaction pricing, E2open integration and industry digitisation can support higher margins even if organic growth stays slower.
"The rollout of the new unified, transaction-based CargoWise commercial model (the "Value Pack"), which removes seat-based pricing and bundles advanced AI-driven workflow and management engines, is expected to accelerate market penetration, reduce adoption friction, and open the SME market, resulting in significant recurring revenue uplift and higher customer retention as user engagement scales with transaction volumes."
One Narrative disagrees with today's price. → See where this Narrative says WiseTech Global should trade
Another Way To Read WiseTech
WiseTech Global pushes logistics software deeper into daily workflows. You can still look one step further out.
Every workflow tool needs somewhere to run. That points to strong demand for cloud capacity and reliable software platforms.
One large ecosystem player concentrates on that layer, selling cloud infrastructure, workplace software and AI tools that fit into business routines.
Its pitch is simple and direct. Help enterprises build, secure and automate their own systems, then charge as usage spreads.
If logistics customers rely more on AI and connected tools, that dependence on large cloud platforms could become even more significant.
One Narrative has already put a figure on it. → Uncover the company trading 22% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com