
Industrial and Commercial Bank of China (SEHK:1398) Approved Its Interim Dividend, Is The Upside Already Priced In?
Industrial and Commercial Bank of China (SEHK:1398) has just approved a 2026 interim cash dividend and fully redeemed its USD 6.16b undated Additional Tier 1 capital bonds, reshaping both shareholder payouts and its capital structure.
At a share price of HK$7.58, Industrial and Commercial Bank of China has logged a 19.56% year-to-date share price return, while the 1-year total shareholder return of 41.21% and very large 3- and 5-year total shareholder returns suggest momentum has been building over time.
Compare this Industrial and Commercial Bank of China update with other income focused opportunities by scanning 162 dividend fortresses, which highlights cash returns and balance sheet strength.
Bulls see Industrial and Commercial Bank of China using dividend cash and AT1 redemption to underline value. Bears worry the rally already prices that in. The valuation work now has to show which story fits the numbers.
Most Popular Narrative: 9% Undervalued
Set against a narrative fair value of HK$8.33 and a last close of HK$7.58, Industrial and Commercial Bank of China is being framed as modestly undervalued, with that gap resting on how its core banking engine and newer fee streams hold up together.
The acceleration of digital transformation is expanding ICBC's reach, as evidenced by rapid growth in mobile banking (MAU >265 million), increased open banking transaction volumes (CN¥249 trillion), and the integration of AI in risk management and customer operations, all of which should significantly enhance long-term cost efficiency and support margin expansion.
Increased penetration and demand for personal loans, digital finance, and wealth management, driven by urbanization, a growing middle class, and focused product innovation, are likely to boost fee and commission income, diversify revenue streams, and mitigate pressure on net interest margins.
See why 46 investors see Industrial and Commercial Bank of China as 9% undervalued.
Result: Fair Value of HK$8.33 (UNDERVALUED)
Still, the narrative around Industrial and Commercial Bank of China can weaken if policy driven lending drags on returns or if fintech competition erodes fee income.
Find out about the key risks to this Industrial and Commercial Bank of China narrative.
Another View On Industrial and Commercial Bank of China’s Valuation
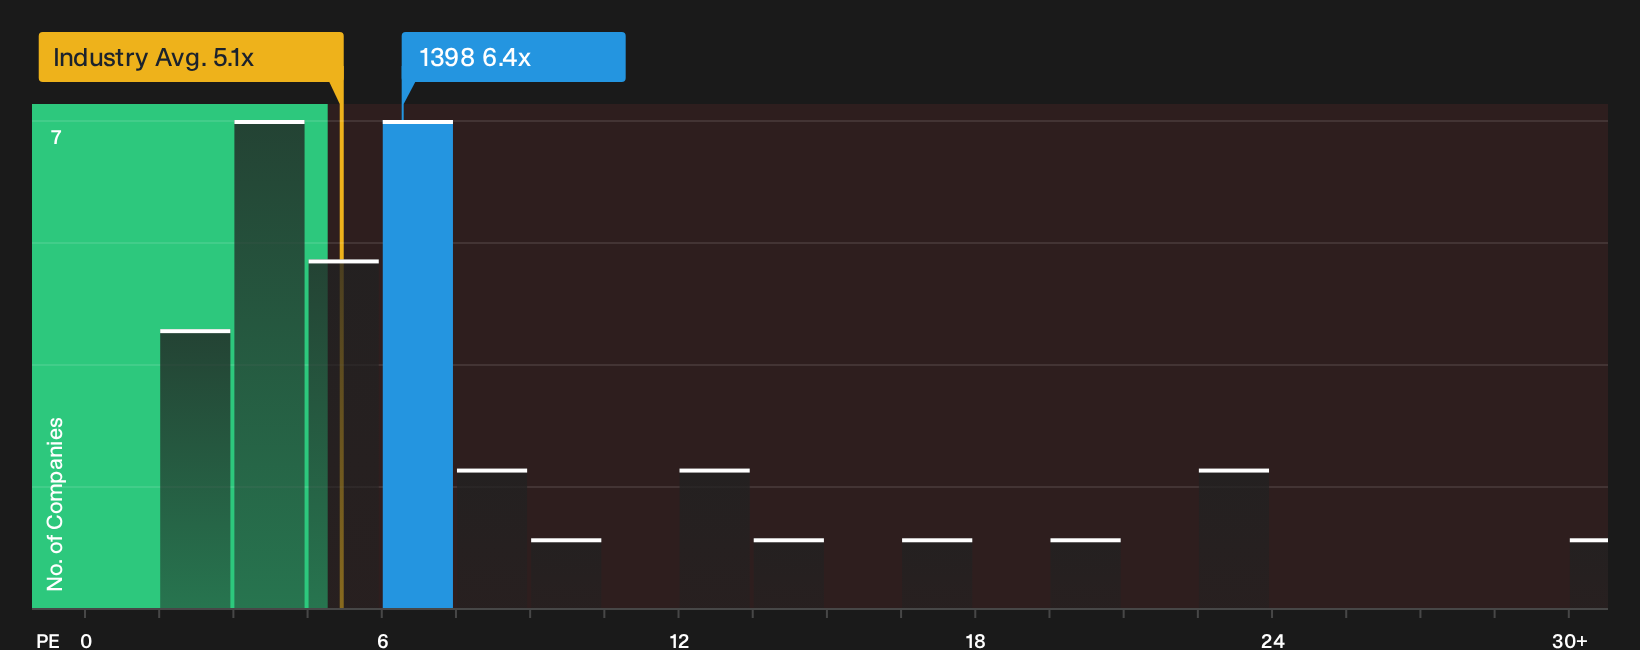
There is a catch. Industrial and Commercial Bank of China looks inexpensive compared with the narrative fair value of HK$8.33. However, its current P/E of 6.4x is above the Hong Kong Banks industry average of 5.1x and just below its own fair ratio of 7.6x. This suggests less obvious upside and more valuation risk if sentiment weakens.
To see how that P/E gap could close in either direction, and what the fair ratio implies for potential future re rating, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around Industrial and Commercial Bank of China feels finely balanced, use the data to pressure test it for yourself. To see what is driving the more optimistic stance in that picture, review the 4 key rewards
Looking for more investment ideas beyond Industrial and Commercial Bank of China?
If you want to round out your view beyond Industrial and Commercial Bank of China, it can be useful to scan fresh ideas before the next wave of results.
- Target potential mispricing by reviewing companies that screen as 185 high quality undervalued stocks based on strong cash flows and solid financial footing.
- Prioritise resilience by checking a list of solid balance sheet and fundamentals (206 results) that can help you focus on businesses with room to handle shocks.
- Look for opportunities by tracking 615 high quality undiscovered gems that pair quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com