
Aequs Limited's (NSE:AEQUS) Path To Profitability
Aequs Limited (NSE:AEQUS) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. Aequs Limited, a contract manufacturing company, engages in the provision of integrated products solutions in India, the United States of America, France, Hong Kong, Sweden, United Kingdom, Germany, and internationally. The ₹192b market-cap company posted a loss in its most recent financial year of ₹1.1b and a latest trailing-twelve-month loss of ₹1.7b leading to an even wider gap between loss and breakeven. As path to profitability is the topic on Aequs' investors mind, we've decided to gauge market sentiment. In this article, we will touch on the expectations for the company's growth and when analysts expect it to become profitable.
According to the 5 industry analysts covering Aequs, the consensus is that breakeven is near. They anticipate the company to incur a final loss in 2027, before generating positive profits of ₹357m in 2028. The company is therefore projected to breakeven around 2 years from now. What rate will the company have to grow year-on-year in order to breakeven on this date? Using a line of best fit, we calculated an average annual growth rate of 80%, which is extremely buoyant. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
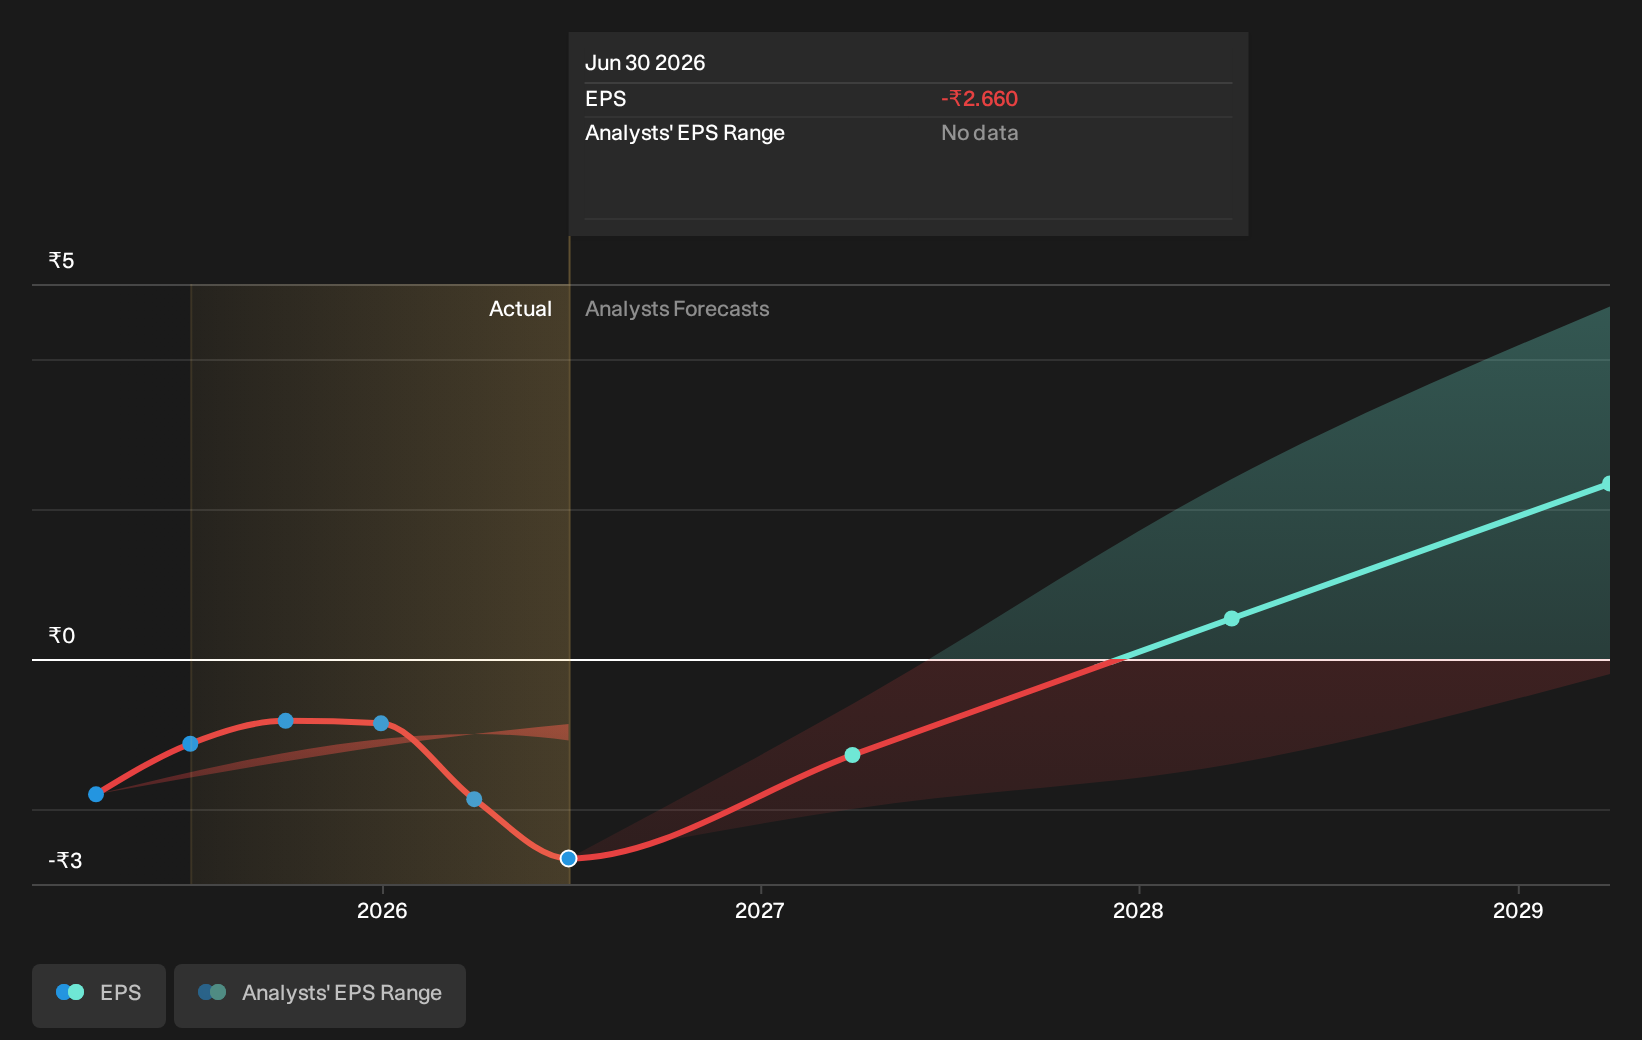
Given this is a high-level overview, we won’t go into details of Aequs' upcoming projects, though, take into account that by and large a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
View our latest analysis for Aequs
One thing we would like to bring into light with Aequs is its relatively high level of debt. Generally, the rule of thumb is debt shouldn’t exceed 40% of your equity, which in Aequs' case is 47%. Note that a higher debt obligation increases the risk around investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on Aequs, so if you are interested in understanding the company at a deeper level, take a look at Aequs' company page on Simply Wall St. We've also compiled a list of essential aspects you should further examine:
- Historical Track Record: What has Aequs' performance been like over the past? Go into more detail in the past track record analysis and take a look at the free visual representations of our analysis for more clarity.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Aequs' board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.