
Castle Biosciences Stock In Focus After Melanoma Test Data and Eczema Study
- Castle Biosciences reported new DecisionDx-Melanoma data from a 2,799-patient prospective study and separate analyses at EADV 2026, alongside a published AdvanceAD-Tx study in atopic dermatitis highlighting clinical need and patient interest in molecular testing.
- The combination of melanoma risk stratification data and atopic dermatitis molecular profiling research points to Castle Biosciences sharpening its focus on clinically validated, higher-value diagnostic decision tools across dermatology.
- We will now look at how Castle Biosciences' expanded evidence in melanoma and atopic dermatitis reshapes the broader investment narrative.
Castle Biosciences Investment Narrative Recap
To own Castle Biosciences, you need to believe that focused dermatology diagnostics and a broader precision testing menu can eventually support profitable scale, even with heavy reimbursement scrutiny. The near term story still hinges on execution in core dermatology and Barrett’s esophagus while containing sales and R&D expense as test volumes evolve.
The main short term catalyst is evidence converting into payer coverage and physician usage across DecisionDx-Melanoma, TissueCypher and AdvanceAD-Tx. The biggest near term risk remains reimbursement pressure, especially after prior noncoverage decisions. The new data looks clinically important but does not on its own resolve pricing, coverage or utilization questions.
The largest prospective DecisionDx-Melanoma study, covering 2,799 patients, is the announcement that matters most for this update. It offers real world support that low risk i31-SLNB patients showed SLN positivity below 5% and that avoiding SLNB in selected cases still aligned with 99.6% five year recurrence free survival. This directly addresses questions around clinical utility.
For investors, that kind of evidence sits directly alongside Castle Biosciences’ key catalysts and threats. Stronger melanoma data can help physicians justify using the test and gives the firm more to point to in payer discussions. At the same time, reimbursement risk, higher operating costs and competition in molecular diagnostics remain central constraints on how far that evidence carries the business.
Castle Biosciences' current story is anchored in analysts modeling 9.2% yearly revenue growth, with earnings today at a loss of US$12.8 million and a consensus forecast for earnings of US$27.0 million by 2029, which implies an earnings swing of about US$39.8 million. On those assumptions, the analyst narrative points to 2029 revenue of US$443.2 million and US$27.0 million of earnings for that same year.
Uncover why Castle Biosciences' fair value indicates a 32% potential upside to its current price, which could narrow quickly if sentiment shifts.
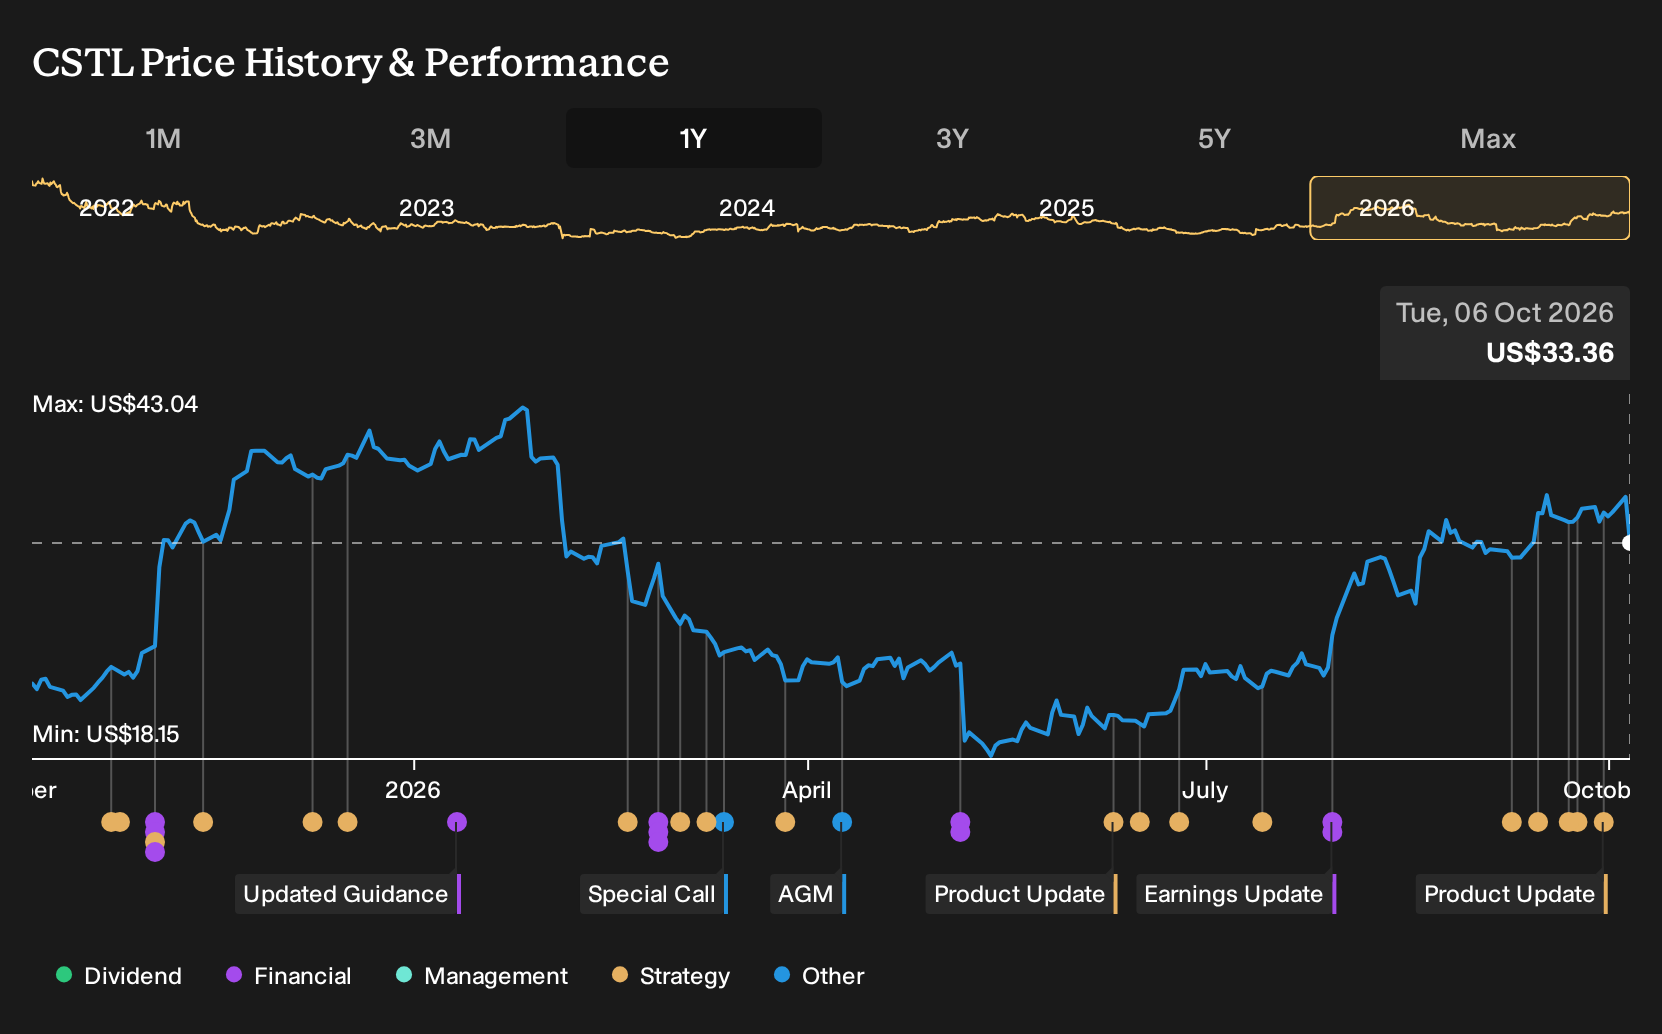
Exploring Other Perspectives
One alternate view focuses squarely on reimbursement risk for Castle Biosciences. The most cautious analysts were penciling in only 7.5% annual revenue growth and earnings of about US$25.8 million by 2029, versus US$27.0 million in the baseline. Those estimates came before this melanoma and atopic dermatitis data, so opinions may shift. You can use that spread in expectations to stress test your own thesis and explore how different coverage outcomes could affect the story.
Explore 2 other Castle Biosciences fair value estimates, including one that suggests it could be worth just $44.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Castle Biosciences research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Castle Biosciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Castle Biosciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Castle Biosciences?
If the Castle Biosciences story has sharpened your thinking about risk, cash flows and quality, it can be useful to compare it with other listed companies that share some of those traits but with different balance sheets, income profiles or payout policies.
- For investors who want resilient businesses with solid finances, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks better than most.
- If income is a priority, scan 8 dividend fortresses that pair higher yields with frameworks aimed at maintaining those payouts.
- If you prefer mispriced quality and a potential margin of safety rather than chasing stories, review 27 high quality undervalued stocks that combine fundamental strength with compressed expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com