
DTE Energy (DTE) Brings Cold Creek Solar Park Online, Is The Discount Still Compelling?
DTE Energy (DTE) just brought the 100 megawatt Cold Creek Solar Park online near Coldwater, Michigan, supplying cleaner power under the MIGreenPower program to support Ford Motor Company’s decarbonization plans.
DTE Energy’s latest solar project arrives as the share price has been choppy, with a 1-day share price return of 2.54% and a 7-day share price return of 4.76%. However, the 90-day share price return is down 15.30% and the 1-year total shareholder return is down 6.86%, while the 3-year total shareholder return of 45.96% points to stronger longer run momentum.
Scan a curated mix of utilities and energy transition players that are moving on fresh project news with our 40 power grid technology and infrastructure stocks to see how DTE Energy compares within the grid upgrade theme.
DTE Energy has rallied off the lows while long term returns still look solid, which puts the focus squarely on valuation. After this latest solar milestone and share price bounce, does the risk reward still lean toward buyers?
Most Popular Narrative: 16% Undervalued
DTE Energy last closed at $128.22, compared with a narrative fair value estimate of about $152.68 that uses a 7.24% discount rate. The current pricing leans toward a discount while still relying heavily on long dated capital projects and regulation going to plan.
Growing contracted and potential data center load, including 2.4 GW already under agreement and a further 5 to 6 GW in the large load pipeline, supports a long runway of new generation and storage projects that can add to regulated rate base and future revenue.
Roughly US$5b of planned investment through 2032 to meet Google’s 1 GW capacity needs, including renewables, storage, demand response, and longer term baseload assets, creates a visible project queue that can support earnings from capital deployed into regulated infrastructure.
See why 12 investors see DTE Energy as 16% undervalued.
Result: Fair Value of $152.68 (UNDERVALUED)
Still, the DTE Energy story could change quickly if regulators tighten cost recovery for big projects or if storm related outages lead to higher reliability penalties.
Find out about the key risks to this DTE Energy narrative.
Another View: DTE Energy Through The Earnings Multiple Lens
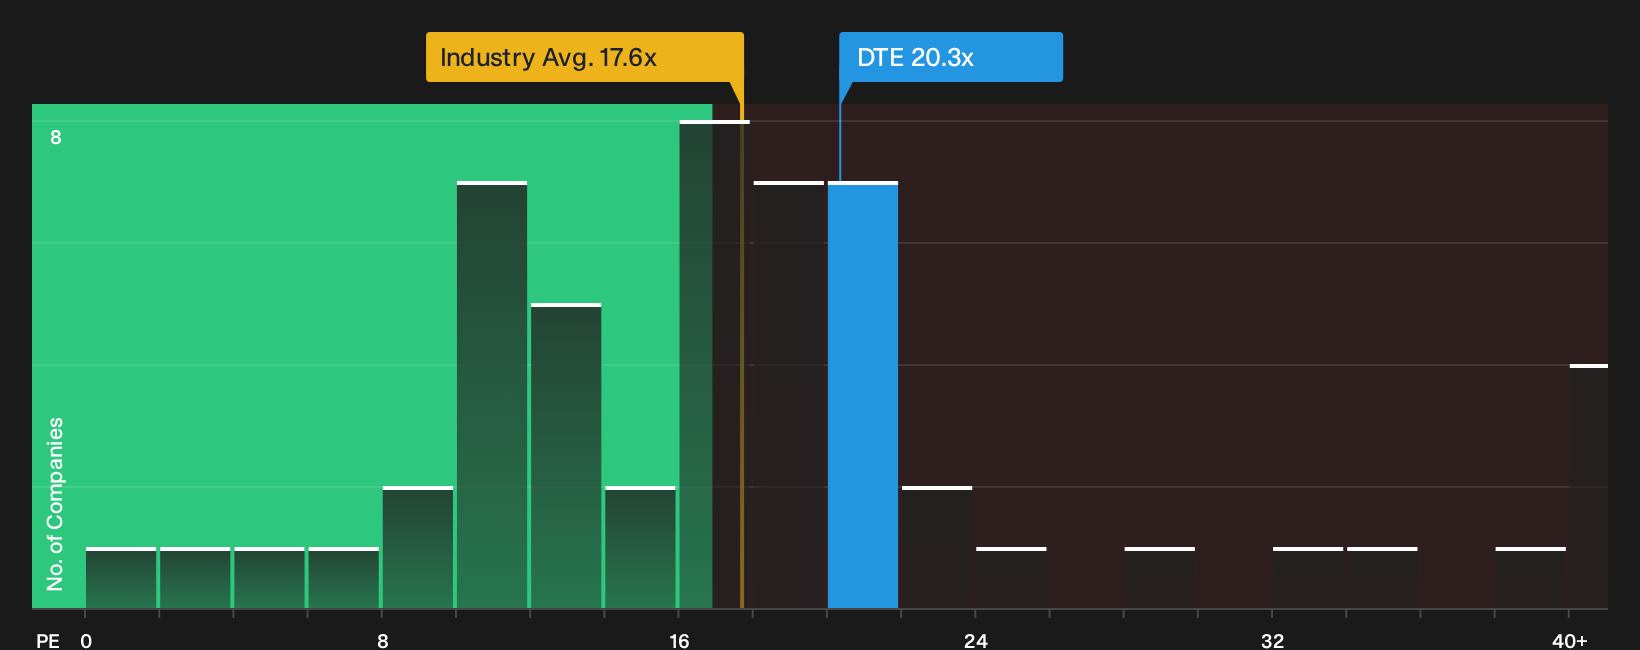
DTE Energy screens differently when you step away from fair value models and look at the straight P/E. The stock trades around 20.3x earnings, compared with 17.6x for the global integrated utilities group and 20.2x for direct peers, while the fair ratio sits slightly higher at 21.1x.
That mix points to a share price that is a bit rich versus the wider industry, closer to in line with peers, and still below where the fair ratio suggests the market could drift over time. For investors, it raises a simple question: Is paying above the sector average for DTE Energy a reasonable trade off for the earnings profile implied in the current narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the DTE Energy story can pull you in either direction, so move fast on the data and shape your own thesis with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond DTE Energy?
If DTE Energy has sharpened your focus on quality and pricing, broaden your watchlist now so you do not miss the next compelling setup.
- Target higher yield potential by reviewing companies in the 8 dividend fortresses that could complement a regulated utility like DTE Energy.
- Tilt your portfolio toward quality at a discount by scanning the 27 high quality undervalued stocks that pair fundamentals with more attractive pricing.
- Strengthen downside protection by focusing on the 31 resilient stocks with low risk scores that score well on resilience when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com