
Church & Dwight (CHD) Looks Undervalued On Paper, Is Its Premium P E Too Rich?
Church & Dwight (CHD) has drawn fresh attention after recent trading left the share price at US$96.54. Performance has been mixed over the past month and the past 3 months, and stronger so far this year.
The share price move to US$96.54 comes after a modest 1-day share price return of 0.92% and a year-to-date share price return of 16.82%. The 1-year total shareholder return of 8.64% points to momentum that has cooled but not reversed over a longer stretch.
Compare Church & Dwight’s recent run with a handpicked group of resilient consumer-focused businesses in our 31 resilient stocks with low risk scores.
Church & Dwight now trades below both analyst targets and an intrinsic value estimate, despite recent gains. Is that a simple pricing gap, or a signal that the market’s caution on this stock makes sense?
Most Popular Narrative: 8% Undervalued
On the most followed view, Church & Dwight screens as modestly undervalued, with a fair value of about $105 against the recent $96.54 close. This puts the spotlight on what drives that gap.
The trajectory of e commerce and online sales, with Church & Dwight's online channel now accounting for roughly 25% of global consumer sales, continues to support a mix shift toward higher margin, data rich distribution that can affect revenue and earnings quality. Consumer focus on health, hygiene and wellness remains a key tailwind, with THERABREATH, HERO and TOUCHLAND all operating in categories where household penetration for these brands is well below category levels. This gives Church & Dwight a path to pursue incremental volume and pricing mix that feeds into both revenue and net margins.
See why 13 investors see Church & Dwight as 8% undervalued.
Result: Fair Value of $105.11 (UNDERVALUED)
Still, Church & Dwight faces pressure from higher SG&A and weaker vitamin gummies, which could strain margins and blunt the e commerce growth story.
Find out about the key risks to this Church & Dwight narrative.
Another View: What Church & Dwight’s P/E Is Telling You
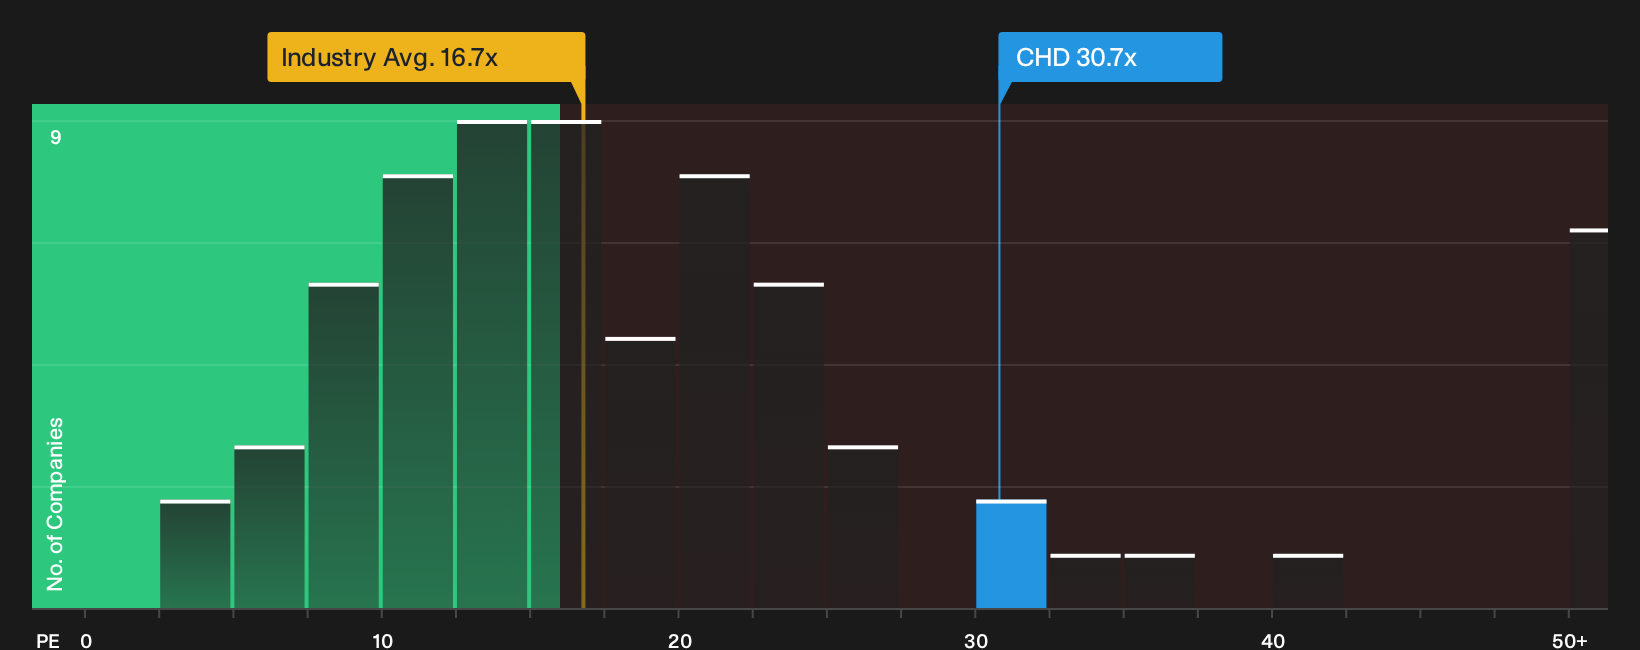
There is a very different picture once you stop looking at Church & Dwight through a fair value model and focus on the market multiple. The stock trades on a P/E of 30.7x, which is far richer than the Global Household Products industry on 16.6x and a peer average of 21x. It also sits well above a fair ratio of 19.3x that the market could move toward, which points to real valuation risk if sentiment cools.
For anyone weighing these signals against the earlier fair value work, it is worth asking which story feels more fragile: the discounted cash flow that suggests upside, or a market multiple that already prices Church & Dwight at a premium on almost every comparison.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Church & Dwight so far. If you want to move fast and base your stance on the underlying data, start by weighing its 3 key rewards and 1 important warning sign.
Looking for more Church & Dwight sized investment ideas?
If you rely only on Church & Dwight, you could miss other opportunities, so put a few minutes into scanning these data driven stock ideas today.
- Target sturdier portfolios by focusing on companies with strong balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a sensible price by filtering for companies that appear underappreciated through the 27 high quality undervalued stocks.
- Build a list of potential income anchors by checking companies with higher yields in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com