
W. R. Berkley (WRB) Faces A Valuation Test As Specialty Insurance Growth Holds Up
W. R. Berkley (WRB) is back in focus after recent share performance data showed mixed returns, with the stock slightly lower over the past year but still strongly positive over the past 3 years.
Recent trading has been choppy, with W. R. Berkley’s share price slipping over the past quarter but still edging higher year to date. The 1 year total shareholder return has declined, while the 3 year total shareholder return remains strongly positive, suggesting longer term momentum has held up better than the recent trend.
Spot potential rebounds by lining up W. R. Berkley’s mixed returns against our curated 31 resilient stocks with low risk scores, which has held up better through recent swings.The share price is now almost level with the average analyst target, yet internal fair value estimates suggest far more upside. Where does W. R. Berkley’s true valuation sit between those two markers?
Most Popular Narrative: 0% Overvalued
W. R. Berkley last closed at $69.65, almost level with the $69.41 fair value implied by the most followed narrative. The market is treating the stock as roughly fully priced while assuming that current underwriting and capital return trends hold.
The expanding complexity of global business and assets is driving demand for specialty insurance solutions. W. R. Berkley is building on this with mid single digit gross and net premium growth in its Insurance segment, alongside current accident year ex cat combined ratios around 89%, which can support revenue and underwriting income.
See why 6 investors see W. R. Berkley as 0% overvalued.
Result: Fair Value of $69.41 (ABOUT RIGHT)
Still, softening commercial pricing and the pullback in reinsurance premiums mean W. R. Berkley’s underwriting margins could come under pressure if loss trends worsen.
Find out about the key risks to this W. R. Berkley narrative.
Another View: W. R. Berkley Through a Cash Flow Lens
Analysts using valuation multiples see W. R. Berkley as fully priced, with the stock trading on a P/E of about 14x compared with an estimated fair P/E of 10.2x. Our DCF model provides a different perspective and points to a fair value of $124.79, above the current $69.65. Which framework do you rely on when the gap is this wide?
For a closer look at the assumptions behind this cash flow outcome and how sensitive it is to small changes in growth or discount rates, Look into how the SWS DCF model arrives at its fair value.
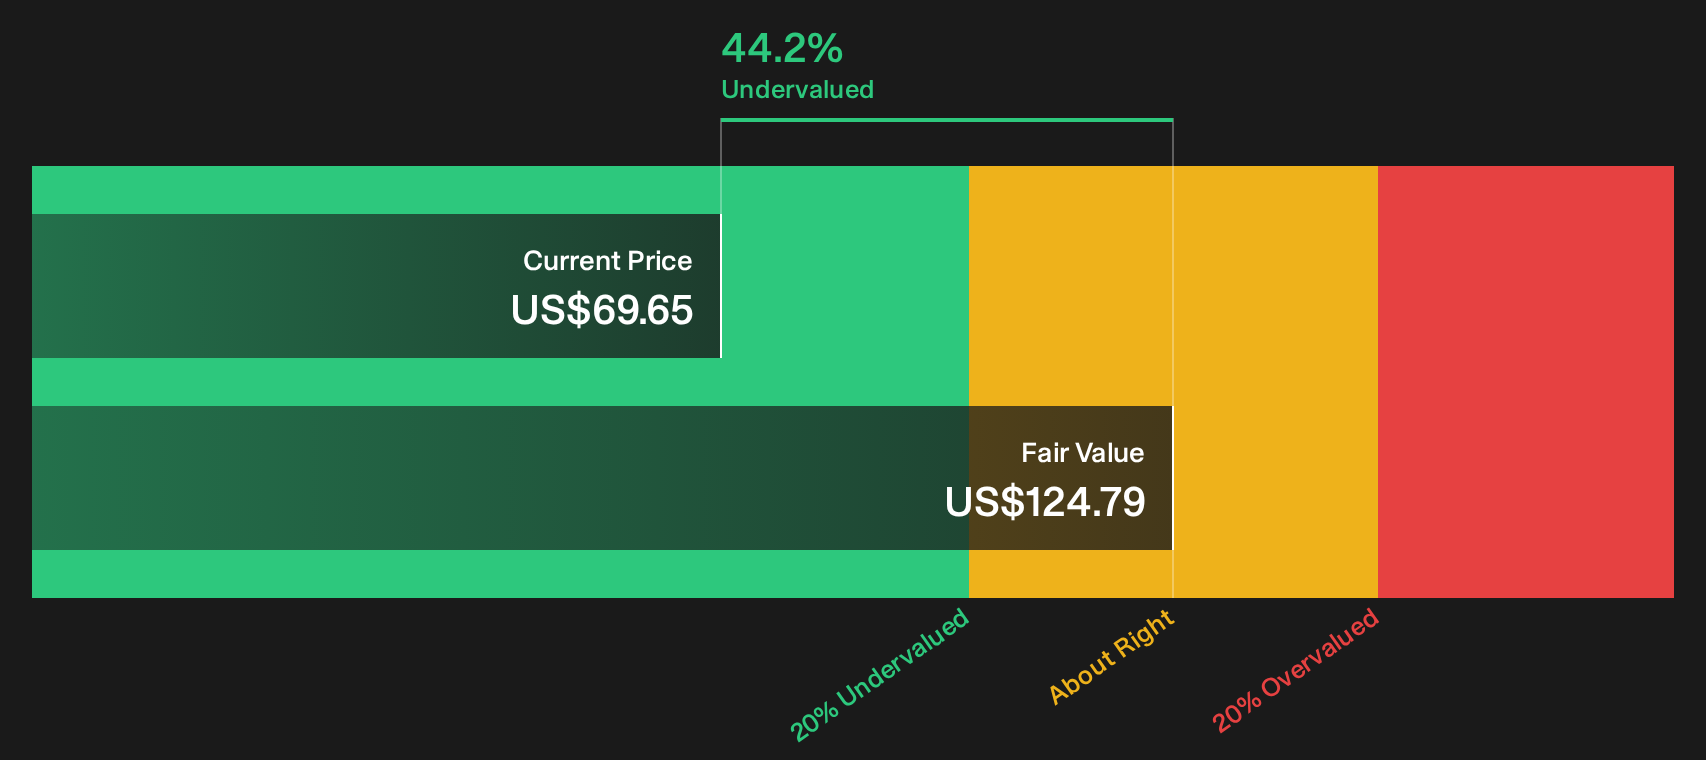
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out W. R. Berkley for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on W. R. Berkley so far, or a clear opportunity hiding in plain sight. If you want to move quickly and build your own conviction, start by weighing its 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond W. R. Berkley?
If W. R. Berkley has sharpened your focus on quality, broaden your watchlist now with a few focused stock ideas sourced from the Simply Wall St screener.
- Target resilience first and look for companies that prioritize capital preservation and steady performance through our 31 resilient stocks with low risk scores.
- Seek value where quality and price still align and review our 27 high quality undervalued stocks before those opportunities narrow.
- Strengthen your income stream by filtering for reliable cash payers using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com