
Why ALSO Holding (SWX:ALSN) Is Back In The Spotlight
ALSO Holding (SWX:ALSN) is back in focus after cybersecurity provider Huntress selected its pan European distribution network to push the Huntress Agentic Security Platform into 31 countries through the ALSO Cloud Marketplace.
Investors have started to re-engage with ALSO Holding, with the share price up 2.1% over the past week and 2.0% over the last month to CHF199.2. This comes even though the year to date share price return has fallen 7.6% and the 1-year total shareholder return is down 13.3%, signaling improving short-term momentum against a weaker multi-year experience for long-term holders.
Compare ALSO Holding's latest cybersecurity push with a curated group of resilient tech distributors and service providers using the 228 resilient stocks with low risk scores to see which businesses combine growth exposure with lower risk.
After the Huntress announcement and a short term bounce in ALSO Holding, the stock still trades below both analyst targets and intrinsic value estimates. Is that discount a margin of safety or a warning sign?
Preferred P/E of 20x for ALSO Holding: Is it justified?
Valuation for ALSO Holding currently leans in investors' favour, with the stock trading at a P/E of 20x while simple fair value checks, analyst targets and a discounted cash flow estimate all sit higher than the last close of CHF199.2.
The P/E ratio measures how much investors are paying today for each unit of earnings. For a technology distributor with a broad services layer like ALSO Holding, that matters because earnings quality, growth prospects and balance sheet risk can all influence what multiple the market is willing to assign.
ALSO Holding is flagged as good value on several fronts. The P/E of 20x is slightly below the European Electronic industry average of 20.3x and far below a peer group average of 84.4x, which suggests investors are paying less for each unit of earnings than they are for comparable businesses. It is also screened as attractive relative to an estimated fair P/E of 29x, a level the market could move towards if sentiment shifts.
That combination is reinforced by other checks. The stock trades at a 7.3% discount to an internal fair value estimate and at a 7.3% discount to an SWS DCF fair value of CHF214.9, while the share price also sits about 16.2% below an average analyst target of CHF231.47. Earnings are described as high quality, profit increased 16.4% over the past year and that rise exceeded the Electronic industry growth of 5.7%, even though earnings over 5 years declined 6.9% per year and forecast growth of 11.1% per year is not described as significant.
ALSO Holding's return on equity of 11.2% is categorised as low and profit margins of 0.9% are slightly below last year, which helps explain why the P/E is not stretched despite recent profit momentum. Dividend yield of 2.63% is not well covered by free cash flows and all funding is classified as higher risk borrowing rather than customer deposits, so the current valuation appears to balance improving earnings quality against capital structure and cash flow coverage questions.
Explore the SWS fair ratio for ALSO Holding.
Result: Price-to-Earnings of 20x (UNDERVALUED)
Still, the thin 0.9% profit margin and reliance on higher risk borrowing mean any setback in demand or pricing could quickly pressure ALSO Holding's earnings profile.
Find out about the key risks to this ALSO Holding narrative.
Another View: ALSO Holding Through The DCF Lens
The P/E points to value in ALSO Holding, yet the SWS DCF model is less generous. On that framework, the shares change hands at CHF199.2 compared with an estimated cash flow value of CHF214.9, a 7.3% gap that looks smaller once execution and funding risks are factored in. How much weight do you put on a spreadsheet versus the market's caution?
Look into how the SWS DCF model arrives at its fair value.
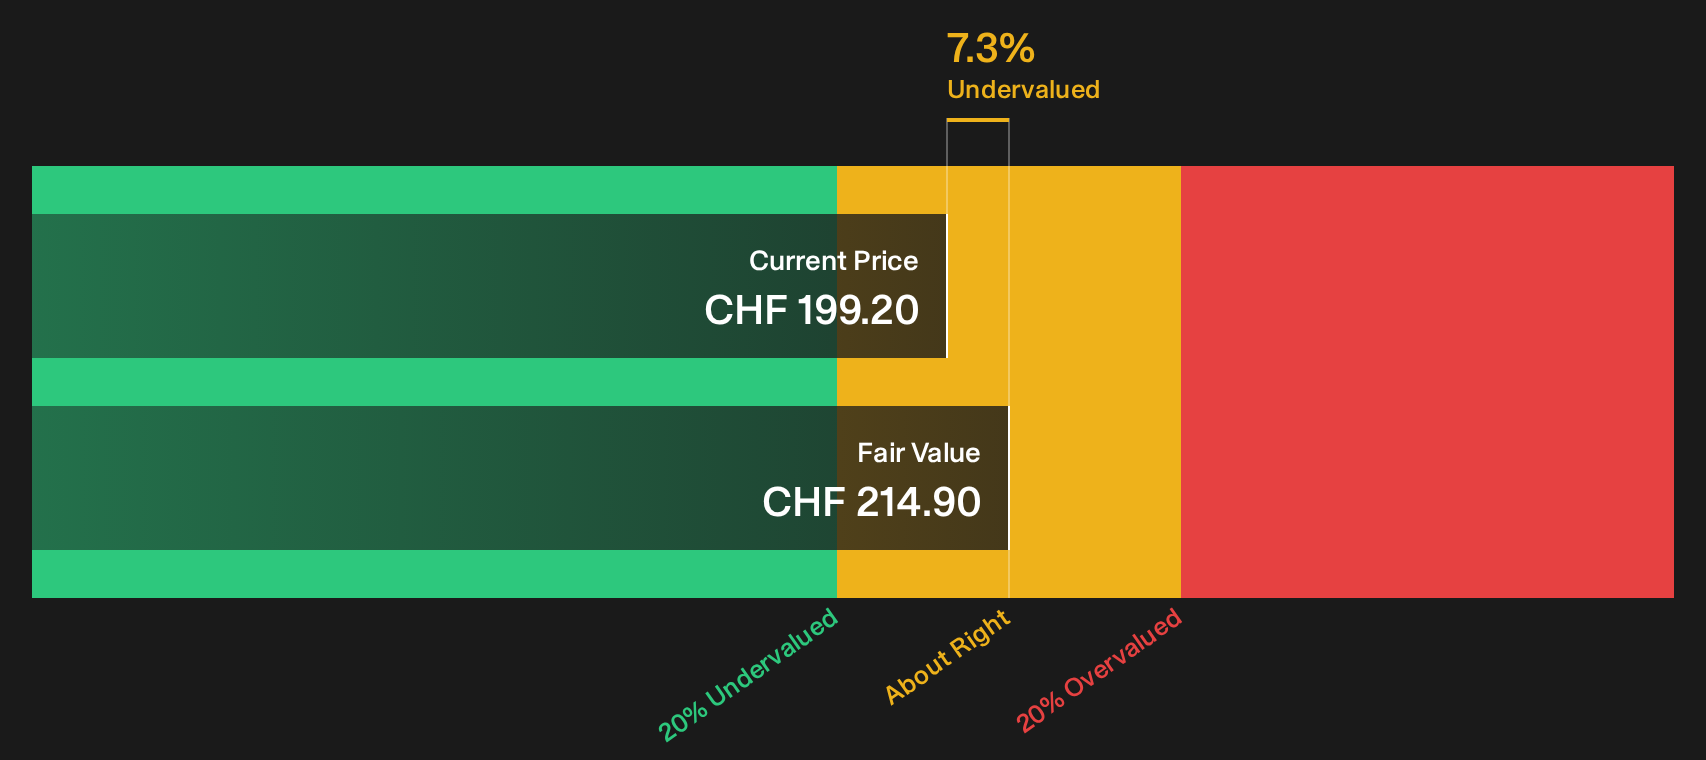
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ALSO Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this combination of value signals and funding questions around ALSO Holding feels finely balanced, act promptly, review the full data set, and weigh both sides using the 4 key rewards and 1 important warning sign.
Looking for more ALSO Holding style investment ideas?
If ALSO Holding has sharpened your focus on pricing, quality and risk, do not stop here. Use the Simply Wall Street Screener to search for other opportunities that fit your playbook before the market spots them.
- Target stronger payoffs from mispriced quality by scanning a 182 high quality undervalued stocks that combines healthy fundamentals with attractive entry points.
- Strengthen your defence by reviewing a list of solid balance sheet and fundamentals (206 results) that can help reduce blow up risk in tougher conditions.
- Hunt for potential future standouts early by checking a 614 high quality undiscovered gems that pairs fundamental strength with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com